❌

Normal view

  • ✇Market Wise
  • Amazon’s AWS Chips Top $25 Billion Run Rate. Does This Signal Trouble for Nvidia? David Engle
    Key Points Amazon’s custom-chip business has surpassed a $25 billion annual revenue run rate, driven by strong demand for Trainium AI accelerators and Graviton CPUs that offer meaningful cost savings versus Nvidia hardware. AWS custom-chip capacity is attracting major customers including OpenAI, Anthropic, Meta Platforms, and Uber, while newer Trainium capacity is nearly sold out and future generations are being booked well ahead of launch. Nvidia remains the dominant AI-chip
     

Amazon’s AWS Chips Top $25 Billion Run Rate. Does This Signal Trouble for Nvidia?

27 August 2026 at 12:54

Key Points

  • Amazon’s custom-chip business has surpassed a $25 billion annual revenue run rate, driven by strong demand for Trainium AI accelerators and Graviton CPUs that offer meaningful cost savings versus Nvidia hardware.
  • AWS custom-chip capacity is attracting major customers including OpenAI, Anthropic, Meta Platforms, and Uber, while newer Trainium capacity is nearly sold out and future generations are being booked well ahead of launch.
  • Nvidia remains the dominant AI-chip player, but Amazon’s growing in-house silicon gives AWS greater control over costs and infrastructure while creating a meaningful competitive threat to Nvidia, AMD, and Intel.

Amazon (AMZN) never ceases to amaze. The company’s custom chip business has surpassed a $25 billion annual revenue run rate, driven by the fast-growing demand for its Trainium AI accelerator chips and Graviton central processing units (“CPUs”) for cloud computing.

The reason is simple. Amazon Web Services (“AWS”) custom chips are more affordable to use, and its customers want lower-cost chips than what Nvidia (NVDA) offers.

Amazon is already the runaway e-commerce leader in the U.S., with a 40.5% market share. Meanwhile, AWS – which essentially created the cloud-computing industry – is the world’s largest cloud-infrastructure provider, with 28% global market share as of midyear.

But are there enough value-focused custom-chip customers for AWS to take a big enough bite out of Nvidia’s dominant AI-chip market share of roughly 80% to 87%?

The Lower-Cost Appeal of AWS Custom Chips

The most obvious appeal here is affordability. Sometimes, you can get high quality at a fair price, and that seems to be the case with Amazon’s chips.

AI developers who use AWS chips can save 30% to 40%, while still getting excellent performance, according to Dave Brown, AWS vice president of compute and machine learning.

As he told Yahoo Finance, “That’s what our customers are looking for, is to constantly get more compute and more performance, and then super importantly, at a lower price.”

Who wouldn’t want that combination?

Amazon notes that it builds its chips “from the ground up” to accommodate specific workloads. The end products are Amazon’s Trainium AI chips, Graviton cloud-computing chips, and Nitro chips, which provide the storage, networking, and security behind AWS’s cloud infrastructure.

So, what makes Amazon’s custom-built AI chips different from the graphics processing units (“GPUs”) that Nvidia creates? GPUs are designed for general-purpose workloads, not specific workloads. Amazon’s AI chips are custom-designed to handle the specific workloads its customers run.

Now, Amazon is not the first company to build custom chips for its clients to use. Alphabet (GOOGL), for example, was an early pioneer in that area, with its customized tensor processing unit (“TPU”) chips that deliver GPU-like performance for less money.

And money matters when it comes to AI, considering global AI spending is expected to reach nearly $2.6 trillion in 2026, according to research by Gartner. Any money businesses can save on AI costs is a win, with investors growing weary of tech companies’ wild spending sprees – and dinging their stock prices as a result.

Even a modest improvement in AI performance and efficiency can save a company millions of dollars a year. CloudExpat, a cloud-infrastructure optimization company, tested AWS Trainium1 chips against Microsoft (MSFT) Azure’s ND H100 and Nvidia GPUs in 2025 (Google’s TPU was also tested, but for this article, we’re focusing on the comparison between AWS and Nvidia).

Using dozens of highly technical tests, CloudExpat revealed that companies looking to train a GPT-4-scale AI model could save millions in cloud spend by using AWS Trainium chips versus Nvidia GPUs.

And Amazon has continued to improve the efficiency and price-performance of Trainium chips with each new generation. Amazon’s Trainium2 is reportedly four times faster than Trainium1 and cut costs by roughly 35% compared with Nvidia’s H100 chips, according to the Tech Buzz. Amazon says its Trainium3 chips offer up to 40% better price-performance than Trainium2.

And that’s just for AI training. When it comes to actually running AI models, where cost per query can add up quickly, Amazon says its Inferentia2 chips offer up to 50% lower cost per inference than GPU-based chips. When you consider that AWS sees billions of inference queries every day, that makes a massive difference.

Of course, there are other considerations here… For example, adopting AWS Trainium chips to replace Nvidia GPUs would require a company to abandon Nvidia’s very sticky – and familiar – CUDA ecosystem and implement AWS’s Neuron platform. And that’s not free.

But the chip performance itself is likely worth the swap.

A Growing Customer List Has AWS Chips Sold Out for Years

Companies are increasingly noticing the benefits of Amazon’s custom chips and signing up as customers. In February, OpenAI committed to using 2 gigawatts (“GW”) of Trainium capacity to power its frontier models starting in 2027. This development expanded the companies’ existing $38 billion multiyear agreement by $100 billion over eight years.

AI giant Anthropic followed suit in April, committing to spend more than $100 billion over the next 10 years on AWS technologies – primarily its Trainium and Graviton chip capacity. Amazon noted that Anthropic will “secure up to 5 [GW] of capacity to train and power their advanced AI models, including significant Trainium3 capacity.”

But it’s not just the big players investing in Trainium. Smaller startups such as TwelveLabs, Neura Robotics, Odyssey, Poolside, Decart, Karakuri, NetoAI, Splash Music, and Metagenomi Therapeutics (MGX) are among the many companies turning to AWS custom chips as a cheaper alternative to Nvidia.

Due to this demand, Trainium3 chip capacity is practically sold out. And AWS’s Trainium4 chips, which won’t even be released until 2027 or 2028, already have much of their capacity booked.

Even Amazon’s Graviton processors are flying off the shelves. According to Amazon, more than 130,000 customers use Graviton-based servers. And more than half of AWS’ new processing power runs on Graviton chips.

In April, Meta Platforms (META) became one of the world’s largest Graviton customers when it signed a deal to deploy tens of millions of Graviton cores to power its agentic AI workloads.

And global rideshare leader Uber Technologies (UBER) heavily employs AWS Trainium3 and Graviton4 chips to improve its infrastructure and make customer experiences smarter and faster.

Like its Trainium counterparts, Graviton processors are gaining popularity thanks to their significantly better – around 40% – price-performance and 45% savings compared with x86-based CPUs. The Tech Buzz estimated that, based on cost-optimization analyses from cloud-management platforms, “a typical Fortune 500 company running 10,000 instances on AWS could save $8-12 million annually by migrating from Intel-based instances to Graviton3.”

Amazon’s custom chips clearly have tons of momentum, which it rode to the milestone $25 billion-plus annual revenue run rate.

What Amazon Custom Chips’ $25 Billion Annual Run Rate Means for the Company and the Industry

Calling the $25 billion-plus annual revenue run rate impressive would undersell its importance. Amazon reaching this figure is changing the semiconductor and AI-infrastructure industries. Just think about it… AWS went from using someone else’s chips and selling access to those chips through the cloud to creating and selling capacity for its own silicon.

For less than the cost of an Nvidia GPU, Amazon can customize chip hardware to optimize specific types of workloads. That is a massive development.

Just as massive: Amazon is no longer solely dependent on paying companies like Nvidia or Intel (INTC) for their hardware. AWS does still buy – and will likely continue to buy – other companies’ chips to satisfy customer demand. But Amazon’s custom chips now make it a direct competitor in the market.

AWS’s 2026 second-quarter financials prove that its custom chips have had a huge impact on the semiconductor market. The results include:

  • $42.2 billion in net sales, a 37% year-over-year increase, which was the fastest segment growth in 18 quarters
  • More than $25 billion in annual revenue run rates for its custom-chip and AI businesses, with year-over-year growth in triple digits
  • $16.6 billion in operating income, up 64% year over year
  • An operating margin of 39.4%, up from 32.9% during the second quarter of 2025
  • An annualized revenue run rate of $169 billion

Amazon’s custom-chip success adds even more revenue to the cash-generating machine that is AWS. As profitable as Amazon is beyond technology (remember, Amazon is far and away the No. 1 e-commerce retailer in North America), AWS accounted for roughly 60% of the entire company’s operating profit in 2025.

Where does Amazon’s chip business stand against heavyweights like Nvidia, Advanced Micro Devices (AMD), and Intel? Before comparing, it’s important to note that Amazon CEO Andy Jassy has said that AWS custom chips would double their current $25 billion revenue if the company sold its physical chips – not just chip capacity – to external customers.

In his annual letter to shareholders published in April, Jassy noted:

If we were a standalone chip company, our chips would be generating over $50 billion in annual revenue.

So, when comparing revenue with its competitors, Amazon is right there… even if its chips are not currently generating more than $50 billion in annual revenue. Nvidia remains the clear leader, with its AI-driven Data Center segment generating a company-record $89 billion during its most recent quarter (fiscal second quarter of 2027).

But Amazon is running neck and neck with Advanced Micro Devices and Intel. Advanced Micro Devices’ projected annual data-center run rate of roughly $26.9 billion (based on its actual $6.72 billion second-quarter revenues) sits just ahead of AWS’s $25 billion. And Intel, with a projected $25.04 billion annualized run rate based on its $6.26 billion second-quarter Data Center and AI segment revenue, is virtually tied with AWS.

If you factor in Jassy’s statement that Amazon’s chip business would be valued at roughly $50 billion if it sold its hardware externally, then Amazon blows right past both Advanced Micro Devices and Intel.

Is Amazon’s Stock Undervalued?

If you’re thinking about investing in Amazon, these chip developments are crucial when you consider that AWS generates most of the company’s operating profit every year. And there’s no reason to think the segment won’t keep growing rapidly.

Not only are new chips here or on the way (Graviton5 was released in June, and Trainium4 will arrive in the next year or so), but powerful frameworks and models are, too.

  • Amazon Bedrock AgentCore, which was released last fall, is the system AWS uses most to build and orchestrate enterprise AI agents.
  • Project Rainier in Indiana, which officially launched last October, is one of the world’s largest distributed AI supercomputing clusters. It currently hosts more than 1 million Trainium processors dedicated to training Anthropic’s frontier Claude models.
  • AWS Continuum, released in June, is a new agentic security service that finds and fixes security risks.
  • AWS Transform is an agentic-AI service that supports large-scale framework modernizations.
  • AWS Context is another new service that automatically builds a knowledge graph from existing data to be used by a company’s agents.

That’s just the tip of the iceberg. And there’s no reason to believe AWS will stop innovating.

Amazon has been a wildly successful company for years. A major reason is the foresight it employs in developing brilliant strategies… like developing its own chips. This has already proved to be a market changer.

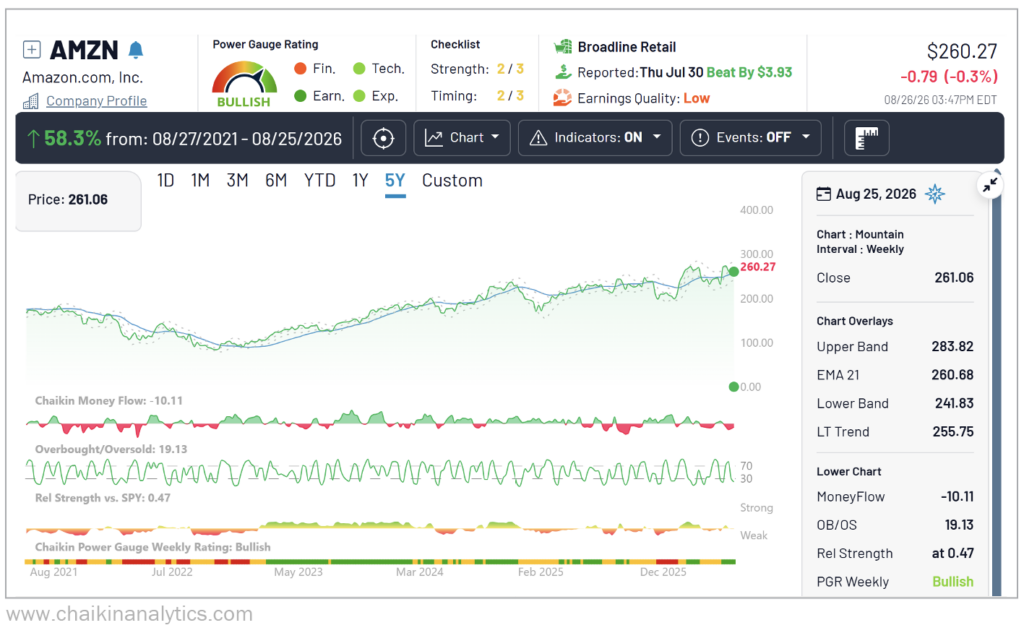
That kind of innovation and confidence in its strategies matters to investors. It’s one reason Amazon’s stock feels undervalued at around $260. The average price target for Amazon is roughly $327, giving the stock around 25% upside.

Amazon stock may not get the splashy spikes like Micron Technology (MU) or Sandisk (SNDK), but it has long been a consistent performer. Year to date, it’s up nearly 15%. And over the past five years, it has gained nearly 57% (largely driven by AWS).

Amazon Power Gauge Rating Bullish

Chaikin Analytics, the investment-research platform founded in 2009 by legendary 60-year Wall Street veteran Marc Chaikin, gives Amazon a “bullish” rating in its Chaikin Power Gauge, a 20-factor stock-rating system that scans more than 5,000 stocks and 2,300 exchange-traded funds.

Chaikin Power Gauge Rating Bullish

Amazon has a long history of innovation and revolutionizing entire industries. It has done that with Amazon Prime and its e-commerce business, its logistics operations, and its enterprise cloud infrastructure. The company’s development of custom AI chips and processors certainly seems to be the next industry changer.

Regards,

David Engle

Editor’s Note: Whitney Tilson called the rise of Apple, Amazon, and Netflix… as well as the collapse of dozens of companies that went bankrupt. Now the former $200M hedge fund firm manager is stepping forward with what he calls the most important financial warning of his 30-year career. He’s sharing two free stock recommendations  (one to buy, one to sell immediately)  along with details of a new proprietary system fueling his predictions. See it all in his free presentation. 

The post Amazon’s AWS Chips Top $25 Billion Run Rate. Does This Signal Trouble for Nvidia? appeared first on MarketWise.
  • ✇Market Wise
  • How to trade the world’s most important trend Brian Hunt
    Today’s issue in preview: How to trade the world’s most important trend This chart shows why you should be bullish and buy stocks Why you should be bullish on Bitcoin right now Learn our Top Themes to buy now How to trade the world’s most important trend Credit: KanawatTH The world’s most important trend just got a big boost from Nvidia (NVDA). Last night, the world’s largest semiconductor firm reported extraordinary second-quarter results that came in well ahead of estimates. Nvidia
     

How to trade the world’s most important trend

27 August 2026 at 12:00

Today’s issue in preview:

  • How to trade the world’s most important trend

  • This chart shows why you should be bullish and buy stocks

  • Why you should be bullish on Bitcoin right now

  • Learn our Top Themes to buy now


How to trade the world’s most important trend

Image

Credit: KanawatTH

The world’s most important trend just got a big boost from Nvidia (NVDA).

Last night, the world’s largest semiconductor firm reported extraordinary second-quarter results that came in well ahead of estimates.

Nvidia CFO Colette Kress said that the company expects revenue growth of 70% for fiscal 2028, which goes from February 2027 to January 2028. CEO Jensen Huang said demand “is much greater than 70%,” but Nvidia is constrained on how much product it can supply.

In response to this good news, Nvidia shares climbed 7.5% during the morning trading session. It also sent the VanEck Semiconductor ETF (SMH) up 2.17%.

Over the past month, we have published a special series of research notes analyzing the semiconductor trend, a key part of “the world’s most important trade.”

The status of this critical tech sector has become one of the great sagas of the business and investment world… a source of intense disagreement among industry bulls and bears.

The semiconductor industry has always been a critical part of our high-tech economy. Semiconductors are the “tiny engines” that power our computers. However, the proliferation of AI has turbocharged the industry’s revenues, stock prices, and importance to the global economy. It has also made industry leader Nvidia a $5+ trillion colossus. The stock is up more than 1,300% since Jan. 1, 2023.

In June 2025, semiconductor stocks broke out of a sideways consolidation pattern and began a rally for the ages. During this rally, the world’s largest semiconductor ETF – SMH – gained 147% in just under a year.

Individual semiconductor leaders AMD (AMD), Marvell Technology (MRVL), and Lattice Semiconductor (LSCC) gained more than 200% during that time. Stock gains of 25% in a month became commonplace.

When a sector gains 50% in a year, that’s considered incredible. What semis returned was “triple incredible.”

Avid Money & Megatrends readers know what drove those giant returns. Given AI’s enormous promise, large tech firms such as Alphabet (GOOG), Amazon (AMZN), and Microsoft (MSFT) have invested over $1 trillion in AI infrastructure. They are on pace to invest over $700 billion this year alone and more than $3 trillion after that.

Both the scale and the velocity of this investment boom are unprecedented. It is the largest collective investment effort in history.

A lot of this money was used to purchase semiconductors. Semiconductor industry revenue totaled $793 billion in 2025, an increase of 21% year-over-year, according to Gartner, Inc.

Big Tech’s historic investment boom has made the entire “AI infrastructure” trend responsible for a large share of America’s GDP growth and stock market returns over the past two years. It has also drawn the skeptical scrutiny of many widely followed investment analysts who claim the trend is a bubble… one that will soon explode and cause tremendous damage to stock prices and the global economy.

I believe the AI infrastructure trend has years to run. I believe the world’s smartest, most connected tech CEOs who have the greatest access to information on AI advancement and return on AI infrastructure spend like Jensen Huang, Satya Nadella (Microsoft) and Andy Jassy (Amazon) just might know more about this business than the bearish armchair AI quarterbacks know.

As much press as AI gets, let’s remember that less than 1% of the global population pays for top-tier AI programs. And I estimate less than 20% of large companies believe AI has made a meaningful impact on their businesses. It’s probably closer to less than 10%.

This revolutionary technology hasn’t yet proliferated, achieved mass adoption, or had mass impact.

Regular readers know I care a lot more about what the market thinks of any stock, trend or theme than what any one person thinks of it, including me. You can be bullish or bearish on a trend all you like, but if that trend is moving strongly against you, then your idea isn’t worth a hell of a lot in my book.

With this in mind, let’s look at industry giant Nvidia’s effect on the state of semis. The semiconductor sector is our preferred way to track and analyze the hugely consequential AI infrastructure megatrend.

Given its AI drivers and big returns, it’s no wonder semis became the world’s “hottest trade” this summer. And when any theme becomes the world’s hottest trade, it becomes a leading candidate to experience a significant correction or something worse.

That’s just how the stock market works. When a bull market grows very popular and attracts a lot of speculation, it likes to “buck off” market participants with a sharp correction or worse.

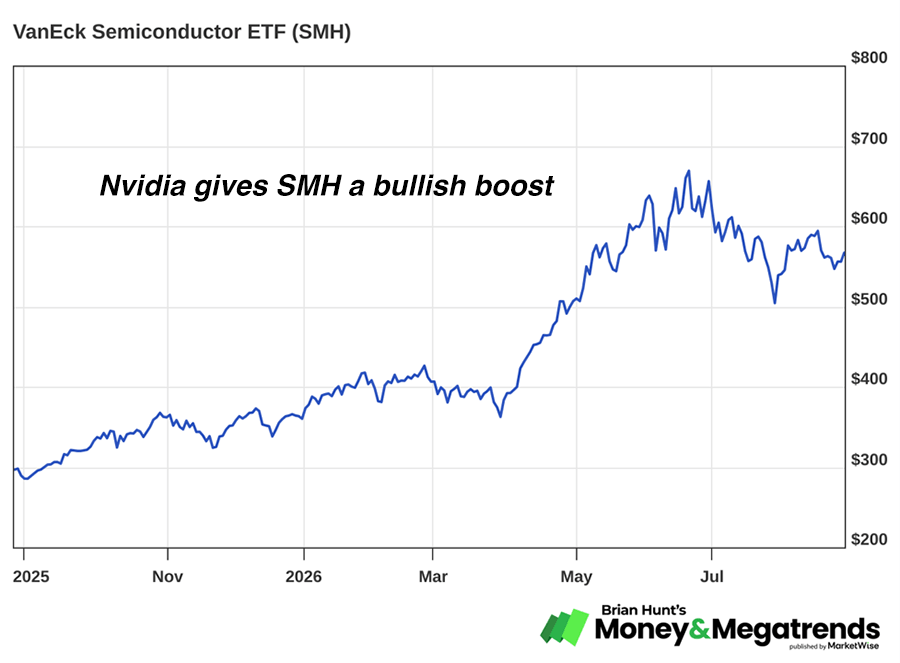
That’s what has happened to the semiconductor trade this summer. After soaring from June 2025 to June 2026, SMH declined 24%. Some individual semi names declined by more than 35%.

As you can see in the two-year chart below, the SMH share price declined from the mid-$600s to the mid-$500s. Since reaching a low in late July, SMH has traded up and down, failing to establish a meaningful trend. In other words, “becalmed” as described above.

In my July 20 health analysis of SMH, I stated that if long-term AI bulls are proven right by the market, SMH will likely “digest” its summer losses by trading in a sideways consolidation pattern for 3-6 months… and then recover to trade back to the mid-$600 area and beyond.

If the AI bears are right, SMH won’t see that mid-$600-per-share level for years… and we are much better off focusing on other trends.

As you can see in the chart below, SMH is getting a boost today… but it is still trading in a directionless sideways consolidation pattern. If the current rally can take SMH back to the $620 level, we can say this critical trend is enjoying restored health. We will keep you updated.

Image

Recommended Link:

Tonight, Louis Navellier Closes the Doors

Ad Image

Until midnight, you can claim a full year of Louis Navellier’s brand-new research… the project that ended his 47-year run as Chief Quant Analyst… at 60% off. It’s a totally new approach to the AI boom, built with Eric Fry and Luke Lango – one the team believes could realistically double your entire portfolio in the years ahead. Doors close at midnight. Until then, click here for the full details.

This chart shows why you should be bullish and buy stocks

Image

Credit: Art Wager

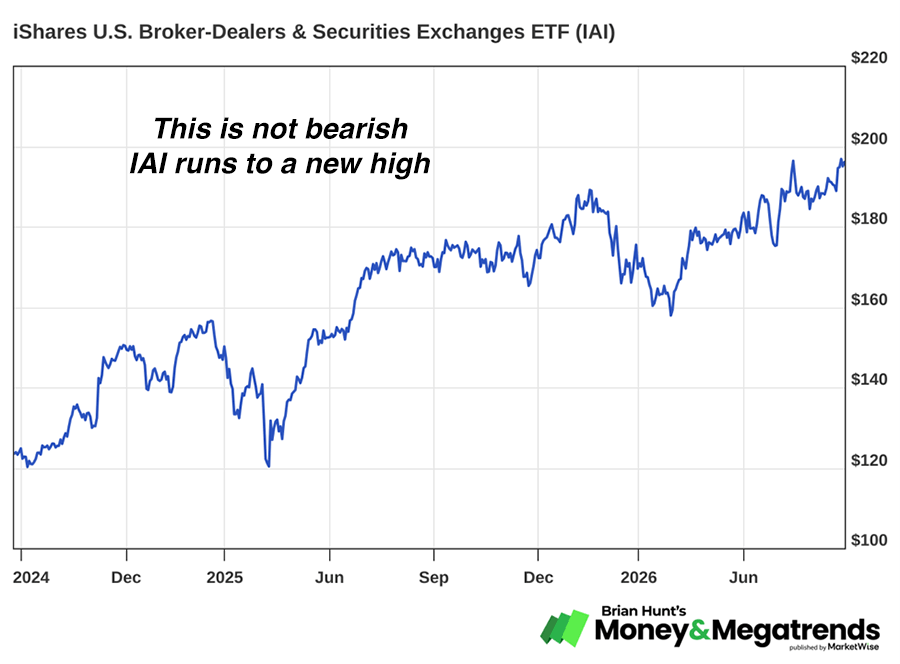
If you’re looking for reasons to be optimistic on the U.S. economy and U.S. stocks, look no further: The iShares U.S. Broker-Dealer & Securities Exchanges ETF (IAI) recently registered a new all-time high.

This is a bullish signal for America… and for your 401(k).

Since the current bull market began in 2023, a whole doom-and-gloom industry has been built on bearish stock and recession forecasts. Anyone who listened to the “prophets of the apocalypse” and avoided stocks has missed a historic wave of wealth creation. The bears have sounded clever, but they’ve been very, very wrong.

Sure, the U.S. economy has imbalances and problems. But it also has tremendous forces working in favor of prosperity. Energy independence. Food independence. The world’s most dynamic system for creating and funding new businesses. The world’s largest and most innovative technology industry. A system that rewards hard work, risk-taking, and value creation.

These “forces for good” are manifesting themselves in IAI’s all-time highs.

IAI is a unique ETF focused on companies in the business of money flows… companies that function as the business and investment world’s “circulatory system.”

The fund includes investment banks, securities exchanges, stock brokerages, financial index providers, and credit rating agencies.

Major holdings include diversified giant Goldman Sachs (GS), fellow giant Morgan Stanley (MS), brokerage firm Charles Schwab (SCHW), brokerage firm Robinhood (HOOD), credit rating agency Moody’s (MCO), and financial exchange giant CME Group (CME, formerly Chicago Mercantile Exchange).

These firms provide the grease and gears that make the world’s financial markets engine go. They eventually get a substantial “cut” from all kinds of financial activities, such as IPOs, 401(k) management, option trades, stock index administration, ETF management, stock purchases, commodity transactions, wealth management, debt issuance, and credit ratings.

Their fortunes rise and fall with the health of global financial markets. The new highs reached by their ETF are a bullish economic signal. The fund has returned a stellar 57% over the past two years.

Over the past 10 months, I’ve written over a dozen research notes analyzing the soaring share prices of highly economically sensitive industry groups, including trucking stocks, regional banks, manufacturing stocks, diesel engine makers, steelmakers, shopping mall operators, and hotel chains.

At the end of each note, I pointed to their soaring stock prices and told readers that the U.S. economy is doing much better than most people think.

This exceptional price strength in key components of America’s economic machine means the economy is doing much better than the news you hear from the mainstream media.

We can add IAI’s new highs to this long list of positive market trends. The business of money, investment, and corporate finance is booming. Manage your financial affairs accordingly!

Image


Why you should be bullish on Bitcoin right now

Image

Credit: Vertigo3d

Minute by minute… day by day… things keep getting a little better for Bitcoin bulls.

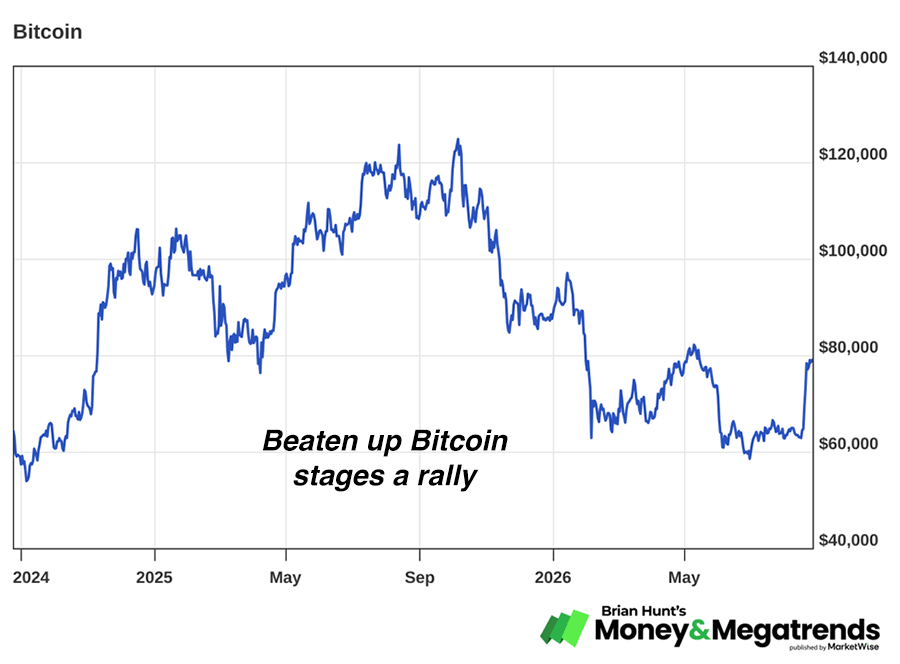
This week, the beaten-up cryptocurrency rallied to reach $80,000 – its highest price in three months. This action gives me confidence in saying that our bullish March 13 note was well-timed.

After reaching an all-time high of around $125,000 last October, Bitcoin entered a brutal bear market, declining by about 48% to the mid-$60,000 range.

Crypto specialists attributed this decline to the U.S. government withdrawing liquidity from financial markets, as well as to gold and AI trades drawing money flows that could have been directed toward Bitcoin.

Most long-term Bitcoin believers see it as a “store of value” that should maintain its purchasing power like gold and beachfront homes do. It should be a digital form of “hard money.” Sounds great.

However, from October 2025 to February 2026, Bitcoin traded more like a failing technology company than anything you’d call strong and stable.

In March, Bitcoin’s trading behavior underwent a significant change. It formed a bottom and gained 9.5% in one month, while technology stocks dropped and gold gained just 3.2%. Importantly, Bitcoin outperformed stocks and gold as Operation Epic Fury created tremendous market volatility and hammered many sectors of the stock market. It was a “port in the storm.”

Importantly, Bitcoin recently rallied above its long-term 200-day moving average. This is a good sign of an improving health trend. Remember what we say about the 200-day moving average around here: Securities below their 200-day moving average are on the wrong side of the tracks. It’s the ugly part of town. All the really bad things happen below the 200-day moving average. Bitcoin just broke about it.

So, after a year of disappointing believers, has Bitcoin regained its place as a “store of value”? Is it ready to be a “port in the storm” and a stabilizing component of serious portfolios? I hope so. The world is a better place when Bitcoin is rising, and we have not one but two forms of hard money to own. Plus, I like it when the “crypto bros” get chirpy on X and antagonize the skeptics.

Count me bullish on Bitcoin and its new rally.

Image


Market Notes

  • Our recommendation to invest in cybersecurity is paying off nicely. Okta (OKTA) just reached a new yearly high, and Palo Alto Networks (PANW) is up 10% today. PANW is now +150% since our March recommendation.

  • Our recommendation to invest in the genomics megatrend continues to pay off. Cancer genomics leader NeoGenomics (NEO) just hit a new high. It’s now up 166% in the last month. Genomics analytics giant Illumina (ILMN) reached a new one-year high.

  • Global and community banks are showing strength. Japanese investment banking giant Nomura Holdings (NMR) and community lender Private Bancorp of America (PBAM) reached new highs today.

  • Our Oct. 2, 2025, recommendation to own the natural gas theme is doing very well. The US Natural Gas Fund (UNG) just hit a new high, as individual names like Range Resources (RRC) have gained around 7.5% this month.

Regards,

Brian Hunt signature

Brian Hunt signature

Brian Hunt
Editor, Money & Megatrends


An urgent message from our colleagues:

Wall Street veteran goes ALL in on Bank of Elon

Image

A 20-year Wall Street veteran – who worked at a $10 billion hedge fund – is putting ALL his money in Elon Musk’s new bank. He says he can see the writing on the wall for traditional banks. And he’s not the only one.

See if you should join him here (not just for the 6% yield).

The post How to trade the world’s most important trend appeared first on MarketWise.

  • ✇Market Wise
  • Nvidia’s Blockbuster Earnings: Here’s the Biggest Risk the AI Chipmaker Faces, Even as Sales Soar James Royal
    Key Points Nvidia reported eye-popping second-quarter results, with sales surging 106% to $96.2 billion and operating earnings climbing 124% to $63.7 billion. Despite the standout performance, Nvidia is losing some key levers for boosting profitability, including its ability to rapidly expand margins as it has in years past. Nvidia’s current valuation depends on the AI build-out continuing to grow, even as more companies are forced to borrow heavily to keep buying its chips.
     

Nvidia’s Blockbuster Earnings: Here’s the Biggest Risk the AI Chipmaker Faces, Even as Sales Soar

27 August 2026 at 10:41

Key Points

  • Nvidia reported eye-popping second-quarter results, with sales surging 106% to $96.2 billion and operating earnings climbing 124% to $63.7 billion.
  • Despite the standout performance, Nvidia is losing some key levers for boosting profitability, including its ability to rapidly expand margins as it has in years past.
  • Nvidia’s current valuation depends on the AI build-out continuing to grow, even as more companies are forced to borrow heavily to keep buying its chips.

Nvidia (NVDA) reported strong earnings on Wednesday. In its latest quarter, the artificial intelligence (“AI”) chipmaker grew sales an astonishing 106% year over year to $96.2 billion, while operating income surged 124% to $63.7 billion.

Nvidia puts up numbers each quarter that seem impossible to fathom. And the fact that a $5 trillion company can grow this much is something special.

While any company would love numbers like that, investors are always looking ahead, and some believe things can’t get any rosier for Nvidia than what they’re seeing now. That’s a big reason why we’ve seen the stock plateau in recent months.

The upshot is that Nvidia is losing some levers that have kept its massive profit machine growing at the pace it has sustained over the past few years. At the same time, its willingness to finance massive projects is swelling its own balance sheet, even as hyperscalers are borrowing billions to buy its chips – both of which call into question the ongoing sustainability of Nvidia’s tremendous sales growth.

For example, even as sales have exploded higher, Nvidia’s gross margin has seemed to top out.

Period2022202320242025Q1 2026Q2 2026
Sales$27 billion$60.9 billion$130.5 billion$215.9 billion$81.6 billion$96.2 billion
Gross margin56.9%72.7%75%71.1%74.9%75%
Operating margin15.7%54.1%62.4%60.4%65.6%66.2%
Source: Macrotrends and Nvidia’s 2026 releases

Gross margin appears stuck at 75% and seemingly unable to expand above that level. So, future profit growth will rely primarily on sales growth, without the added lift of gross margin expansion.

Nvidia has already warned that surging memory costs are hitting margins, likely pushing them to 71% to 72% in the fourth quarter. Next year, however, they should bounce back to margins of 72% to 73%. This sensitivity to change shows how tough it will be for Nvidia to exceed its historic 75% level.

It’s a similar – but slightly different – situation with operating margins, which continue to grow from already phenomenal levels, albeit more slowly than before. If sales keep growing and Nvidia keeps a hold on costs, it will likely still be able to wring a few more points of operating margin. But the days of 8.1 year-over-year percentage-point gains Nvidia saw in 2024 are gone.

Nvidia’s bleeding-edge products keep it in the lead for now. Still, everyone wants a piece of these fat margins, from established players such as Broadcom (AVGO) to upstarts such as Cerebras Systems (CBRS), which makes wafer-scale chips for AI data centers.

None of this suggests that the near future won’t get better for Nvidia, but the ability for it to get much better has been diminished, since margins can’t expand at yesteryear’s levels anymore. But this is only one part of the concerns suggesting that Nvidia must use new levers, such as more aggressive financing, to keep its sales growth on track.

(Looking for a step-by-step plan to help you use AI in your own investing? Here’s how the N.E.W. System works.)

Nvidia Is Aggressively Financing the AI Boom, Which Comes With Higher Risks

Borrowing behind the AI build-out has surged, especially in 2026. Hyperscalers such as Amazon (AMZN), Microsoft (MSFT), Alphabet (GOOGL), and Meta Platforms (META) have spent nearly all their 2026 cash flow on capital expenditures, most of it on the AI build-out.

To keep that build-out on pace, these hyperscalers have each started borrowing tens of billions of dollars in the past year. With hyperscalers’ AI spending projected to top $1 trillion in 2027 – well beyond their estimated cash flow – they’ll need to borrow even more money.

While that increased financing means the spending spree for Nvidia’s chips won’t keep growing forever, the chipmaker has begun offering more short-term financing on its own balance sheet.

That is, Nvidia is offering more generous payment terms to larger customers, giving these more important clients up to a year to pay. CFO Colette Kress said about 25% of Nvidia’s 2027 sales could be to AI labs (such as OpenAI) where Nvidia is using its own balance sheet.

You can see this change in a metric called accounts receivable, which has soared in recent years, as Nvidia finances more sales, typically for short periods. The average is around 60 days, or about two months. While the figure dipped in the first quarter (not necessarily a bad thing), it rebounded hard in the second quarter, though only to its historical levels.

Period2022202320242025Q1 2026Q2 2026
Receivables$3.8 billion$10 billion$23.1 billion$38.5 billion$40.7 billion$63.1 billion
Sales$27 billion$60.9 billion$130.5 billion$215.9 billion$81.6 billion$96.2 billion
Days sales outstanding51.859.964.56544.959.9
Source: Macrotrends and Nvidia’s 2026 releases

To judge these receivables, analysts look at days sales outstanding (“DSO”), which is the ratio of accounts receivable to a quarter’s average daily sales. DSO shows whether a company may be expanding credit to less worthy customers to keep its sales growth continuing.

This trend isn’t worrisome yet, but it’s worth watching as Nvidia expands its financing, especially to clients with major financing issues such as OpenAI, which is hemorrhaging billions in cash each quarter. Of course, it’s not just OpenAI that could hurt Nvidia, but even established players that rely on OpenAI remaining solvent to continue moving billions in AI spending through the system.

After such a consistent trend for years, a sudden rise in DSO may offer investors an early read on how the business is going. Nvidia is already warning investors that the number should rise – and it’s a sign that it must move more of this financing to its own balance sheet to keep sales rising. If credit problems arise, they will likely appear in rising days sales outstanding figures.

That puts greater credit risk on Nvidia, drawing it even closer to less well-financed players.

More broadly, you can see Nvidia rushing to keep its sales growth on track, as it becomes the “central bank of AI.” It has lined up a $250 billion backstop for OpenAI to construct a massive data center as well as a $350 billion financing arrangement for the facility’s chips.

Nvidia also announced an incomplete $500 billion deal with major investors before it had been finalized. In the end, it’s less a deal than a memorandum of understanding – “a deal to do a deal” – despite the breathless media headlines making it seem like the terms were in place.

Despite this quarter’s excellent numbers, Nvidia is pushing hard to line up financing for its customers and keep all its plates spinning. With each passing quarter, the growth will become harder to sustain, so watch for a rise in DSO as an early warning sign of trouble.

Nvidia’s Stock Looks Undervalued, But Is It Really?

On the surface, Nvidia looks cheap for a company growing at such a brisk pace. In May, various analysts raised stock price targets based on Nvidia’s rising earnings for 2026 and 2027, due to surging AI investment.

For example, Wells Fargo raised its price target from $265 per share to $315 on earnings estimates of $8.45 per share this year and $11.95 per share for calendar year 2027. This level of explosive growth implies a price of less than 19 times next year’s earnings at a share price around $220.

This price-to-earnings (P/E) ratio is well below the stock’s 32 times earnings over the past three years, says Wells Fargo.

In absolute terms, this forward P/E ratio looks quite reasonable for such high growth. But it assumes that growth will continue, even as Nvidia desperately works to provide financing for its clients. Some of Nvidia’s levers for growing profits are becoming less powerful, too.

So this assumption of growth will look fine until one day it suddenly won’t.

It’s less a question of “if” than “when” the Nvidia juggernaut can no longer sustain the high expectations it’s setting now.

Arguably, the world’s most-watched company is trading for what looks like a value. If you believe in the wisdom of the market, you want to be quite sure why it’s putting the company – and many high-growth AI plays – in the bargain bin. They may not be as undervalued as they appear.

Regards,

James Royal, PhD

Editor’s Note: Whitney Tilson — the hedge fund manager CNBC called “The Prophet” — says America has reached its “Ripping Point.” The old financial order is being torn apart, and he believes most investors have no idea what’s coming in the next six months. He’s named the stocks he thinks will be destroyed in the chaos — and the ones he believes will soar. Watch his free presentation while it’s still available.

The post Nvidia’s Blockbuster Earnings: Here’s the Biggest Risk the AI Chipmaker Faces, Even as Sales Soar appeared first on MarketWise.

  • ✇Market Wise
  • CoreWeave Stock: The $2.6 Billion Debt Signal the AI Bubble Is Ignoring Jonathan Rose
    A $2.6 billion loan just told you more about the AI buildout than any earnings call. The stock already recovered and forgot. The loan document remembers — and it’s the most honest signal in the whole trade. Twenty years on a trading desk teaches you where to look when you want the truth about a trade. Twenty years on a trading desk teaches you where to look when you want the truth about a trade. You can’t use stock prices, they lie all the time. They gap on emotion, they get pinned by o
     

CoreWeave Stock: The $2.6 Billion Debt Signal the AI Bubble Is Ignoring

27 August 2026 at 07:04

A $2.6 billion loan just told you more about the AI buildout than any earnings call. The stock already recovered and forgot. The loan document remembers — and it’s the most honest signal in the whole trade.

Twenty years on a trading desk teaches you where to look when you want the truth about a trade.

Twenty years on a trading desk teaches you where to look when you want the truth about a trade.

You can’t use stock prices, they lie all the time. They gap on emotion, they get pinned by options dealers, they run on narrative long after the story has changed.

That’s especially true when you’re evaluating AI infrastructure stocks, where billion-dollar financing decisions often reveal more than earnings calls or analyst price targets ever will.

If you want to know quickly whether a company is actually in trouble, you watch what it costs that company to borrow money.

The lenders behind the money have done the work. They’ve read the contracts. They’ve stress-tested the cash flows. And when they suddenly demand more interest, tighter terms, and a lockbox on the revenue before they’ll hand over a dollar — that’s the smart money repricing risk in real time.

This is exactly what’s happening with one stock at the center of the next AI wave — CoreWeave Inc. (CRWV).

AI Infrastructure Stocks’ Hidden Debt Bomb

In mid-July, CoreWeave — the “neocloud” that rents out Nvidia GPUs to AI companies — went to the leveraged-loan market to raise $2.6 billion.

At first, the loan looked routine.

The structure was a delayed-draw term loan, its fifth-and-a-half such facility, nicknamed DDTL 5.5. The proceeds were earmarked to buy more GPUs and infrastructure to serve a specific set of customer contracts.

According to loan-market reporting from LSEG and Octus, the deal launched on July 16 at a spread of SOFR plus 425 to 450 basis points, offered at 99 cents on the dollar. Standard-issue for this borrower.

Then it stalled.

The lenders investing in the project weren’t convinced. And to get the deal across the line, CoreWeave had to rewrite the terms in the buyers’ favor:

  • CRWV agreed to pay a much higher interest rate, making the loan significantly more expensive. The spread widened roughly 100 basis points to SOFR + 550, and the loan was discounted to around 96 cents — a four-point cut. The Financial Times pegged the all-in yield at roughly 9%. That’s a junk-grade cost of capital for a company that, months earlier, had raised GPU-backed money at investment-grade rates.
  • The lenders demanded stronger protection. They imposed a cash lockbox — meaning the cash coming in from customer contracts has to go to paying down the debt first, before CoreWeave can touch it — plus a 1.35x debt-service-coverage covenant and full amortization, per Fitch and loan-market coverage. Translation: the lenders wanted a hand on the cash register.

Only after making those concessions was CoreWeave able to secure the financing.  When the deal finally closed around August 10, the company described it as “meaningfully oversubscribed,” meaning more investors ultimately wanted to participate than the company needed.

At first glance, that sounds like a sign of overwhelming confidence, but remember when that demand appeared.

Investors only lined up after CoreWeave caved to the lenders’ demands. In other words, they’re there for the deal,

This was echoed by the independent credit-rating agencies. Fitch rated the loan BB+ and Moody’s rated it Ba2 — both below investment grade.

The deal did get done. But the market forced CoreWeave to pay up, pledge its cash flows, and accept a leash — before it would fund the AI buildout everyone insists is unstoppable.

The major takeaway here?

When a trade is truly bulletproof, the financing is supposed to get cheaper. But this one got more expensive, more restrictive, and harder to place, all at once.

The Stock Already Forgot. The Loan Remembers.

Here’s the part that makes this worth your attention right now.

In late July, fear peaked. The cost of insuring CoreWeave’s debt against default — its credit default swap, or CDS — blew out. Per Bloomberg data cited across market coverage, CoreWeave’s CDS topped roughly 855 basis points, a level that implied around a 50% probability of default within five years on a standard pricing model. The stock bottomed near $60.

Then the mood flipped. The loan cleared. On August 12, CoreWeave reported second-quarter revenue up more than 200% year-over-year, with a backlog it pegged at roughly $104 billion.

The stock ripped — nearly doubling off the lows to around $117 by mid-August before settling back into the high $80s.

The sell-side climbed aboard: Truist moved to Buy with a $165 target, Goldman lifted its target to $139, and Oppenheimer kept an Outperform and a $150 target, arguing AI demand runs about four times available capacity.

It only took the equity crowd about three weeks to get its optimism back. Understandable. But notice what didn’t reverse: CoreWeave still had to accept a 9% all-in cost, a cash lockbox, a maintenance covenant, and full amortization to get that money.

Those terms are baked into a signed credit agreement. They don’t un-widen because the stock bounced. The bond market did its stress test in public, and the price of that test is now a permanent line item in their budget until it’s paid in full.

This is the oldest lesson on the desk. Think of it like this…

The stock market is a voting machine — it forgot the scare in three weeks. The credit market is a weighing machine — it wrote the risk into the contract and moved on.

When those two machines disagree this much, I’ve learned which one to trust.

The Three Key Tells Buried Inside the Deal

Pull the DDTL 5.5 apart and three specific risks explain why the lenders got nervous. Each one is a flashing light that’s still on.

Tell #1: The Durations Don’t Match.

CoreWeave’s problem is the oldest one in finance — borrowing long and getting paid short. This loan runs about five years. But the customer contracts backing it average only about three. And the underlying data-center leases CoreWeave signs with its landlords can run up to 15 years.

So CoreWeave commits to 15-year obligations, funds them with a five-year debt, and covers it with three-year revenue. If those customer contracts don’t renew, the bills keep coming with no guaranteed income behind them.

Fitch flagged exactly this. Visibility gets murky beyond the current contracted window, when the company leans on renewals and re-leasing to sustain growth. If that pattern rings a bell, it should. It’s the same asset-liability mismatch that took down WeWork — long leases, short revenue, and a growth story papering over the gap.

Tell #2: The Customers are Dangerously Concentrated.

The Financial Times reported that the single largest counterparty behind this loan is Anthropic, at roughly 40%, followed by the quant trading firm Jane Street at about 35%, with Midjourney, Hudson River Trading, and Anysphere (the maker of Cursor) making up the remainder. Fitch separately noted that CoreWeave drew about 65% of its first-quarter 2026 revenue from just its top two customers.

Two things stand out. First, that is enormous concentration — a handful of contracts carrying the whole structure. Second, and more pointedly: Anthropic, the 40% anchor, is a privately held company with no public credit rating.

That’s not a knock on Anthropic — it’s one of the best-funded labs in AI, and in August it was being called the hottest upstart in the field. It’s a statement about what the lenders can actually underwrite.

You cannot price the credit risk of a counterparty you cannot rate.

When 40% of your collateral rests on an unrated private company and another 35% on a proprietary trading firm, the margin for error is thin under the best of circumstances.

There’s a footnote worth watching. As bond analyst Rod Dubitsky flagged, Fitch upgraded Jane Street — CoreWeave’s #2 counterparty — right in the middle of the period when this struggling loan was being marketed, citing factors that had been in place for years. Draw your own conclusions, but the timing feels suspicious.

Tell #3: The Lockbox is the Lenders Telling You What They Think.

You don’t demand a cash lockbox from a borrower you trust. You demand it when you want to make sure you get paid before anything else can go wrong. The concession CoreWeave had to grant is itself the verdict.

Not All AI Infrastructure Stocks Are Built the Same

While CoreWeave may be the loudest canary in the coal mine among the AI infrastructure stocks, they’re far from being alone.

The entire AI buildout runs on borrowed money and depreciating collateral.

Neoclouds like CoreWeave and Nebius fund their GPU purchases with debt secured against the chips themselves  —  Nvidia hardware that’s valuable today but could be a generation behind tomorrow.

CoreWeave’s own guidance calls for $31–35 billion of capital spending in 2026 against roughly $6.2 billion of trailing-twelve-month revenue.

Its first-quarter interest expense doubled to $536 million, and it has burned free cash flow every year since 2022. Revenue is expanding, yes — but so is the spending required to produce it. That treadmill only works as long as the cheap money hose keeps spitting out cash.

There’s a circularity here that should make you tilt your head: Nvidia sells the chips, is a major shareholder in CoreWeave, and is part of the capital ecosystem funding the customers who buy those chips.

When the same company is supplier, shareholder, and financier, “demand” gets harder to read at face value.

 That’s why “AI infrastructure” is too broad to be a useful investment category. The companies may be building toward similar goals, but they’re operating under very different financial constraints. The way I see it, the easiest way to think about them is to divide them into two groups:

The self-funders. Amazon, Alphabet, Microsoft, and Meta are pouring hundreds of billions into the buildout too — but largely out of operating cash flow from businesses that already mint money.

Their existing profits subsidize the unprofitable early years of AI. If financing gets expensive, they can shrug.

The debt-funders. CoreWeave, Nebius, Oracle’s cloud arm, and the leveraged neocloud complex finance the same buildout with debt, leases, and project loans against short contracts and depreciating chips.

For this bucket, the cost of money is the business model. When spreads widen, their math breaks first. This isn’t limited to the neoclouds: Oracle — the largest non-financial borrower in the Bloomberg U.S. high-grade index — saw its own CDS climb above 215 basis points this year, up from about 145 at the end of last year, with its long bonds yielding close to 7.8%. Apollo’s chief economist Torsten Slok put a name on the danger: at high enough all-in yields, the AI capex cycle starts to self-throttle not because demand changes, but because financing becomes too expensive.

And the hyperscalers just made the debt-funders’ problem worse.

In mid-July, Meta announced “Meta Compute,” a service to sell bare GPU capacity to third parties — the exact business the neoclouds are built on. When your biggest potential customer becomes your competitor, the “customer concentration” and “insourcing” risks are no longer theoretical.

I call it my AI Destruction List. Big media loves to oversimplify the problem. They say “AI is a bubble” — but that’s too lazy to be useful for anyone, and it’s impossible to time.

The more precise version: the leveraged, debt-funded layer of the AI trade cracks first, and it cracks in the credit market before it cracks in the stock.

Is There Any Bull Case for CoreWeave?

Now that we’ve covered the problems, allow me a moment to argue against myself. After all, a one-sided case is a weak case — and I want you thinking, not panicking.

The bulls have real, current points. The loan did clear, oversubscribed at the wider terms — the demand exists, just at a higher price.

Many of CoreWeave’s contracts are “take-or-pay,” meaning customers owe the money whether or not they use the capacity. That ~$104 billion backlog is enormous (bear in mind it blends remaining performance obligations with other committed amounts, so it’s a scale indicator, not a bank balance).

The company is actively working to diversify the concentration I just flagged — in August it signed a fresh multi-year deal with Hudson River Trading and pushed into sticky government work through a CoreWeave Federal partnership with Leidos.

Its marquee counterparties — Anthropic, Meta, OpenAI, Jane Street — are real, growing, well-capitalized names.

The insider selling that made headlines was executed under pre-arranged 10b5-1 plans and left executives with large stakes.

And most of Wall Street is bullish, with price targets from $139 to $165 against a stock in the high $80s. A CDS spread is a probability, not a verdict — and the one that screamed in July has since calmed as the stock recovered.

Both readings are defensible from the same set of facts depending on which details you choose to focus.

The honest position isn’t “CoreWeave is going to zero.” It’s that the cost of financing the AI buildout went up in a visible, measurable, contractually permanent way — and the market charged the most leveraged players the highest prices.

What is critical to understand before committing your capital to this trade is that ignoring that risk because the stock bounced is exactly the mistake retail makes at every top.

Forewarned is forearmed.

What the Options Say About CoreWeave

People always want the trade. But before we take the trade, we need to know the range of what to expect — and on a name like this, the range tells us the story.

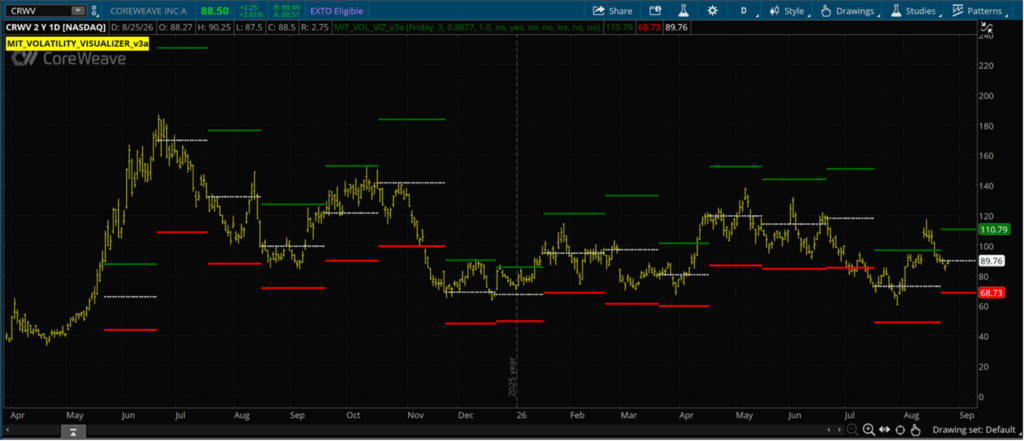
Every day I run a tool I built called the Volatility Visualizer, or the Vol Viz for short. This program plots the expected-move band the options market is pricing in for where a stock could realistically trade over a given window.

To be clear, this isn’t an arbitrary line I drew on a chart. This is hard data, pulled straight out of live options prices — the market’s own, dollar-weighted forecast of how far this thing can move.

Coreweave chart

Here’s what it’s showing on CoreWeave, with the stock around $88.50: an expected-move band running from roughly $69 on the downside to $111 on the upside — a range more than 40 points wide, better than 20% in either direction.

Sit with that. The options market is pricing a swing of more than a fifth of the company’s value, up or down, on a business worth tens of billions of dollars.

That’s an unusually wide range of expected outcomes. And it echoes the same warning coming from the credit market: investors are demanding a much bigger margin for uncertainty.

The lenders demanded a cash lockbox and 9% money because they couldn’t pin down the risk. The options market is pricing a 40-point range for the same reason.

Two completely different corners of Wall Street — credit and volatility — look at CoreWeave and reach one identical verdict: nobody knows where this settles and they’re actively worried about where it might end.

Why the Expected Move Matters More Than Any Price Target

A sell-side analyst stamps a $165 target on the stock and a headline is born — but that’s one person’s guess about direction.

The expected move is the whole market’s consensus about magnitude, and it comes with probabilities attached. Roughly speaking, the market is pricing about a two-in-three chance the stock finishes inside that ~$69–$111 band over the window.

That single fact should reframe everything you’re looking at. CRWV ripping toward $110 next month? Still “inside expected” — not a breakout, not a miracle, just the top of a range the market already told you about. A decisive break below $69 or above $111 is the only thing that would count as the market being genuinely surprised.

That is how you keep your head in a stock that moves 15% before lunch. You stop flinching at every candle and start asking one question: is this move inside the expected range, or did something just break the market makers’ models?

Because the day CoreWeave slices through the low end of that band on heavy volume is the day the credit-market alarm bells stop being silent.

Five Signals I’m Watching Next

You don’t need to track every loan. Watch these:

The 10-year Treasury. With the long end elevated, the cost of all this debt is set by the bond market. Higher-for-longer is the neocloud’s enemy.

The next neocloud financing. The tell isn’t whether it gets done — it’s the spread and the structure. Wider pricing and more lockboxes mean the squeeze is tightening. Cheaper, cleaner deals mean the fear is fading.

CoreWeave and Oracle CDS. The real-time thermometer. Staying wide is the warning; the more it compresses, the smoother sailing there is ahead.

Contract renewals. The duration mismatch is critical. The first time a big three-year contract comes up and doesn’t renew at full value, the mismatch problems stop being theoretical.

Hyperscaler insourcing. Every “Meta Compute” — every hyperscaler that builds instead of rents — is a direct hit to the neocloud customer base.

The Bottom Line

The biggest mistake investors make with AI infrastructure stocks is assuming they’re all exposed to the same risks.

Financial talking heads love to go on about the AI trade as a contest of technology — whose model is smartest, whose chips are fastest. But at this scale, it’s a contest of capital allocation and financial endurance. The question is no longer whether AI demand is real in the short-term. It’s whether that demand converts to cash fast enough, and lasts long enough, to service the mountain of debt being stacked against depreciating hardware.

The stock market already voted twice — panic in July, euphoria in August. The credit market didn’t flip-flop. It wrote the risk into a contract and left it there: wider spreads, tighter terms, a cash lockbox, and a set of covenants that tell you exactly how the smartest lenders in the room see this. The stock forgot. The loan remembers.

The first crack in the AI trade won’t show up on a chart. It will be buried in the fine print of a loan document.

Always follow the money.

Editor’s Note: Forbes calls $1 billion fund manager Louis Navellier “the king of quants.” Today, he’s stepping forward to reveal why he’s investing $358 million of his own firm’s money in the next stage of Artificial Intelligence… a technological sea-change that could erase millions of jobs, solve humanity’s biggest mysteries, and spark a wave of moneymaking opportunities — both in and outside the stock market. Click here for the details… 


I break down the day’s biggest market story every morning on Masters in Trading Live, 11 AM ET. I follow the top stories of the day and show you how the smart money is really positioned — no geometry, no chart-drawing, just evidence of where the money is moving. Join me each morning, drop a “Good Morning” in the chat, and let’s read the tape together. Jonathan Rose is a former CBOE market maker and the founder of Masters in Trading at InvestorPlace. I hosts Masters in Trading Live every weekday at 11 AM ET. Follow me on X at @JRoseTrades

The post CoreWeave Stock: The $2.6 Billion Debt Signal the AI Bubble Is Ignoring appeared first on MarketWise.

  • ✇Market Wise
  • Bitcoin Miners: A Surprising Winner From the Growing AI Data-Center Backlash Eric Wade
    Key Points Bitcoin miners are becoming valuable players in AI infrastructure because their existing power, land, and cooling assets can be repurposed for lucrative data centers. AI’s surging electricity demand is creating a tailwind for some miners, while flat mining difficulty and higher bitcoin prices could further boost profitability. The AI data-center backlash creates both opportunity and risk: slower development could limit mining competition but also delay miners’ own
     

Bitcoin Miners: A Surprising Winner From the Growing AI Data-Center Backlash

26 August 2026 at 10:01

Key Points

  • Bitcoin miners are becoming valuable players in AI infrastructure because their existing power, land, and cooling assets can be repurposed for lucrative data centers.
  • AI’s surging electricity demand is creating a tailwind for some miners, while flat mining difficulty and higher bitcoin prices could further boost profitability.
  • The AI data-center backlash creates both opportunity and risk: slower development could limit mining competition but also delay miners’ own AI infrastructure projects.

It seems like just about everyone is mad about AI data centers right now.

They’re thought of as big, loud nuisances… and it’s hard to find people who actually want them where they live.

At the same time, we’re using artificial intelligence (“AI”) more than ever for searches, coding, writing, problem-solving, and even just chatting. So, demand for data centers is real.

Nonetheless, the AI data-center backlash we’re seeing has become big enough to matter to investors. Towns are pushing back over water, power bills, tax breaks, noise, diesel generators, and the simple reality that nobody wants a windowless server farm dropped into their neighborhood.

That’s a problem for the AI trade because Nvidia (NVDA) stock may be a proxy for AI growth, but chips still need to be installed in hardware which needs to be deployed into buildings, powered by transformers, and receive municipal permits before they become revenue. Nvidia is the top bellwether for AI, but it still relies on data centers for a majority of its chip sales.

It’s also creating a strange side effect in bitcoin mining…

See, while investors have been staring at Nvidia, the bitcoin mining network has been doing something odd.

Crypto-tracking site CoinWarz put bitcoin difficulty at 125.81 trillion today. About a year ago, on August 24, 2025, according to Hashrate Index, the difficulty was at 129.70 trillion… then an all-time high.

In plain English, the work required to mine a block today is roughly the same as it was last summer. That gives miners more time to make a return on their hardware investments without having to upgrade.

So thank you, AI data centers. And thank you to everyone saying they don’t want one in their neighborhood. It’s helping make certain miners a lot of money.

Today, we’ll look further at how the AI-infrastructure build-out and rising bitcoin prices are setting up a profitable scenario in the mining space.

Why Steady Mining Difficulty Is Favorable in a Bitcoin Rally

Bitcoin mining difficulty is the network’s thermostat.

Every two weeks, bitcoin adjusts how hard miners must work to keep blocks arriving about every 10 minutes. When more machines mine for the same reward, bitcoin difficulty rises. Fewer machines, or machines pointed somewhere else, means difficulty stabilizes or falls.

For a miner, that math is brutal and simple. Revenue comes from the bitcoin price, block rewards, and transaction fees. Costs come from power, machines, debt, and maintenance. If bitcoin jumps while difficulty stays flat, the same machines earn more dollars without facing the usual penalty of a harder network.

That’s exactly why the recent bitcoin rally matters. Bitcoin gained 23% in a week– its biggest move since last year’s sell-off – after Treasury-bond buybacks pushed long yields lower, the dollar weakened, and a short squeeze forced buyers back into the market. ETF inflows are the next test, because forced buying burns out quickly, while institutional flows can keep a rally alive.

If bitcoin holds even part of that move higher, miners get operating leverage when the selling price rises, and the production hurdle does not.

AI Pivots Are the New Way Miners Capitulate

In previous bitcoin cycles, miner capitulation looked familiar. The price fell, inefficient miners shut off, mining rigs hit the secondary market, and the network waited for difficulty to adjust down.

This cycle has a different escape hatch. Miners don’t have to disappear. Some have become AI-infrastructure companies.

That sounds like a branding trick until you remember what miners can offer to the AI space: power access, land, cooling, substations, operating teams, and a tolerance for absurd capital intensity. Those are the main things that data-center developers are fighting to secure.

CoinDesk reported in March that public miners had announced more than $70 billion in AI and high-performance-computing (“HPC”) contracts. S&P Global listed Iren, Riot Platforms, Core Scientific, Hive Digital Technologies, Cipher Digital, and TeraWulf among the miners shifting capacity away from pure bitcoin mining, with analysts expecting HPC and AI to drive much of their growth in 2026.

That matters because every megawatt chasing AI is a megawatt that’s not automatically chasing the next bitcoin block. While the machines and customers are different, the scarce input is the same: energized infrastructure.

The result is a softer version of miner capitulation. Instead of “we shut off because bitcoin mining stopped being profitable,” the message becomes “we found a better-paying customer for this power.”

AI Data-Center Backlash Cuts Both Ways

Now for the catch…

The same local revolt slowing the data-center land rush and helping bitcoin miners also threatens the miners trying to become AI landlords.

Governors and lawmakers are moving to force data centers to pay for their own electricity supply, limit water use, disclose more about operations, and win local support, according to the Associated Press.

Microsoft (MSFT) is already working to unwind multimillion-dollar tax breaks on several Atlanta data-center projects as the politics get hotter.

So, the trade is not “buy every miner with AI in the press release.” Please don’t do that. That’s how people end up owning a construction project with a bitcoin ticker.

Look for mining stocks that already control power, have credible tenants, and can survive construction delays while still making money mining bitcoin if their AI customer takes longer than promised to come online.

Global asset manager VanEck has already warned that miners chasing AI face a roughly $50 billion near-term funding gap and that only about a quarter of leased AI and HPC capacity has been delivered so far.

That means there’s still a long way to go.

What Investors Should Watch Next

Chips are no longer the bottleneck in the AI trade. Power is. Permits are. Local sentiment is. The boring parts are now in charge.

For bitcoin miners, that means three numbers are worth watching…

  • Bitcoin difficulty: If difficulty stays near last year’s level while bitcoin holds its rally, miner margins improve without any miracle.
  • ETF inflows: A short squeeze can light the match (and it really, really did last week), but sustained inflows tell you whether serious capital is returning to bitcoin. They’ve been positive since August 17, which is good, but previous rallies have run for as long as seven months, so time will tell.
  • AI data-center approvals: Every delayed hyperscale project makes energized power more valuable. Some miners will monetize that value through AI contracts. Others will benefit because competitors will stop adding hash rate as aggressively.

That’s one thing many bitcoin investors are missing. While the AI data-center backlash is a risk to the AI build-out, it’s also putting a ceiling on one of bitcoin mining’s worst enemies: endless hash-rate growth.

If bitcoin’s price keeps firming while mining difficulty stays flat, it presents a solid opportunity for bitcoin mining stocks to profit from.

For once, the local zoning board is indirectly doing bitcoin miners a favor.

Good investing,

Eric Wade

Editor’s Note: Trillions of dollars — the largest flood of spending in U.S. history — are pouring into AI and energy. And one little-known company sits right in the path of it, collecting a toll on every dollar that flows past. It doesn’t make a single chip or pump a drop of oil. Whitney Tilson calls it “America’s Greatest Retirement Stock” right now — and today, it’s trading at a rare discount. He’s giving away the name for free. Click here…

The post Bitcoin Miners: A Surprising Winner From the Growing AI Data-Center Backlash appeared first on MarketWise.

❌