❌

Normal view

  • ✇Market Wise
  • Time to Wake Up. Copper Stocks Are the AI Trade Everyone’s Sleeping On. Jonathan Rose
    Everybody’s crowding into the same handful of AI chip names. Meanwhile, the actual bottleneck in the entire AI buildout is a metal that’s been around since the Bronze Age — copper. (Yes, the Chester Copper Pot metal, for my fellow Goonies fans. It always sneaks into my presentations.) And this week copper did something it hasn’t done in a very long time: it printed a brand-new all-time high while the physical supply underneath it keeps getting thinner. As I’m writing this, three-month copper
     

Time to Wake Up. Copper Stocks Are the AI Trade Everyone’s Sleeping On.

8 September 2026 at 13:58

Everybody’s crowding into the same handful of AI chip names. Meanwhile, the actual bottleneck in the entire AI buildout is a metal that’s been around since the Bronze Age — copper. (Yes, the Chester Copper Pot metal, for my fellow Goonies fans. It always sneaks into my presentations.)

And this week copper did something it hasn’t done in a very long time: it printed a brand-new all-time high while the physical supply underneath it keeps getting thinner. As I’m writing this, three-month copper on the LME just tagged a record near $14,700 a ton (an intraday high around $14,694), capping its longest weekly winning streak since 1994. One of my favorite copper stocks is Freeport-McMoRan (FCX), and it’s up better than 7% on the day and roughly 44% on the year.

I’ve been pounding the table on the copper trade on Masters in Trading LIVE for weeks — and I put a real, defined-risk version of it (a specific FCX options play) in our free portfolio, live on the show, which I’ll show you the exact structure of below. Let me walk you through why first.

 AI Runs on Copper, and There Isn’t Enough of It

Here’s the part Wall Street keeps glossing over. An AI data center uses roughly 10 times the copper of a traditional data center. All that compute, all that power delivery, all that cabling — it runs on copper. And a new copper mine takes seven to ten years to build. Supply simply cannot catch up to this demand on any timeline that matters.

Now stack that AI demand on top of a supply chain that’s genuinely cracking:

  • One year ago this week, a wet-material flood hit Freeport’s Grasberg mine in Indonesia — the world’s second-largest copper source — triggering a force majeure. Freeport has cut its 2026 output guidance at the complex by roughly a third, and a full recovery isn’t expected until 2027 or 2028.
  • Chile, the world’s largest producer, just logged its weakest second quarter in at least 19 years and has cut its full-year forecast twice.
  • Global mine output actually fell in the first half of the year. Morgan Stanley started 2026 expecting supply to grow and now sees it flat-to-down — which would be the first annual decline in mine supply since 2017.

As Evy Hambro, BlackRock’s Global Head of Thematic and Sector Investing, put it, existing copper operations are “tired, very, very old assets.” That’s the backdrop: warehouses draining, grades falling, and the biggest demand story of the decade just getting started.

The Copper Tariff Catalyst Nobody’s Fully Pricing In

This is where the edge lives. I don’t just want to be long a strong commodity — I want a known catalyst with a date on it. Copper has one.

Remember: a tariff is just a tax. Back in 2025, Washington slapped a 50% tariff on semi-finished copper products — pipes, wires, rods, sheets — plus copper-intensive derivatives like cables and connectors. But read the fine print: they didn’t tax raw input material or refined copper (cathode) itself. Not yet.

Here’s the timeline that matters:

  • The Commerce Department’s deadline to recommend action on refined copper passed on June 30, and more than two months later the White House still hasn’t ruled.
  • The recommendation on the table is a phased tax on refined copper — 15% in 2027 (possibly as soon as January), stepping up to 30% in 2028.
  • Traders aren’t waiting for the ink to dry. Roughly 200,000 tons of refined copper flooded into the U.S. in July alone — the largest monthly inflow on record — pushing Comex inventories past 1 million tons as buyers race to beat that possible January duty.

When big money moves ahead of a known date, it tips its hand. That’s the footprint I follow. I learned that on the floor — I spent twenty-eight years as a market maker at the CBOE and a floor trader at the CME and CBOT, and all any trader is ever doing is positioning in front of the biggest players in the room. Copper is flashing that exact signal right now.

 The Edge: Only Two Copper Smelters Are Left in America

Here’s the nuance that separates the pros from the crowd. A tax on imported refined copper is a gift to the very few companies that turn raw material into finished copper on U.S. soil. And there are barely any left.

Industry testimony to Congress this year put it starkly: the U.S. ran 16 primary copper smelters in 1976. Today, just two are operational, with a third (Grupo México’s Asarco Hayden in Arizona) mothballed. That’s the entire domestic backbone for refining copper in the world’s largest economy — which is why the U.S. ships roughly a third of the copper it mines overseas to be processed, then buys it back as finished metal. Put a tariff on that finished metal, and you hand enormous pricing power to the two companies that still run a smelter here:

  • Freeport-McMoRan (FCX) runs one of them (its Miami smelter in Arizona). It’s the largest U.S.-listed copper producer, it trades with deep, liquid options, and it’s my single favorite name in the space. The leverage is the story: by management’s own math, every 10-cent move in copper is worth about $390 million in annual EBITDA. It models ~$13 billion in EBITDA at $5 copper and ~$20 billion at $7 copper. Copper’s already trading north of $6.60 a pound. You do the math.
  • Rio Tinto (RIO) owns the other (its Kennecott smelter in Utah). It’s a much bigger, more diversified major — so it’s a steadier, more indirect way to get exposure. Think of Rio as the lower-beta version of the same idea.

That’s the concentrated bet. Now let’s talk about the rest of the group — because not all copper stocks play this story the same way.

The Best Copper Stocks for AI (and the Ones to Approach With Caution)

Copper’s 2026 run has turned the big producers into what basically looks like one trade — the year-to-date returns are clustered in a tight band, which tells you this is a commodity move, not a company-execution move. Names to know:

  • FCX (Freeport-McMoRan) — my top copper stock pick. Most direct U.S. smelter play, deepest options, biggest earnings leverage to the copper price.
  • RIO (Rio Tinto) — the other U.S. smelter; bigger, steadier, more diversified.
  • SCCO (Southern Copper) — a pure-play copper heavyweight, up roughly 45% on the year with monster EBITDA margins. Riding the same wave as FCX.
  • TECK (Teck Resources) — also up ~45% YTD, part of that same tight cluster.

And then there’s the be-careful bucket. Plenty of copper names are just miners — they dig up raw copper and ship it overseas. A U.S. refined-copper tax doesn’t really touch them, and the foreign refiners can actually be hurt by it. That group includes names like Ero Copper (ERO), Hudbay (HBM), First Quantum, Ivanhoe, Capstone, plus the big overseas majors like Vale (VALE) and BHP. Great companies, plenty of them — but they don’t sit on the right side of this specific catalyst. Know what you own and why you own it.

What About Copper ETFs?

If you’d rather not pick a single name, the sector has clean ETF wrappers — just understand what each one actually gives you:

  • COPX (Global X Copper Miners ETF) — a basket of copper miners worldwide. Great for broad exposure to the theme. The trade-off: it dilutes the U.S.-smelter edge, because it holds a lot of those overseas miners the tariff doesn’t help.
  • CPER (United States Copper Index Fund) — tracks copper futures directly. This is your cleanest exposure to the metal itself rather than the equities. If your whole thesis is that the price of copper goes higher, this is the straightforward vehicle.
  • COPJ (Sprott Junior Copper Miners ETF) — smaller, higher-beta junior miners. More torque, more risk.

The way I look at it: the copper ETFs are the easy button for just being in copper. But the edge — the concentrated, catalyst-driven bet — lives in the two American smelters, FCX and RIO. That’s the difference between owning the theme and owning the trade.

The Exact FCX Copper Trade I Shared Free on MiT Live

Here’s what makes our show different: I don’t just talk about copper — I put on a real trade in front of you, live, in our free portfolio — no paywall required to watch me do it. So let me show you exactly how I structured the FCX trade when I shared it on the show.

The Exact FCX Copper Trade I Shared Free on MiT Live

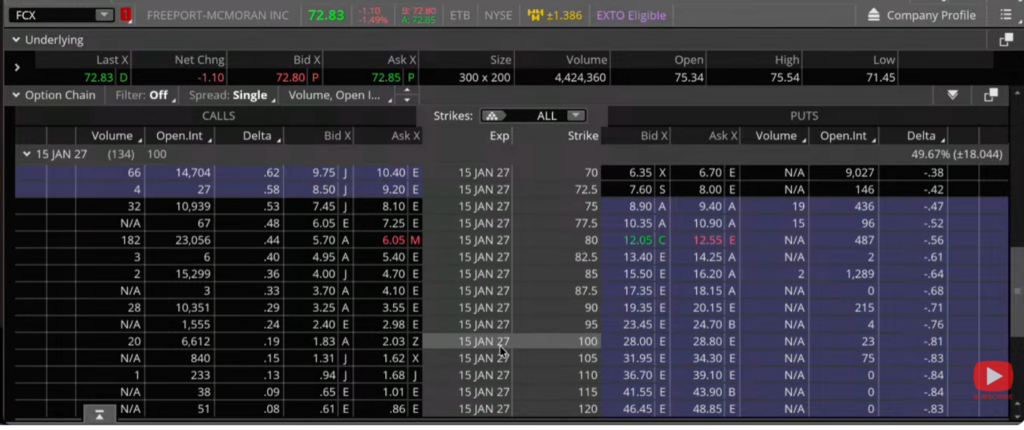
The setup was a vertical call spread in the January 2027 expiration:

  • Buy the FCX 80 call
  • Sell the FCX 105 call

At the time, that spread cost roughly $4.50 to put on — paying about $6 for the 80s and collecting about $1.50 for the 105s. And that number is your risk: in a defined-risk spread like this, the most you can lose is what you pay for it. So one spread risked about $450 — and you can never lose a dollar more than that, no matter what FCX does.

Now the reward. The spread is worth its full width — the 25 points between the 80 and 105 strikes, or $2,500 — if FCX finishes above 105. Subtract the $450 you paid, and the most you can make is about $2,050. That’s better than 4-to-1 — risk $450 to make $2,050 — with about 134 days for the thesis to play out. And it scales cleanly: a 10-lot risks about $4,500 to make about $20,500. Same ratio, just add a zero.

A few things I say every single day on the show:

  • This is one trade, not two. Two legs, one position — a vertical call spread. Don’t manage it as a separate long option and short option.
  • Options are just a derivative of the stock. Think of it as long from 80 and short from 105. If FCX is above your strike at expiration, you’re long from there; if it’s below, you’re not. That’s it — the internet loves to overcomplicate this.
  • New to options? Paper-trade it. Write the trade down, follow FCX, and let your confidence build before you risk a dime.

Options prices move, so the fills above reflect the session when I shared it — and with copper and FCX both pushing to fresh highs since, the picture keeps evolving. But the structure is the lesson: a known catalyst, a strictly defined risk, and a reward that’s several times what you put up.

The Bottom Line on Copper Stocks

AI can’t run without copper. The world is running short of it. And Washington is sitting on a decision that could put a tax on it as soon as January. That’s a supply squeeze, a demand supercycle, and a known catalyst all stacked in one place — and the cleanest way to play it is the two companies that refine copper on American soil, starting with FCX.

Editor’s Note: Forbes calls $1 billion fund manager Louis Navellier “the king of quants.” Today, he’s stepping forward to reveal why he’s investing $358 million of his own firm’s money in the next stage of Artificial Intelligence… a technological sea-change that could erase millions of jobs, solve humanity’s biggest mysteries, and spark a wave of moneymaking opportunities — both in and outside the stock market. Click here for the details… 

Copper Stocks FAQ

Why are copper stocks going up?

Copper just printed a record near $14,700 a ton on the LME, capping its longest weekly winning streak since 1994, while the physical supply underneath keeps thinning. An AI data center uses roughly 10 times the copper of a traditional one, and a new mine takes seven to ten years to build. Demand is surging while supply stalls.

What does the copper tariff mean for copper stocks?


In 2025, Washington put a 50% tariff on semi-finished copper products but left refined copper untaxed, for now. A phased duty on refined copper is on the table, possibly 15% as soon as January 2027 and 30% in 2028. That would hand pricing power to the few companies that refine copper on U.S. soil.

What are the best copper stocks for AI?


The cleanest plays are the two companies that still refine copper on U.S. soil: Freeport-McMoRan (FCX), the largest U.S.-listed producer and the top pick, and Rio Tinto (RIO), a steadier, more diversified option. Southern Copper (SCCO) and Teck Resources (TECK) ride the same commodity wave, both up roughly 45% this year.

Is FCX a good copper stock to buy?


Freeport-McMoRan runs one of only two operational U.S. copper smelters, and its earnings leverage is the story. By management’s own math, every 10-cent move in copper is worth about $390 million in annual EBITDA, and it models around $20 billion at $7 copper. Copper is already trading north of $6.60 a pound.

Are there copper ETFs for the AI trade?


Yes. COPX (Global X Copper Miners) gives broad exposure but dilutes the U.S.-smelter edge with overseas miners. CPER (United States Copper Index Fund) tracks copper futures directly, the cleanest bet on the metal itself. COPJ (Sprott Junior Copper Miners) holds smaller, higher-beta names with more torque and more risk.

What are the risks of copper stocks?


Copper’s 2026 run is largely a commodity move, so the big producers trade like one bet and would fall together if copper retreats. Many copper names just mine raw metal and ship it overseas, so a U.S. refined-copper tariff does not help them and can even hurt foreign refiners. Know what you own and why.

Want to see the next setup like this before it goes on? I break down real, defined-risk trades live every weekday at 11 AM ET on Masters in Trading LIVE — real trades, real time, real community. Come hang out.

The post Time to Wake Up. Copper Stocks Are the AI Trade Everyone’s Sleeping On. appeared first on MarketWise.

  • ✇Market Wise
  • GoPro’s $285 Million Rescue: AI and Defense Pivot Leaves Shareholders With a 10% Lottery Ticket David Engle
    Key Points GoPro’s $285 million sale to Starman Optical could rescue the struggling action-camera manufacturer while giving it an unexpected foothold in AI, defense, and aerospace. The deal would wipe out GoPro’s debt and combine its 2,500-plus patents with Starman’s optical-transceiver business, creating opportunities far beyond action cameras. GoPro shareholders face a choice between taking $1.14 per share or keeping their portion of the remaining 10% stake in a risky new c
     

GoPro’s $285 Million Rescue: AI and Defense Pivot Leaves Shareholders With a 10% Lottery Ticket

8 September 2026 at 13:47

Key Points

  • GoPro’s $285 million sale to Starman Optical could rescue the struggling action-camera manufacturer while giving it an unexpected foothold in AI, defense, and aerospace.
  • The deal would wipe out GoPro’s debt and combine its 2,500-plus patents with Starman’s optical-transceiver business, creating opportunities far beyond action cameras.
  • GoPro shareholders face a choice between taking $1.14 per share or keeping their portion of the remaining 10% stake in a risky new company that could become something much bigger.

To call GoPro (GPRO) a struggling company would be a vast understatement. In the midst of 88 straight days of trading below a dollar per share starting in early June, the action-camera company received a delisting notice from Nasdaq on July 21. GoPro shares hit rock bottom at 57 cents during intraday trading on August 12.

But on September 1, privately held optical-transceivers maker Starman Optical and GoPro released a joint statement announcing that Starman will buy GoPro for $285 million in cash. The deal valued GoPro’s shares at $1.14, a roughly 29.6% premium to the stock’s previous closing price.

Through this deal, Starman would receive a 90% stake in GoPro. Current GoPro shareholders would own the remaining 10% of the company. The agreement amounts to a major lifeline for GoPro, which had roughly $27.3 million in cash but $405 million in current liabilities at the time of the deal.

On August 31, GoPro closed at roughly 88 cents, which actually represented a huge gain from the 60-cent closing price on August 28 (driven by separate news that popular YouTube creator Mark “Markiplier” Fischbach had purchased an 8.5% stake in GoPro in July, driving its trading volume of less than 9 million shares on August 28 to more than 220 million shares on August 31).

On September 1, after the Starman deal was announced, GoPro surged as high as $1.64 – an 87.2% increase – with more than 500 million shares traded for the full day. By market close on September 2, GoPro was up to $1.69, gaining 92.9% in a span of two days.

Whether those levels hold depends largely on how GoPro’s shareholders vote on the deal later in the year.

How GoPro Got Here: A Look at the Struggling Camera Company’s Numbers

Once upon a time (in 2014), GoPro was on top of the world. The company hit a $4 billion valuation on its first trading day that year, and its revenue soared to nearly $634 million during the last quarter of 2014 alone.

How the mighty have fallen…

Here’s a look at GoPro’s 2025 and 2026 (through the second quarter) numbers:

  • Full-year 2025 revenue was $652 million, a 19% year-over-year decline, and just $18 million more than the company’s fourth-quarter 2014 revenue.
  • The company sold about 2 million cameras in 2025, down 20% year over year.
  • Hardware revenue in 2025 fell 21.5% year over year.
  • Second-quarter 2026 revenue was $105 million, down 31% year over year – and, alarmingly, down roughly 80% from that 2014 fourth-quarter peak.
  • Approximately 291,000 cameras were sold in the second quarter, a 38% year-over-year drop.
  • There was a dip in the GAAP (generally accepted accounting principles) gross margin from 35.8% to 30.2%.
  • GAAP net loss was $51 million, or $0.30 per share, compared with a $16 million net loss the year before. Non-GAAP net loss was $36 million, or $0.21 per share, versus a $12 million net loss the previous year.
  • Adjusted EBITDA (earnings before interest, taxes, depreciation, and amortization) took a nosedive from negative $6 million to negative $29 million year over year.

Not pretty. All of this underperformance pushed GoPro to reduce its workforce by 23% in April.

The lone positive? A second-quarter 11% year-over-year increase in subscription and service revenue, to $29 million, and a record 69% subscriber attach rate (the percentage of customers who purchase an add-on service or choose a recurring subscription option).

What’s behind GoPro’s dramatic fall from grace? First, the space has become flooded with competition – namely, cheaper products manufactured by Chinese companies like Insta360 and DJI, which can run as much as $100 to $200 less than comparable GoPro models.

Then there are rising memory-chip costs that are dogging most of the electronics industry. Over the past year, memory-chip prices have skyrocketed by up to an almost unfathomable 500%. Electronics makers are beginning to pass those costs down to consumers.

With those concerns in mind, as well as GoPro’s $92 million in debt, it’s safe to say that Starman Optical came along at the right time.

Starman Optical: Is the Optics Business a Good Fit for GoPro?

If you hadn’t heard of Starman Optical before this deal, welcome to the club. The privately held company is part of the larger Starman family, which includes consumer brands such as Griffin, Incase, and Incipio, as well as medical, distribution, and real estate businesses.

Starman New Photonics is the arm under which Starman Optical operates. And Starman Optical was literally incorporated in Delaware on August 31, the day before the GoPro acquisition was announced. So, it’s very new. And it’s a very different direction for GoPro.

The GoPro you’re familiar with is a leading maker of action cameras and accessories. This new version of GoPro will still maintain its retail camera business. But it will soon add defense, government, robotics, aerospace, fiber-optics, and artificial intelligence (“AI”)-infrastructure markets to its portfolio under Starman.

When announcing the deal, the companies noted that this combination would better leverage GoPro’s impressive number of U.S. patents (more than 2,500) by incorporating its innovations into optics and imaging components that can be used in the defense and AI markets.

And it might be the best thing that has happened to GoPro since 2014.

Why the Pivot to Defense and AI Makes Sense for GoPro

The match between GoPro and Starman Optical makes perfect sense: Many of GoPro’s patents involve optics and imaging technology, and Starman Optical is an expert in making the optical transceivers used in AI data centers.

(These transceivers convert electronic data signals into high-speed light pulses to connect AI processors, servers, and network switches. This helps keep the data flowing while AI clusters train large models.)

Combining these elements could pay off for both companies, considering the AI optical-transceiver market is taking off. TrendForce research predicts the market will hit $26 billion in 2026, up nearly $10 billion from last year.

The fact that Starman’s transceivers are built in the U.S. is another advantage, with the Federal Communications Commission proposing a ban on Chinese-made transceivers to protect AI data-center security.

Financially, this deal is a lifeline for GoPro, as the acquisition will pay off GoPro’s $92 million debt. That should allow the company to focus on new products both for consumers and for Starman Optical.

With AI-infrastructure spending reaching mind-blowing proportions and an aerospace and defense industry worth roughly $900 billion, the GoPro/Starman coupling could be a match made in heaven if Starman can successfully integrate GoPro’s patented technologies into products for these markets.

That’s something GoPro could never have accomplished on its own as a consumer-focused action-camera manufacturer.

The GoPro Shareholder Dilemma: Take the Money or Keep the 10% Lottery Ticket?

Here’s where things get tricky for GoPro shareholders. They have two choices, assuming the deal passes: Take the $1.14 per share, cash out, and move on. Or keep the “lottery ticket” stub – each shareholder’s portion of the collective 10% stake in the new GoPro-Starman venture – and hope for the best.

The problem is that no one really knows what that lottery ticket will be worth.

After all, we’re talking about:

  • A company (Starman Optical) whose incorporation is literally days old.
  • An entity (Starman New Photonics) that owns Starman Optical and GoPro that is still growing and not yet turning a profit.
  • A newly formed operation (Starman Optical and GoPro) that has not yet designed any new products, let alone built and sold them.

In other words, shareholders face substantial unknowns. A lot must go right for GoPro stock to gain value above its $1.14-per-share sale price. The first step involves Starman New Photonics successfully opening its new 100,000-square-foot manufacturing facility in Warren, New Jersey.

From there, Starman must increase production of its core Liberty Series 800G and 1.6T transceivers, which are just starting low-volume shipments and undergoing further testing, respectively. The 800G transceivers likely won’t ramp up production until late this year.

While the GoPro-Starman partnership certainly appears promising, there’s no guarantee it will succeed. It will take some time for the two companies to put their collective heads together and design, test, build, and sell new products that potential aerospace, defense, and AI customers will want.

If new government, military, and/or hyperscaler contracts are secured reasonably soon, hanging on to the collective 10% stub may prove worthwhile. Unfortunately for shareholders, there’s simply no way of knowing what the future holds for GoPro.

What to Watch in the Coming Months

As I noted, Starman is expected to expand production of its 800G transceivers later this year, depending on when the New Jersey factory opens. A smooth rollout is worth monitoring there, as are the next stages of 1.6T transceiver testing and initial factory production.

Even more important, however, is the shareholder vote, which will likely occur in November or December, before the deal closes (presumably by the end of the year). Once the mechanics of the deal (cash, plus the 10% stub) are confirmed against the proxy, which should occur in October or November, GoPro shareholders will decide whether to sell the company to Starman.

This is a key development for potential GoPro investors to watch.

If the vote passes, which is expected, the safe bet is that the stock probably won’t drop below the $1.14 share sale price. Even if it does, investors who buy GoPro shares before the deal closes are guaranteed $1.14 per share, so they’ll get their money back anyway.

But if the vote fails, that $1.14 floor disappears, and the stock will probably crash back down to its pre-merger levels. We will find out in a few months.

Is GoPro Worth the Risk?

That depends on your level of risk tolerance. If GoPro and Starman can create some high-quality products that appeal to the aerospace, defense, and AI industries, this could be a worthwhile investment that pays off a few years from now.

But those are big ifs. And they’re not the only ones. Keep in mind that GoPro was once a highly successful company that found its niche in selling action cameras to outdoor enthusiasts, athletes, and content creators – until it wasn’t.

Between cheaper Chinese competition, rising memory costs, and major improvements in smartphone cameras, GoPro lost its footing… and nearly everything else.

Since 2014 and its initial $4 billion valuation, GoPro has lost 96% of its value. (Yes, 96%.)

With this deal, however, GoPro gets a rare second chance, not only to sell more cameras, but to reinvent itself as a business. Time will tell how two very different companies and product offerings mesh.

But with GoPro’s innovation and 2,500-plus patents, Starman Optical probably feels like a kid in a candy store, with tons of opportunities yet to be discovered. It won’t happen overnight, though. Impatient investors may want to steer clear. But for those willing to give the GoPro-Starman merger some time to bake, the payoff may be worth the wait.

Regards,

David Engle

Editor’s Note: It’s easy to assume the AI story begins and ends with the big-name chip stocks. But there’s a quieter version of it playing out inside the defense budget – where the government isn’t just regulating AI, it’s starting to buy into the companies that build it.

A forensic accountant named Joel Litman – someone the Pentagon and FBI have actually consulted, and who called both the 2008 and 2020 crashes – argues this is one slice of a much bigger shift he calls the “Second Declaration.” He believes a handful of companies sitting where AI meets national defense could be repriced when a policy deadline arrives this November.

Watch his full presentation here → LINK

The post GoPro’s $285 Million Rescue: AI and Defense Pivot Leaves Shareholders With a 10% Lottery Ticket appeared first on MarketWise.

❌