❌

Reading view

Screening For Compounders On Porter’s 3x Screen

An important part in our analytical toolbox is our stock screens, where we apply a list of criteria – relating to different financial, accounting, and performance parameters – to sift through the 3,000+ publicly traded stocks on U.S. markets. That’s how we identify the tiny fraction of U.S.-listed stocks that offer the best opportunities for creating huge returns.

We are revisiting a popular stock-filtering tool we call “Porter’s 3x Stock Screen.” Over the last 25 years, buying an equally-weighted basket of stocks generated from the 3x screen has tripled the return over the overall stock market (the S&P 500). Below we also show the names of significant stocks hitting 52-week highs and 52-week lows – a helpful list that we use to guide our analysis.

Porter’s 3x Stock Screen

The 3x Screen was inspired by Porter himself, who challenged the Complete Investor analyst team to create a filtering tool to find companies with high capital efficiency, steady revenue growth, and that trade at reasonable valuations… and to backtest the results to ensure the screening criteria selected stocks that generated market-beating gains over time.

To see the criteria used to create “Porter’s 3x Stock Screen,” go here.

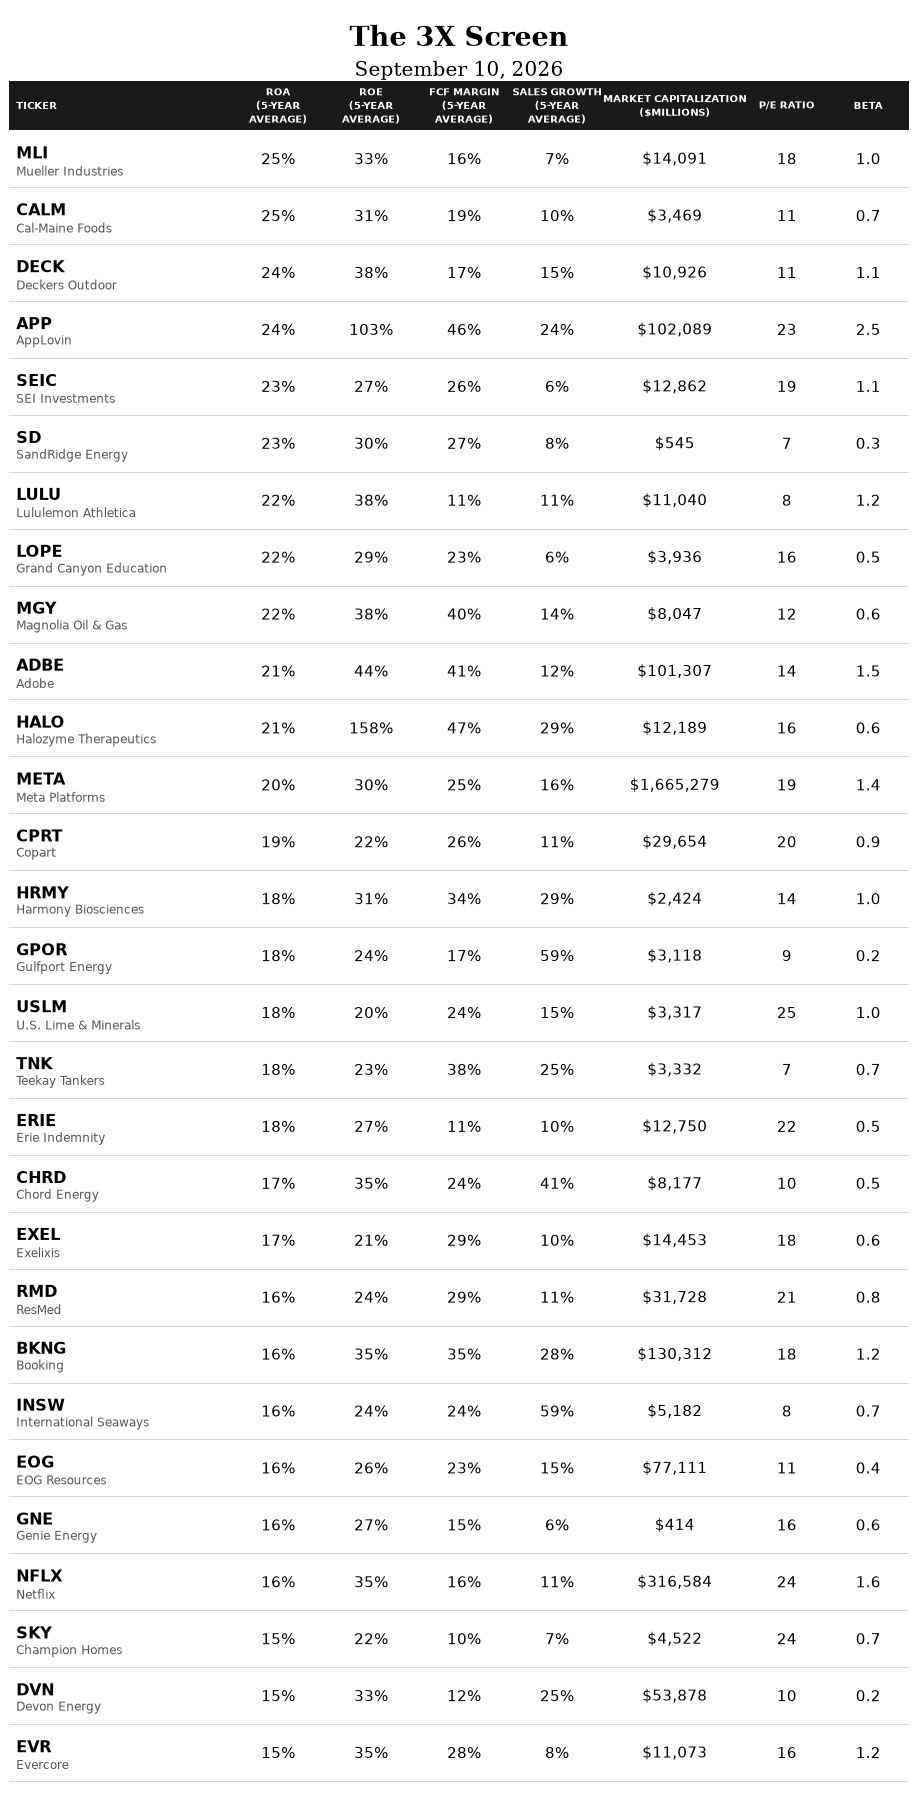
As of Thursday’s close, this screen produced the 29 stocks shown in the table below. We have displayed each of the criteria noted above along with each company and ticker symbol, as well as each stock’s beta (a measure of volatility versus the overall market). Note that beta is not used in the screening criteria, but rather to provide a reference point for noting the volatility of the stocks on the list.

Next, the highs and lows.

Highs And Lows

Each week, we also monitor any stocks in the market making new 52-week highs. We do this because any stock on its way to generating 2x, 3x, or 10x returns will spend a lot of time making new 52-week highs along the way. Thus, the new 52-week-high list provides an opportunity to flag these potential high performers before they really break out, with a particular emphasis on lower-profile, less widely-followed stocks that might have otherwise gone unnoticed.

Notable stocks making a new 52-week high this week:

  • Chevron (CVX)
  • ConocoPhillips (COP)
  • Valero Energy (VLO)
  • Marathon Petroleum (MPC)
  • Bank of New York Mellon (BNY)
  • Phillips 66 (PSX)
  • State Street (STT)
  • Archer-Daniels-Midland (ADM)
  • Okta (OKTA)
  • HP (HPQ)
  • American Water Works (AWK)
  • Expeditors International of Washington (EXPD)
  • Best Buy (BBY)
  • Plains All American Pipeline, L.P. (PAA)
  • Exelixis (EXEL)
  • Bio-Techne (TECH)
  • Qorvo (QRVO)
  • Jackson Financial (JXN)
  • PBF Energy (PBF)
  • SM Energy Company (SM)
  • 10x Genomics (TXG)

Presented By: Tuttle Capital Management


We also monitor stocks on the new 52-week-low list. In many cases, the names on this list are there for good reason – the market is often correctly pricing in weak fundamentals. However, once in a while, a great business with excellent long-term prospects finds itself on this list due to a temporary setback. This can create the rare opportunity to buy top-shelf merchandise at bargain-basement prices.

Notable stocks making a new 52-week low last week:

  • PepsiCo (PEP)
  • McDonald’s (MCD)
  • TJX (TJX)
  • Lowe’s (LOW)
  • Stryker (SYK)
  • AON (AON)
  • TransDigm (TDG)
  • CRH (CRH)
  • Nike (NKE)
  • AutoZone (AZO)
  • L3Harris Technologies (LHX)
  • Exelon (EXC)
  • Medline (MDLN)
  • IDEXX Laboratories (IDXX)
  • D.R. Horton (DHI)
  • Public Service Enterprise Group (PEG)
  • Martin Marietta Materials (MLM)
  • WEC Energy Group (WEC)
  • Vulcan Materials (VMC)
  • Baidu (BIDU)
  • Carnival (CCL)
  • Zoetis (ZTS)
  • Las Vegas Sands (LVS)
  • Ryanair (RYAAY)

Porter & Co.
Stevenson, Maryland

The post Screening For Compounders On Porter’s 3x Screen appeared first on Porter & Co..

  •  

The Next Lindy Payments Network

In a market obsessed with quarterly results and narratives that change by the week, today’s screen searches for the exact opposite – companies that are built to last for decades. The screen identifies the next generation of enduring businesses – before they’re widely recognized.

The Emerging Lindy Screen is about finding future Lindys: businesses that combine invention with discipline, transforming broken industries through structural innovation, vertical integration, and cultural resilience. The screen is designed to uncover the next Amazon or Apple – the types of compounding machines we aim to own long before the world catches on.

In today’s Sunday Selection, we report on a business that has quietly assembled the traits of an Emerging Lindy – the first company in 60 years to build both sides of a new payments network, where every merchant added makes it more useful to consumers, and every consumer added raises the cost of staying out for merchants. Its founder architected it from day one as a vertically integrated, software-defined, data-preserving network – a foundation built to carry product after product, from everyday financial services to advertising tools for merchants.

To see the criteria used to create The Emerging Lindy Screen, go here.

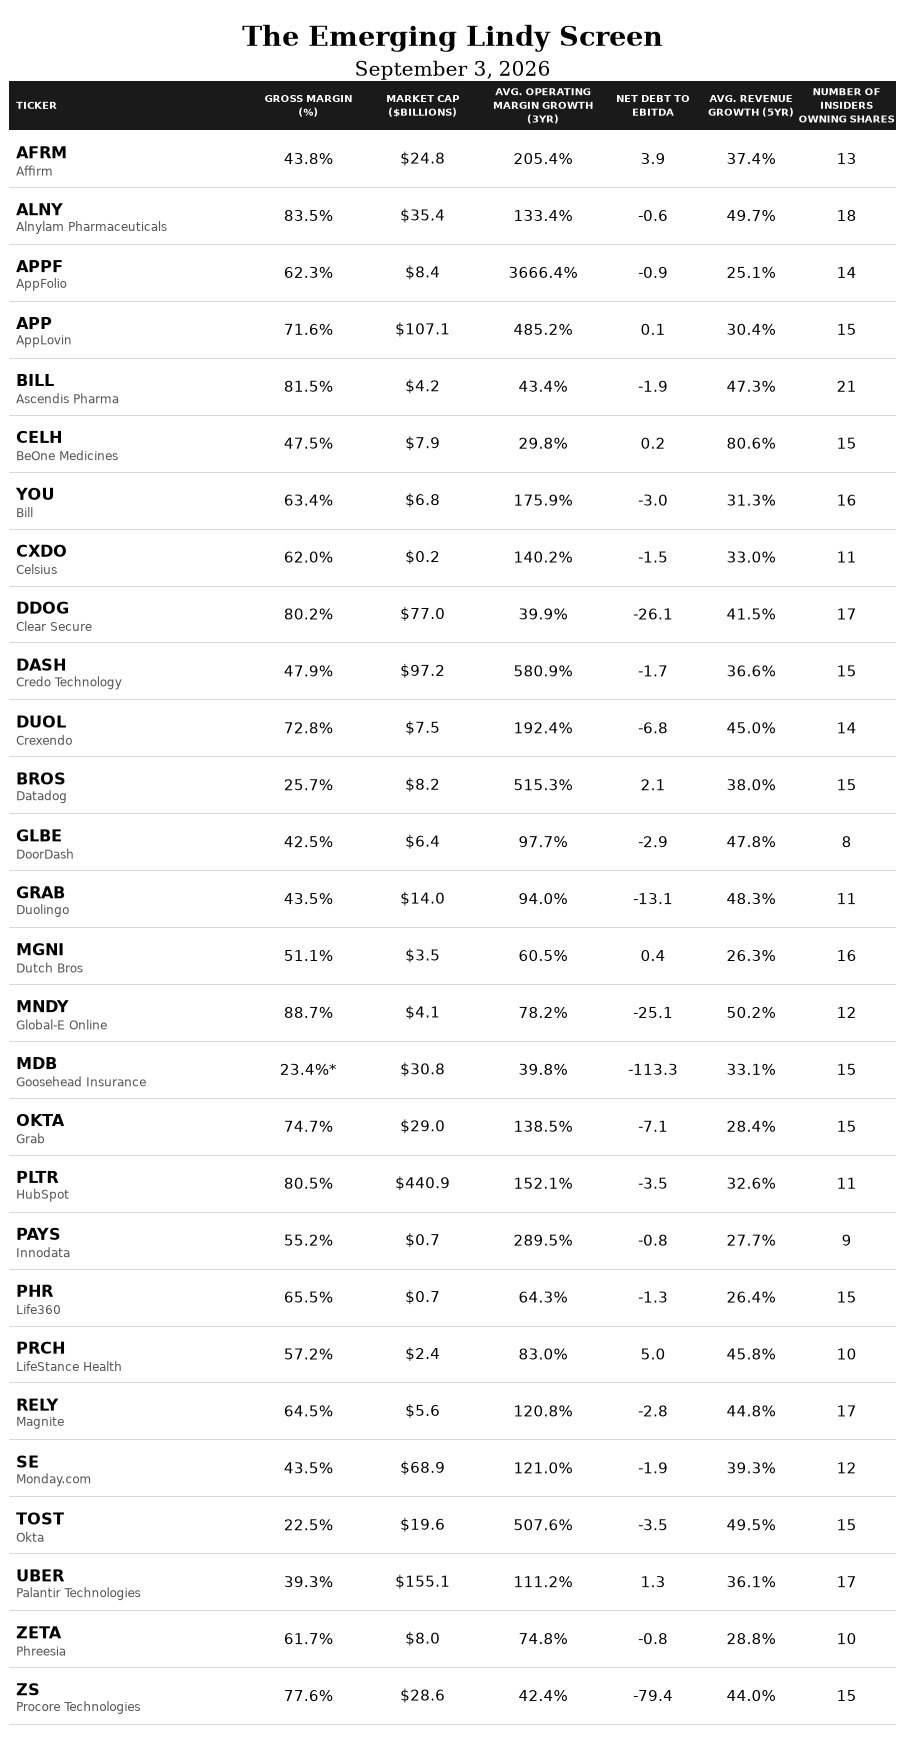
As of the close of trading on Thursday, September 3, the following 28 stocks met these criteria:

Highs And Lows

Each week, we also monitor any stocks in the market making 52-week highs. We do this because any stock on its way to generating 2x, 3x, or 10x returns will spend a lot of time making new 52-week highs along the way. Thus, the 52-week-high list provides an opportunity to flag these potential high performers before they really break out, with a particular emphasis on lower-profile, less widely-followed stocks that might have otherwise gone unnoticed.

Notable stocks making a 52-week high this week:

  • JPMorgan Chase (JPM)
  • Visa (V)
  • Johnson & Johnson (JNJ)
  • Mastercard (MA)
  • AbbVie (ABBV)
  • Chevron (CVX)
  • Dell Technologies (DELL)
  • Amgen (AMGN)
  • Salesforce (CRM)
  • Verizon Communications (VZ)
  • Deere & Company (DE)
  • ConocoPhillips (COP)
  • Pfizer (PFE)
  • Vertex Pharmaceuticals (VRTX)
  • Bristol-Myers Squibb (BMY)
  • Marathon Petroleum (MPC)
  • The Bank of New York Mellon (BNY)
  • Valero Energy (VLO)
  • Phillips 66 (PSX)
  • Regeneron Pharmaceuticals (REGN)
  • MetLife (MET)
  • Corteva (CTVA)
  • State Street (STT)
  • Ameriprise Financial (AMP)
  • Atlassian (TEAM)

Presented By MyWallSt


We also monitor stocks on the 52-week-low list. In many cases, the names on this list are there for good reason – the market is often correctly pricing in weak fundamentals. However, once in a while, a great business with excellent long-term prospects finds itself on this list due to a temporary setback. This can create the rare opportunity to buy top-shelf merchandise at bargain-basement prices.

Notable stocks making a 52-week low last week:

  • McDonald’s (MCD)
  • TJX (TJX)
  • Lowe’s (LOW)
  • TransDigm (TDG)
  • Nike (NKE)
  • Honeywell Aerospace (HONA)
  • L3Harris Technologies (LHX)
  • AutoZone (AZO)
  • IDEXX Laboratories (IDXX)
  • Public Service Enterprise (PEG)
  • Martin Marietta Materials (MLM)
  • Carnival (CCL)
  • Las Vegas Sands (LVS)
  • Otis Worldwide (OTIS)
  • Xylem (XYL)
  • CMS Energy (CMS)
  • Rollins (ROL)
  • Constellation Brands (STZ)
  • Textron (TXT)
  • Wynn Resorts (WYNN)
  • Builders FirstSource (BLDR)

The Making Of The Next American Express

This week’s Sunday Selection comes off today’s Emerging Lindy screen. Payment networks are some of the most Lindy businesses ever created.

The oldest payments company in America – American Express (AXP) – has been operating since 1850. The technology behind the most widely used payment rails today – Visa (V) and Mastercard (MA) – was designed in the 1950s and 1960s. Once a financial network reaches critical mass, it almost never dies – it simply compounds. Which is why it is remarkable that no company has successfully built a new payments network at the scale of these behemoths. Today Visa and Mastercard are worth a combined $1.2 trillion, and American Express another $200 billion.

The company featured in today’s Sunday Selection is a founder-led business that has quietly assembled both sides of a new payments network – tens of millions of consumers on one side and a large share of American commerce on the other. This year it crossed the threshold every young network must cross – from burning cash to generating it – and just reported the most profitable quarter in its history. Yet the stock trades almost exactly where it did one year ago.

⚙ Edit 🗑 Delete

(To become a Partner Pass member, contact our Customer Care team at 888-610-8895, internationally at +1 443-815-4447, or via email at support@porterandcompanyresearch.com.)

Today’s Sunday Selection is Affirm Holdings (Nasdaq: AFRM). Its founder and CEO, Max Levchin, was the original engineer behind PayPal (PYPL). In 2002, freshly minted as a multimillionaire from PayPal’s IPO, Levchin was denied a car loan – a failed college startup had wrecked his credit score a decade earlier.

The denial was a shock and an embarrassment – and it planted the question Affirm was founded to answer: why is the American credit system designed so that the lender wins when the borrower stumbles?

A credit card is an open tab – the bank grants you a limit, the balance revolves, and interest compounds on whatever you carry. Affirm’s model – an improved version of buy now, pay later (“BNPL”) – flips that: each purchase is its own small loan, with a fixed number of payments, a fixed end date, and the total dollar cost shown before you buy.

Underneath that simple product is the machinery that makes it possible. Every loan is underwritten individually, in real time, with full knowledge of what is being purchased. There are no late fees, no deferred interest, and no gimmicks. In an industry that collects roughly $15 billion per year in late fees alone, Affirm structured itself so that it only makes money when its borrowers succeed and repay their loans. That alignment is the backbone of Affirm’s moat, and the design principle the entire network is built on: underwrite every transaction, and never profit from a customer’s failure.

There was one problem. No company had built a new payments network at scale in 60 years, because networks have a cold-start problem – merchants will not join without consumers, and consumers will not join without merchants. Affirm cracked the code by entering through the merchant’s income statement. It did not sell payment acceptance – Affirm sold demand. Merchants who added Affirm’s BNPL at checkout saw conversion rates rise 28%, and roughly 70% saw larger average carts. That gave merchants a reason to join on day one, and merchants delivered consumers for free – it is why Amazon (AMZN), Walmart (WMT), and Shopify (SHOP) all partnered so deeply with Affirm. Every repayment then sharpened the underwriting models, and the models turned into the moat: Affirm’s 30-day-plus delinquencies run below 3% – 100 to 300 basis points better than large consumer lenders like Capital One and Synchrony – despite a loan book that is roughly 44% non-prime, a higher share than any of those lenders carry.

Over the past year, the business model has gained momentum. As Levchin described in the latest shareholder letter, in a well-designed network, the cost of not participating rises as the network itself scales. With roughly 28 million active consumers now expecting Affirm at checkout, the merchant without it is the one with the conversion problem – which is why Crate & Barrel, Backcountry, and Bed, Bath & Beyond’s brands all signed on just this summer.

And once merchants join, they do not leave – they process more and more transactions. Well-managed networks see very little churn at scale, and Affirm’s numbers prove that it belongs in the upper echelon of this class: merchants already offering Affirm have expanded their volume at a dollar-based net expansion rate averaging 120% over the past three years. That means even if Affirm never signed another merchant, the existing base alone would grow the network 20% per year.

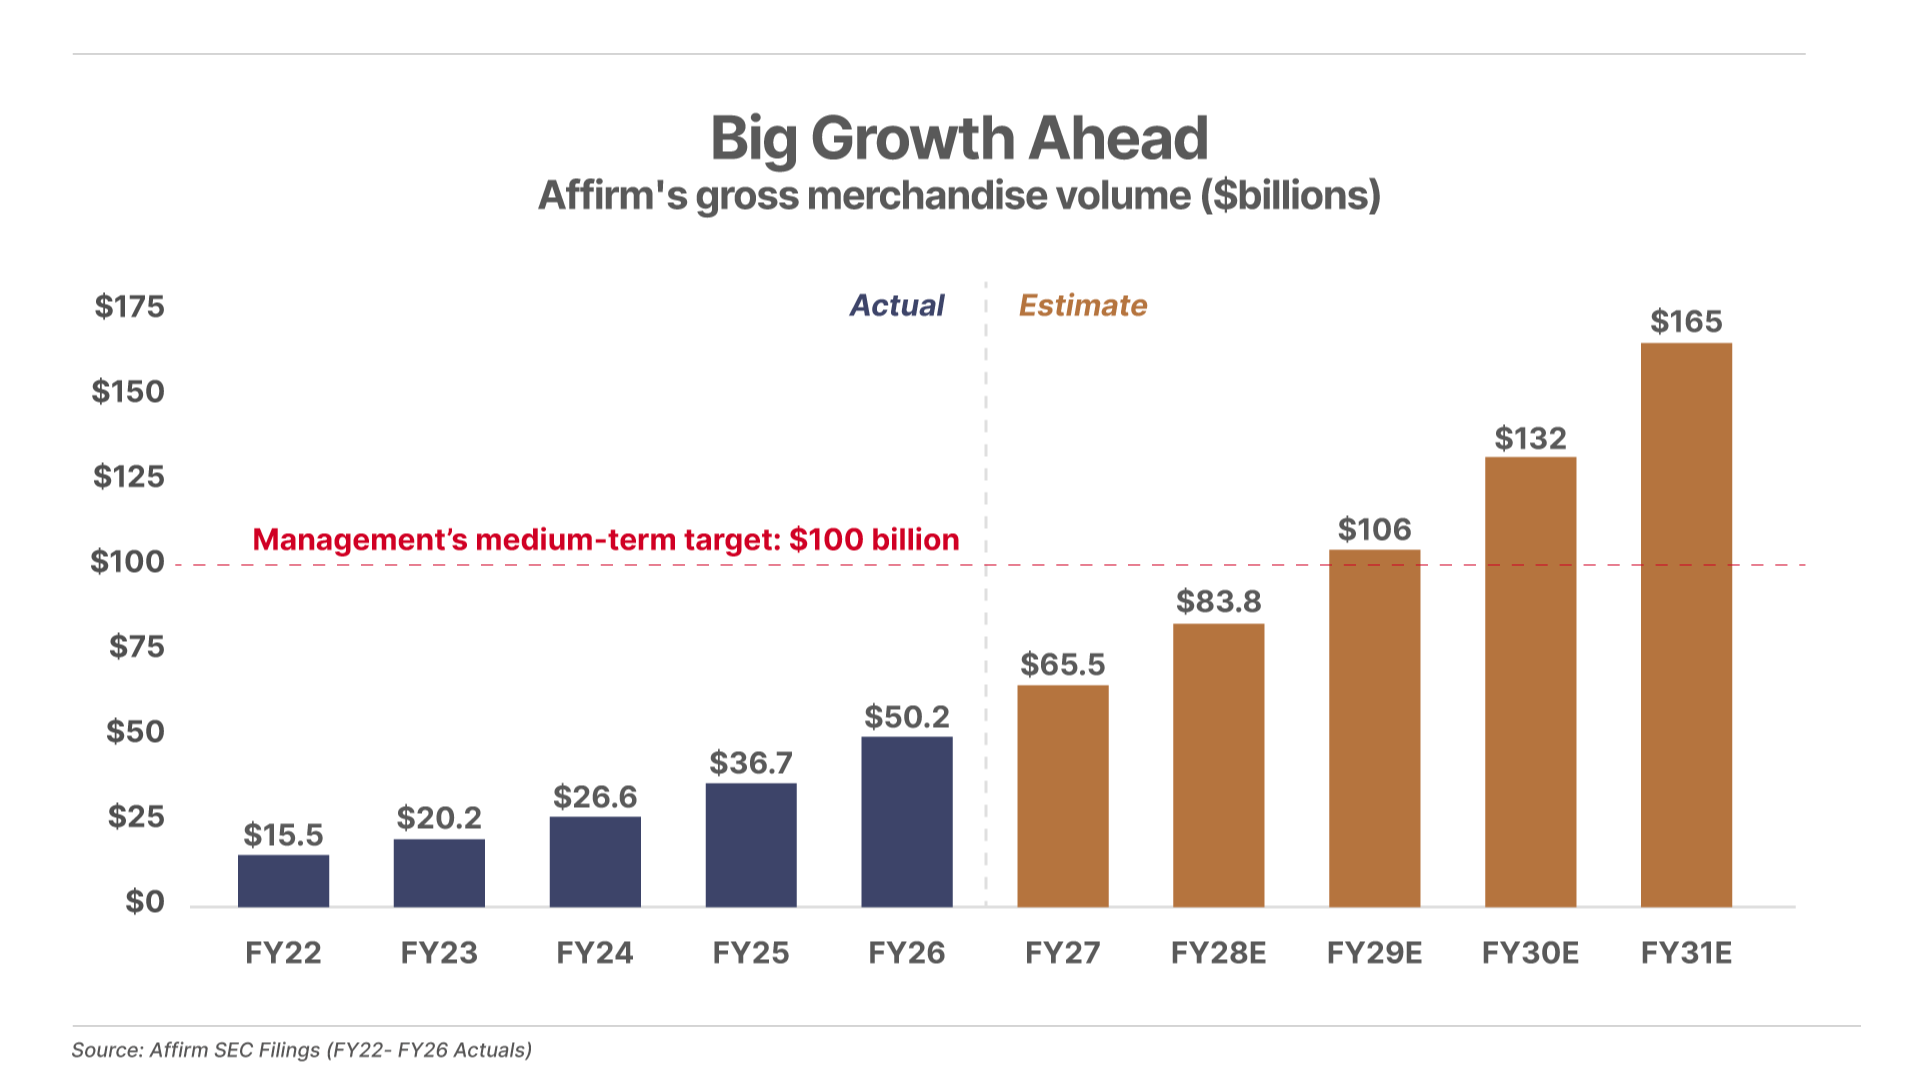
Affirm processed $50.2 billion of gross merchandise volume (“GMV”) in fiscal 2026, up 37% – adding roughly $13.5 billion of incremental volume in a single year, nearly as much as the entire network processed in all of fiscal 2022.

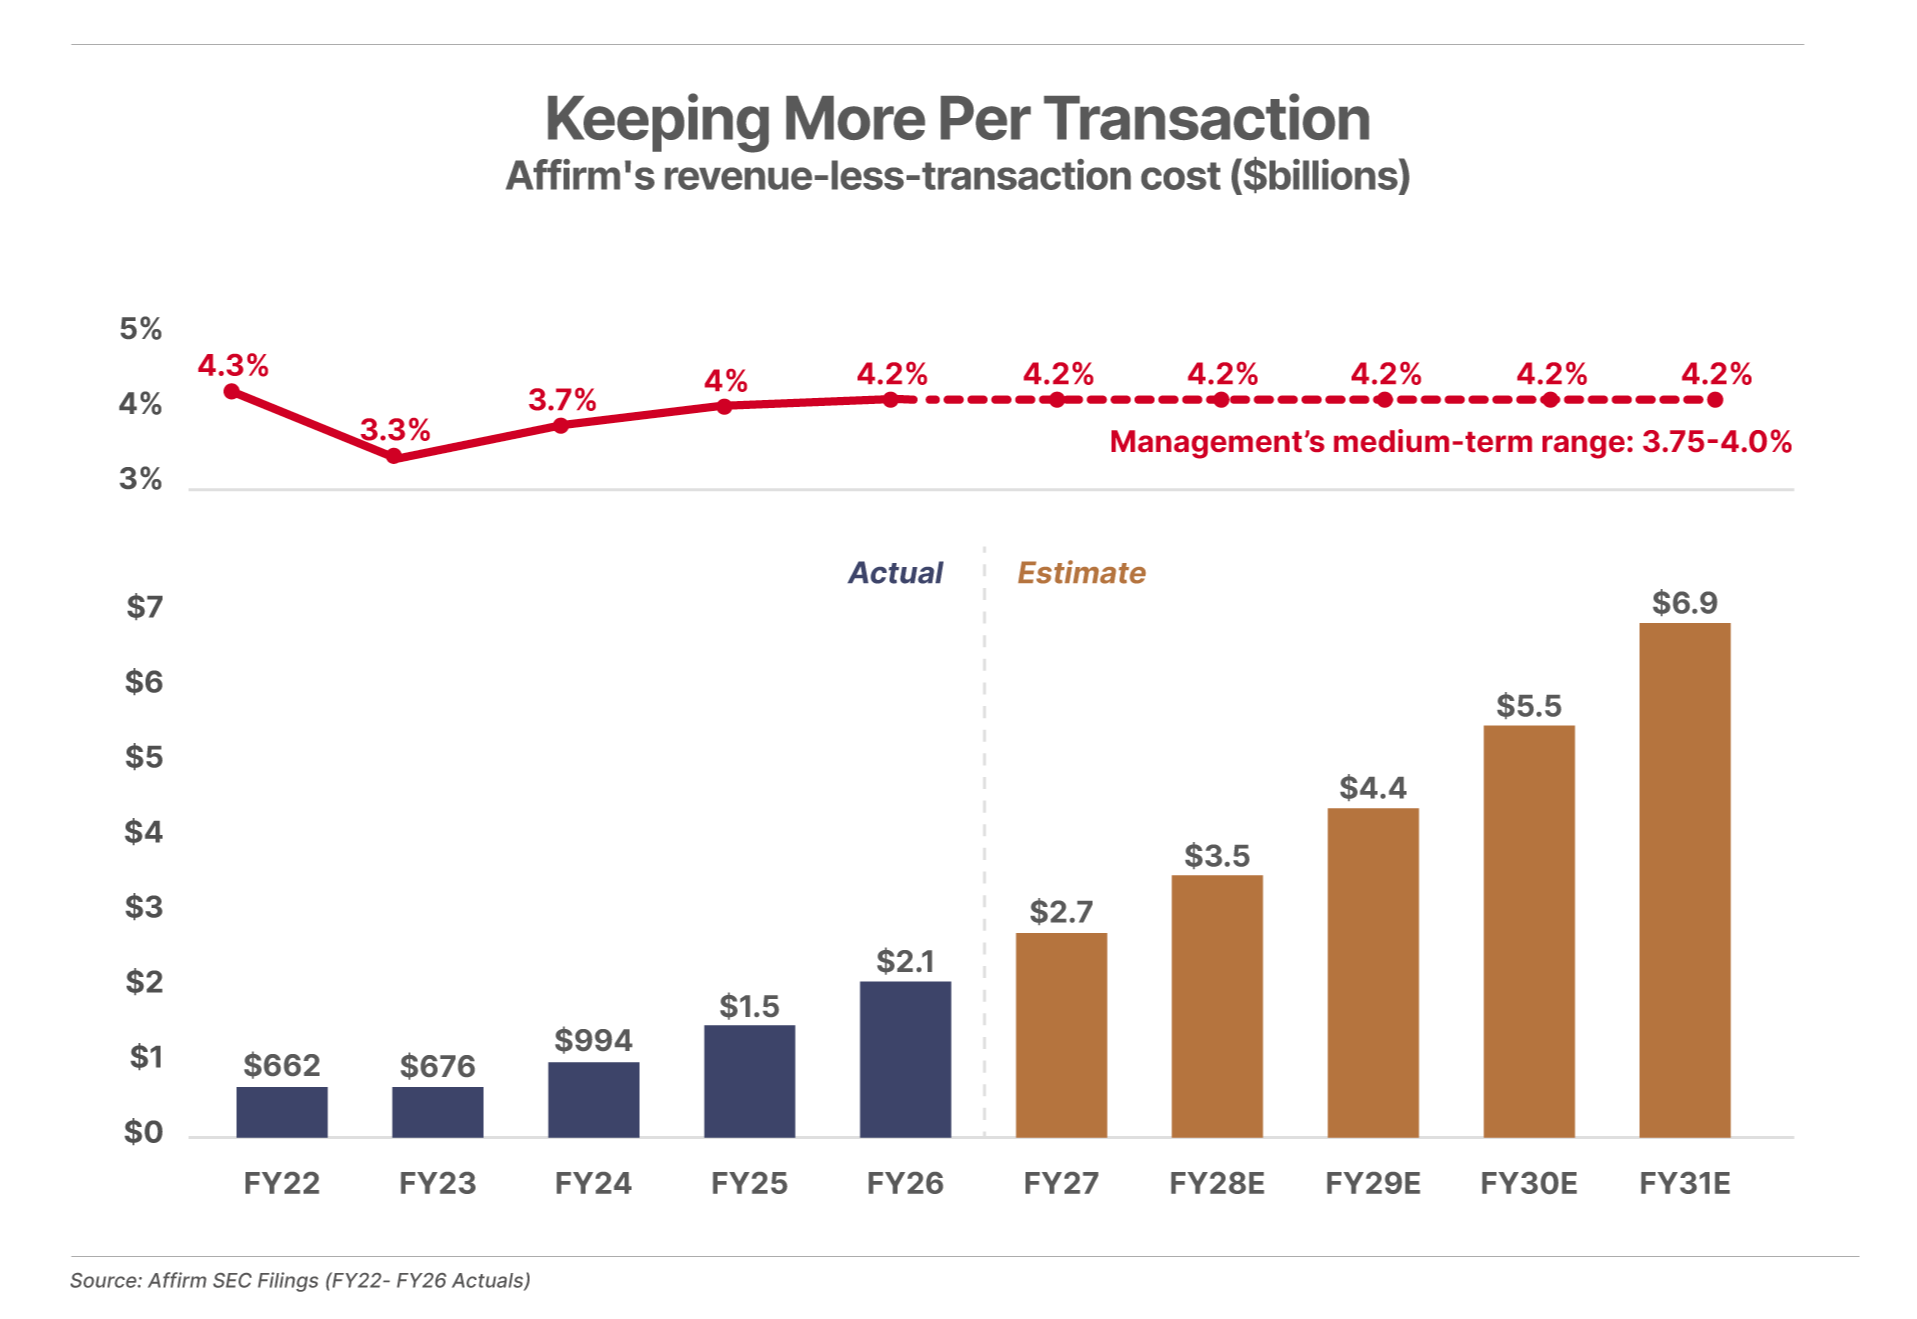
For perspective, Visa and Mastercard grow volume 8% to 10% per year. And Affirm’s growth is not the same as that of the payments companies it gets lumped in with. Stripe processes enormous volume, but for one side only – it has no consumer relationship. PayPal owns consumers, but moves money above through Visa. The difference shows up in the economics: Affirm keeps more than 4% of every dollar that crosses its network after funding costs and credit losses – what the company calls revenue less transaction costs (“RLTC”) – versus the 2% to 3% the card ecosystem collects for simply moving money.

Affirm is the only company at scale that owns both sides of the network, underwrites every transaction in-house, and does so profitably. Meanwhile, Affirm is still live on only 75 of the top 250 U.S. e-commerce sites, and roughly 10% of e-commerce merchants overall – leaving plenty of share to grab.

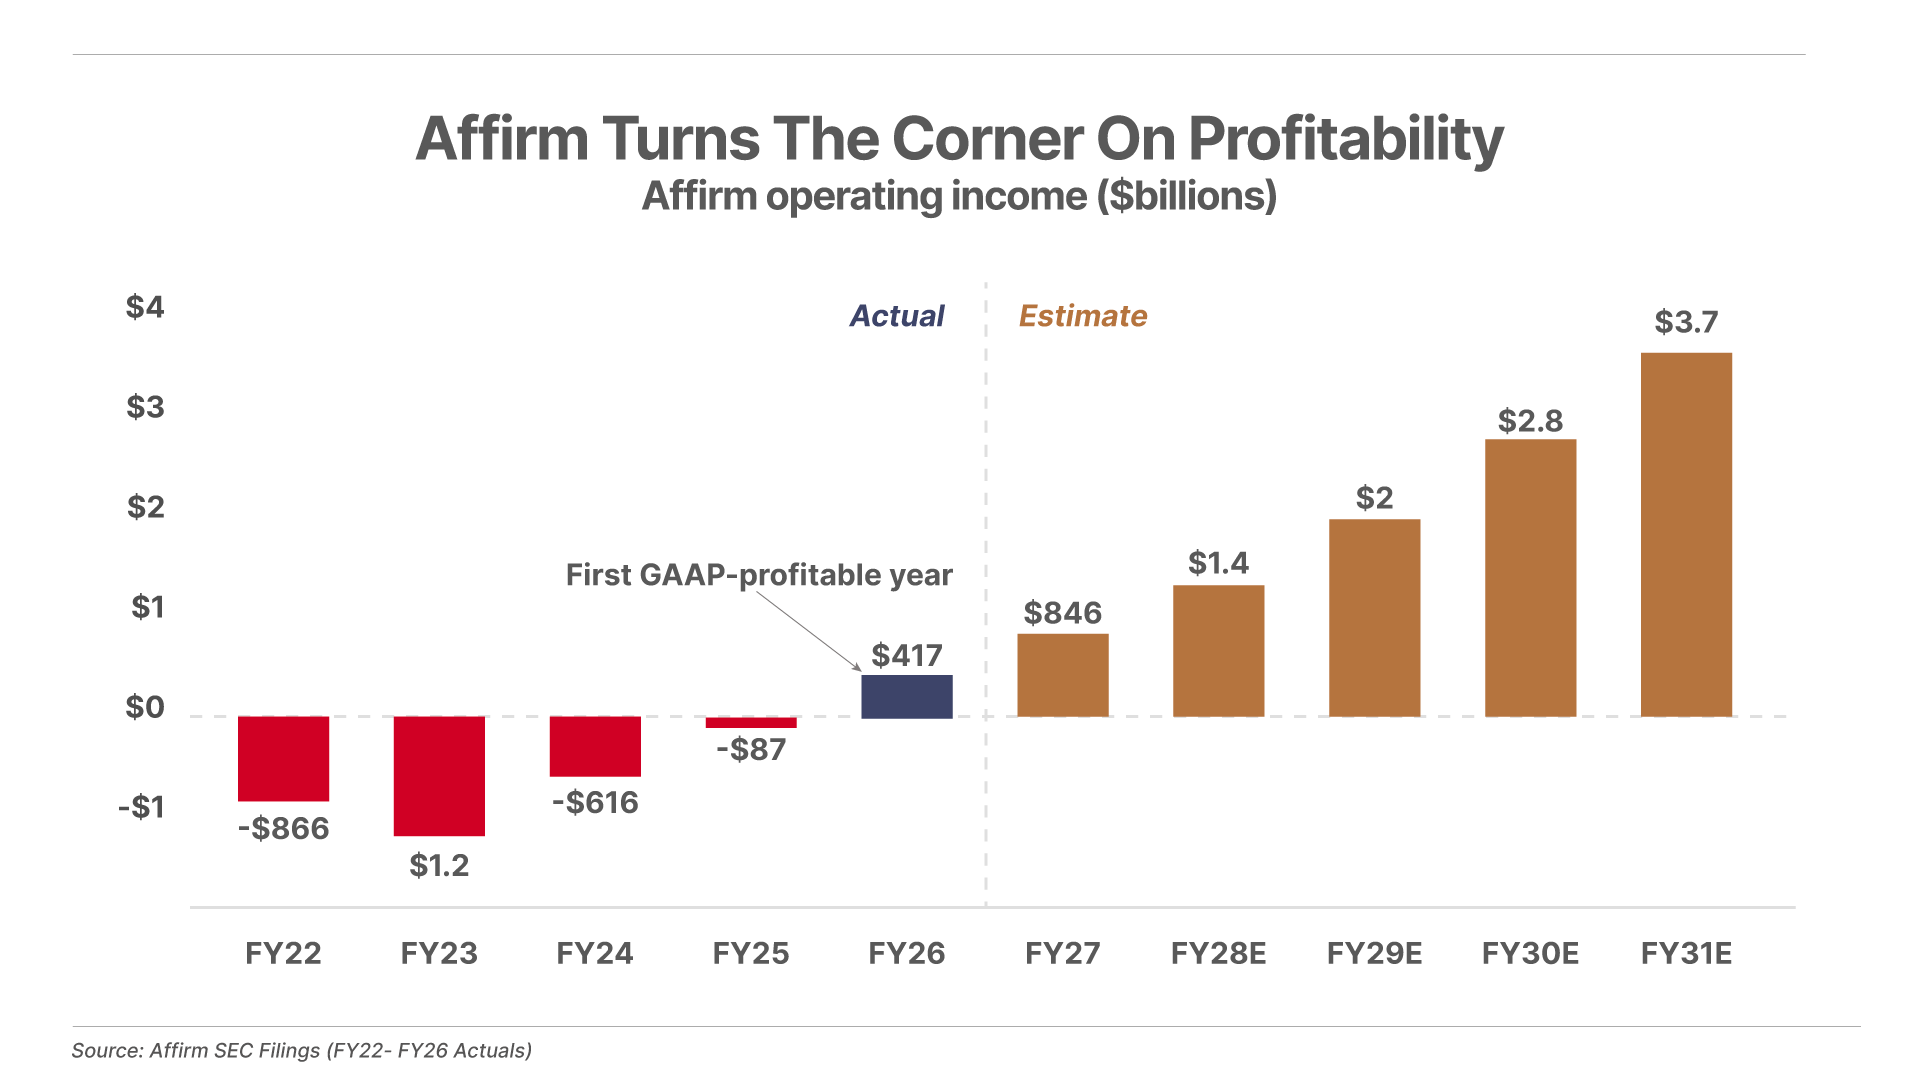
Affirm’s largest operating loss came in fiscal 2023 at $1.2 billion when interest rates surged. But Affirm’s loans are short-duration assets, so the company repriced its entire book within a few quarters – producing a $1.6 billion swing to $417 million of operating profit in fiscal 2026, on the same business model the market had written off.

From fiscal 2024 to fiscal 2026, roughly 53 cents of every incremental revenue dollar fell straight to the operating bottom line. That is the signature of a network, not a lender – the ledger, the risk models, and the merchant integrations are already built and paid for, so each new dollar of volume carries very little cost beyond funding and credit.

What separates Affirm from a typical growth company is that the network keeps manufacturing new growth verticals. Each of Affirm’s businesses has followed an S-curve – slow adoption while the product finds its footing, then a steep run of growth as it catches on, then a plateau as the market matures.

The first S-curve – online checkout – is largely won. More than 60% of U.S. e-commerce already runs through merchants that offer Affirm. The second S-curve is live right now: the Affirm Card, which brings per-transaction underwriting to the physical world, where roughly six times more spending happens than online. The card works like a debit card for everyday purchases – but any transaction over $50 can be converted into an installment plan from the Affirm app within 48 hours, putting pay-over-time in the consumer’s pocket instead of at a merchant’s checkout page.

Card GMV grew 124% last quarter to an annualized run rate above $11 billion, active cardholders doubled to 5.2 million, and cardholders spend about twice as much as typical Affirm users. Yet only 19% of Affirm’s consumers carry the card – the steep, profitable part of this curve is ahead. Management’s long-term vision of 20 million cardholders spending $7,500 per year implies roughly $150 billion of GMV from the card alone.

The clearest tell that more S-curves are coming is how the founder spends his time. Levchin has always framed Affirm as a 30-year mission to do what PayPal never did – own both sides of the ecosystem, merchant and consumer alike. And with Michael Linford promoted to president to run daily operations, Levchin is freed up to chase the next S-curve full time, at the exact moment the core business has started printing the cash to fund it.

That next S-curve is already visible – and it runs through the banks themselves. Affirm spent a decade winning online checkout. It is now three years into putting a card in consumers’ wallets. And it is now encroaching on the banking system.

It’s looking at two options – becoming its own standalone chartered bank or creating a product (Affirm Edge) that embeds Affirms installment lending inside bank and credit-union apps. If the banking application succeeds, the near-term upside is modest – the bank would originate roughly half of Affirm’s loans but hold only a fraction on the balance sheet, reclaiming the fees and interest currently shared with partner banks, worth perhaps 15 to 30 basis points on that volume. The long-term math is what matters: once the bank is allowed to keep what it originates, insured deposits replace capital-markets funding at roughly 100 to 150 basis points less – every $10 billion moved on-balance-sheet is worth about $100 million of pre-tax income – and that balance sheet grows with Affirm’s own retained earnings. Nobody is modeling that yet, including Affirm. The application is pending in the friendliest charter environment in two decades, with GM and Ford both winning conditional approvals days before Affirm filed.

The end state is the only architecture that has ever produced an untouchable consumer finance franchise – a payments network attached to a deposit-funded bank.

We are not formally recommending Affirm – but it is one of our highest-conviction Emerging Lindys. The brand promise, the world-class partnerships, and the two-sided network make it the closest thing we have seen to a young American Express – a Porter classic, and an all-time Lindy. Amex has compounded for 176 years. Visa’s rails have run for nearly 70. Affirm has what took them generations to build – both sides of the network, a brand built on trust, and a founder 14 years into a 30-year mission.

Levchin remains the largest individual shareholder, and his compensation is almost entirely a multi-year award of performance options that vest only at stock price hurdles climbing as high as $372 per share. And with the network finally paying for itself, he is free to finish what he started – reorienting the entire credit ecosystem around the people who actually use it.

Porter & Co.
Stevenson, Maryland

The post The Next Lindy Payments Network appeared first on Porter & Co..

  •  

Following The Smart Money In Q2

In today’s Sunday Stock Screen, we’re “Following The Smart Money” by looking closely at the 13F filings from Wall Street’s top money managers.

And in today’s Sunday Selection, we report on a dominant retail company whose margins are vanishing – the crowd sees deterioration, but the world’s top fund managers see an empire spending today’s profits to own the next decade

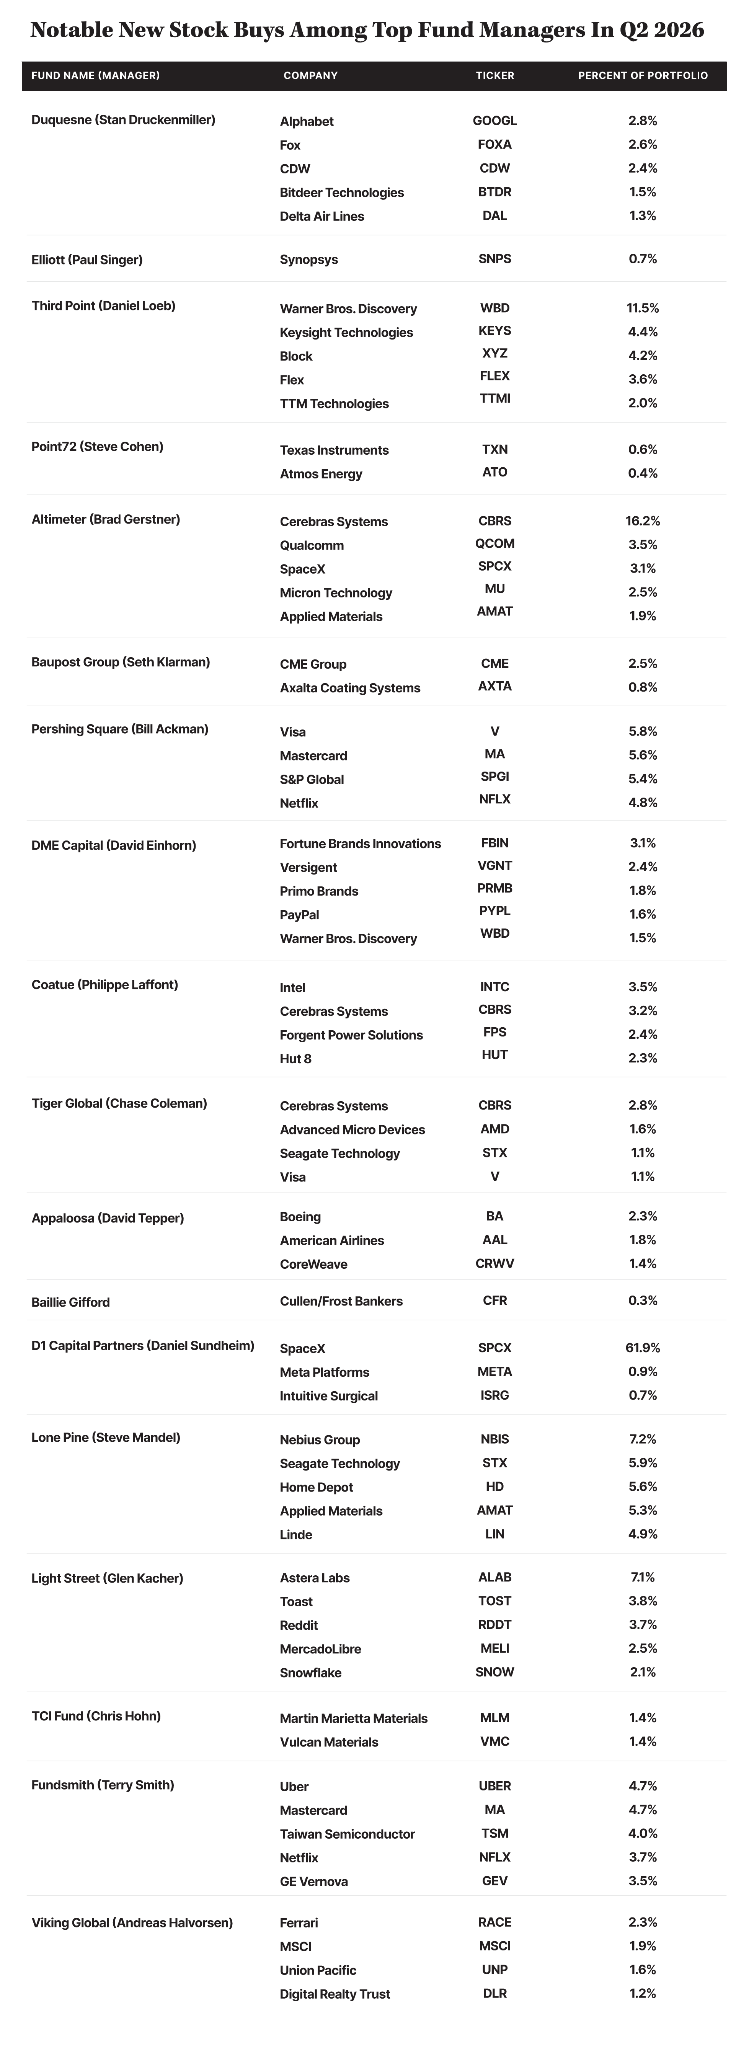
In the tables below, we show the latest (Q2 2026) new stock buys – as reported in their most recent 13F filings with the Securities And Exchange Commission – of some of our favorite fund managers. We also show what percentage each stock makes up within each fund’s investment portfolio.
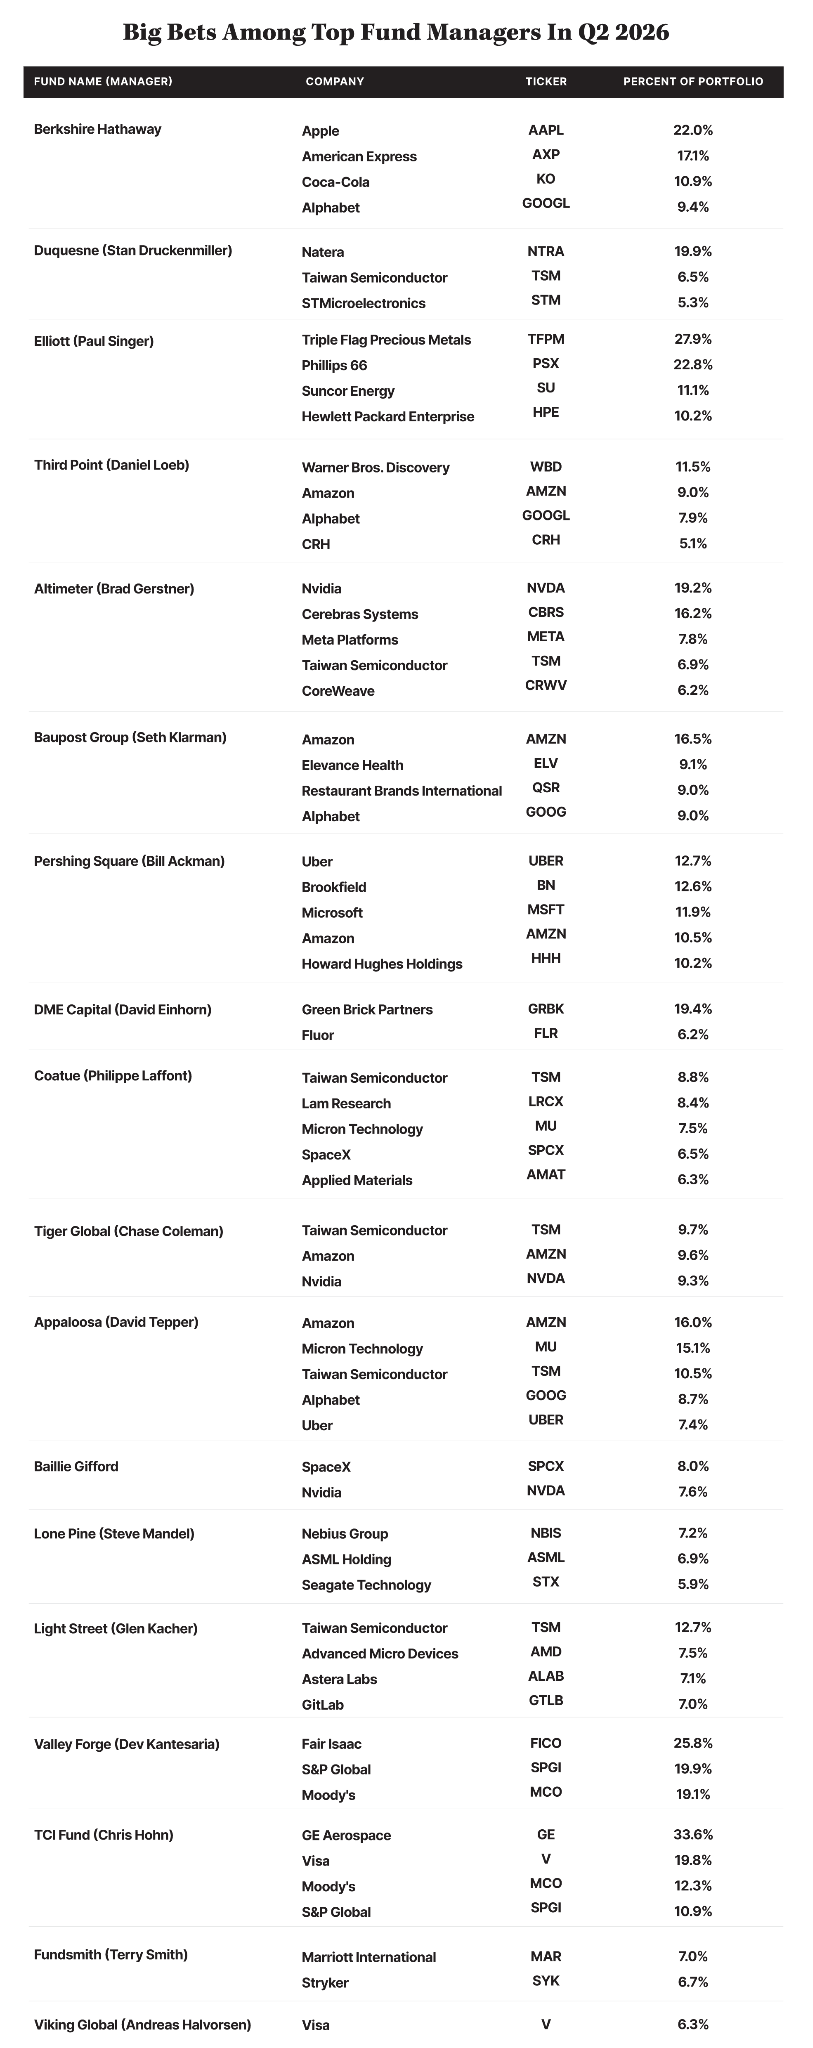
In addition to tracking new purchases, we pay attention to any “big bets” these asset managers make – comprising at least 5% of the portfolio.
⚙ Edit 🗑 Delete

(Several of the companies on the two lists above are also recommended stocks in Porter Stansberry’s Complete Investor… to learn more about joining Complete Investor – and find out which stock those are, and why we recommended them – go here.)

Highs And Lows

Each week, we also monitor any stocks in the market making a new 52-week high. We do this because any stock on its way to generating 2x, 3x, or 10x returns will spend a lot of time making 52-week highs along the way. Thus the new 52-week-high list provides an opportunity to flag these potential high performers before they really break out, with a particular emphasis on lower-profile, less widely-followed stocks that might have otherwise gone unnoticed.

Notable stocks making a new 52-week high this week:

  • Eli Lilly (LLY)

  • JP Morgan Chase (JPM)

  • Visa (V)

  • Johnson & Johnson (JNJ)

  • AbbVie (ABBV)

  • Coca-Cola (KO)

  • Merck (MRK)

  • Amgen (AMGN)

  • Thermo Fisher Scientific (TMO)

  • Charles Schwab (SCHW)

  • Union Pacific (UNP)

  • ConocoPhillips (COP)

  • Pfizer (PFE)

  • Vertex Pharmaceuticals (VRTX)

  • Bristol-Myers Squibb (BMY)

  • Airbnb (ABNB)

  • General Dynamics (GD)

  • Marathon Petroleum (MPC)

  • Valero Energy (VLO)

  • Phillips 66 (PSX)

  • 3M Company (MMM)

  • Regeneron Pharmaceuticals (REGN)


How to Profit From”The SpaceX Supercycle”

Act Before August 26

According to legendary tech investor Jeff Brown…

Three words on page 37 of the SpaceX IPO filing…

Signal Musk is about to trigger a rare wealth supercycle…

And send billions into a sector nobody associates with tech.
Click Here Now To Watch His Urgent Strategy Session

Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Brownstone is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.


We also monitor stocks on the new 52-week-low list. In many cases, the names on this list are there for good reason – the market is often correctly pricing in their weak fundamentals. However, once in a while, a great business with excellent long-term prospects finds itself on this list due to a temporary setback. This can create the rare opportunity to buy top-shelf merchandise at bargain-basement prices.

Notable stocks making a new 52-week low last week:

  • AppLovin (APP)

  • CRH plc (CRH)

  • AutoZone (AZO)

  • Medline (MDLN)

  • Public Service Enterprise Group (PEG)

  • Kroger (KR)

  • Martin Marietta Materials (MLM)

  • FedEx Freight Holding (FDXF)

  • Rollins (ROL)

  • Lennox International (LII)

  • JBT Marel (JBTM)

  • Brookfield Business (BBUC)

  • Icahn Enterprises (IEP)

  • Liftoff Mobile (LFTO)

  • PagSeguro Digital (PAGS)

  • StoneCo (STNE)

Today’s Sunday Selection comes off one of our “Following The Smart Money” screens – and it is one of the most dominant online retailers in the world. Two weeks ago, it reported its fastest quarterly revenue growth in four years – crossing $10 billion for the first time in its history, up 50% year over year (“YOY”), while adding 18 million new customers in 12 months.

Yet the shares sit roughly 25% below their 52-week high as the market is fixated on margins. The company is in the middle of a deliberate investment cycle – spending today’s profits to extend its lead across an entire continent – and the market is punishing the stock for it. Yet the world’s top fund managers were buying while the market complained. We have seen this movie before, from this company: the last time it invested this heavily, the bears insisted it would never earn consistent profits, its margins went on to set record after record, and the stock compounded several times over for investors who bought at the trough.

We believe a similar moment is approaching, making this a strong candidate for the Complete Investor recommendation list.

⚙ Edit 🗑 Delete

(To become a Partner Pass member, contact our Customer Care team at 888-610-8895, internationally at +1 443-815-4447, or via email at support@porterandcompanyresearch.com.)

The company is MercadoLibre (Nasdaq: MELI) – the Amazon (AMZN), PayPal (PYPL), and Shopify (SHOP) of Latin America rolled into a single business. Calling MercadoLibre an online retailer understates it the way calling Amazon a bookstore did in 2005. Founded in Buenos Aires in 1999 and listed on Nasdaq since 2007, the company operates across 18 countries through three interlocking businesses.

The marketplace, MercadoLibre, is the dominant e-commerce platform in Latin America – roughly 35% share in Brazil (more than double Amazon), 68% in home-market Argentina, and a strong second position in Mexico. It served 89 million unique buyers last quarter, with gross merchandise volume (“GMV”) up 36% YOY on a currency-neutral basis, and generated $16.3 billion of revenue in 2025 – 56% of the total.

The fintech arm, Mercado Pago, began as a checkout tool and is now one of Latin America’s largest financial platforms – digital wallet, merchant acquiring, asset management, and, increasingly, credit. Total payment volume passed $100 billion last quarter, 88 million people use Pago monthly, and in Brazil it is the most-used wallet after the government’s own Pix system. This fintech arm generated $12.6 billion of revenue in 2025, or 44% of the total. Within it, credit revenue reached $5.9 billion, up 63% in a year, on a $16.4 billion loan book growing 75% with non-performing loans near historical lows and net interest margins widening.

The logistics network, Mercado Envios, is what makes the marketplace credible: fulfillment centers, more than 10,000 drop-off points, and the fastest delivery network in the region, moving roughly three-quarters of fast shipments within 48 hours. Unit shipping costs in Brazil fell 17% last year even as volumes surged – scale economics working as designed.

Each business feeds the others. Shoppers adopt the wallet, wallet users get offered credit, credit makes shoppers buy more, and sellers fund advertising to reach them. Users active in both commerce and fintech grew 37% last quarter – faster than either side alone – and management says these dual-ecosystem users are multiples more profitable than single-platform users. That is the MercadoLibre flywheel.

The flywheel has driven revenue nearly vertical: $15.1 billion in 2023, $20.8 billion in 2024, and $28.9 billion in 2025. The profit line tells a different story, and it is the part the market keeps focusing on. MercadoLibre runs in deliberate investment cycles. When management sees an opening, it spends through the income statement to seize it – growth accelerates and margins compress. Then the investments mature and the profits arrive.

The company has completed this loop once at full scale. From 2016 to 2019, it transformed from a high-margin marketplace into an integrated commerce, logistics, and payments ecosystem – and paid for it with profits. Operating margin went from 21.4% in 2016 to negative 6.7% in 2019 while bears insisted the company would never earn consistent profits. Then margins recovered to a record 14.6% – on revenue that had grown 10-fold from its 2018 level – and the market capitalization went from $13 billion at the end of 2018 to $84 billion by the end of 2020, a more than six-fold increase in two years.

Here is the detail that matters most for timing: the stock rose 92% in 2019 – nearly 3x the Nasdaq’s gain in a year when falling rates lifted everything. The market did not wait for the margin inflection to appear in the headlines. It re-rated the stock as soon as the evidence showed the spending was changing customer behavior and would eventually monetize. By the time reported margins recovered, the easy money had been made.
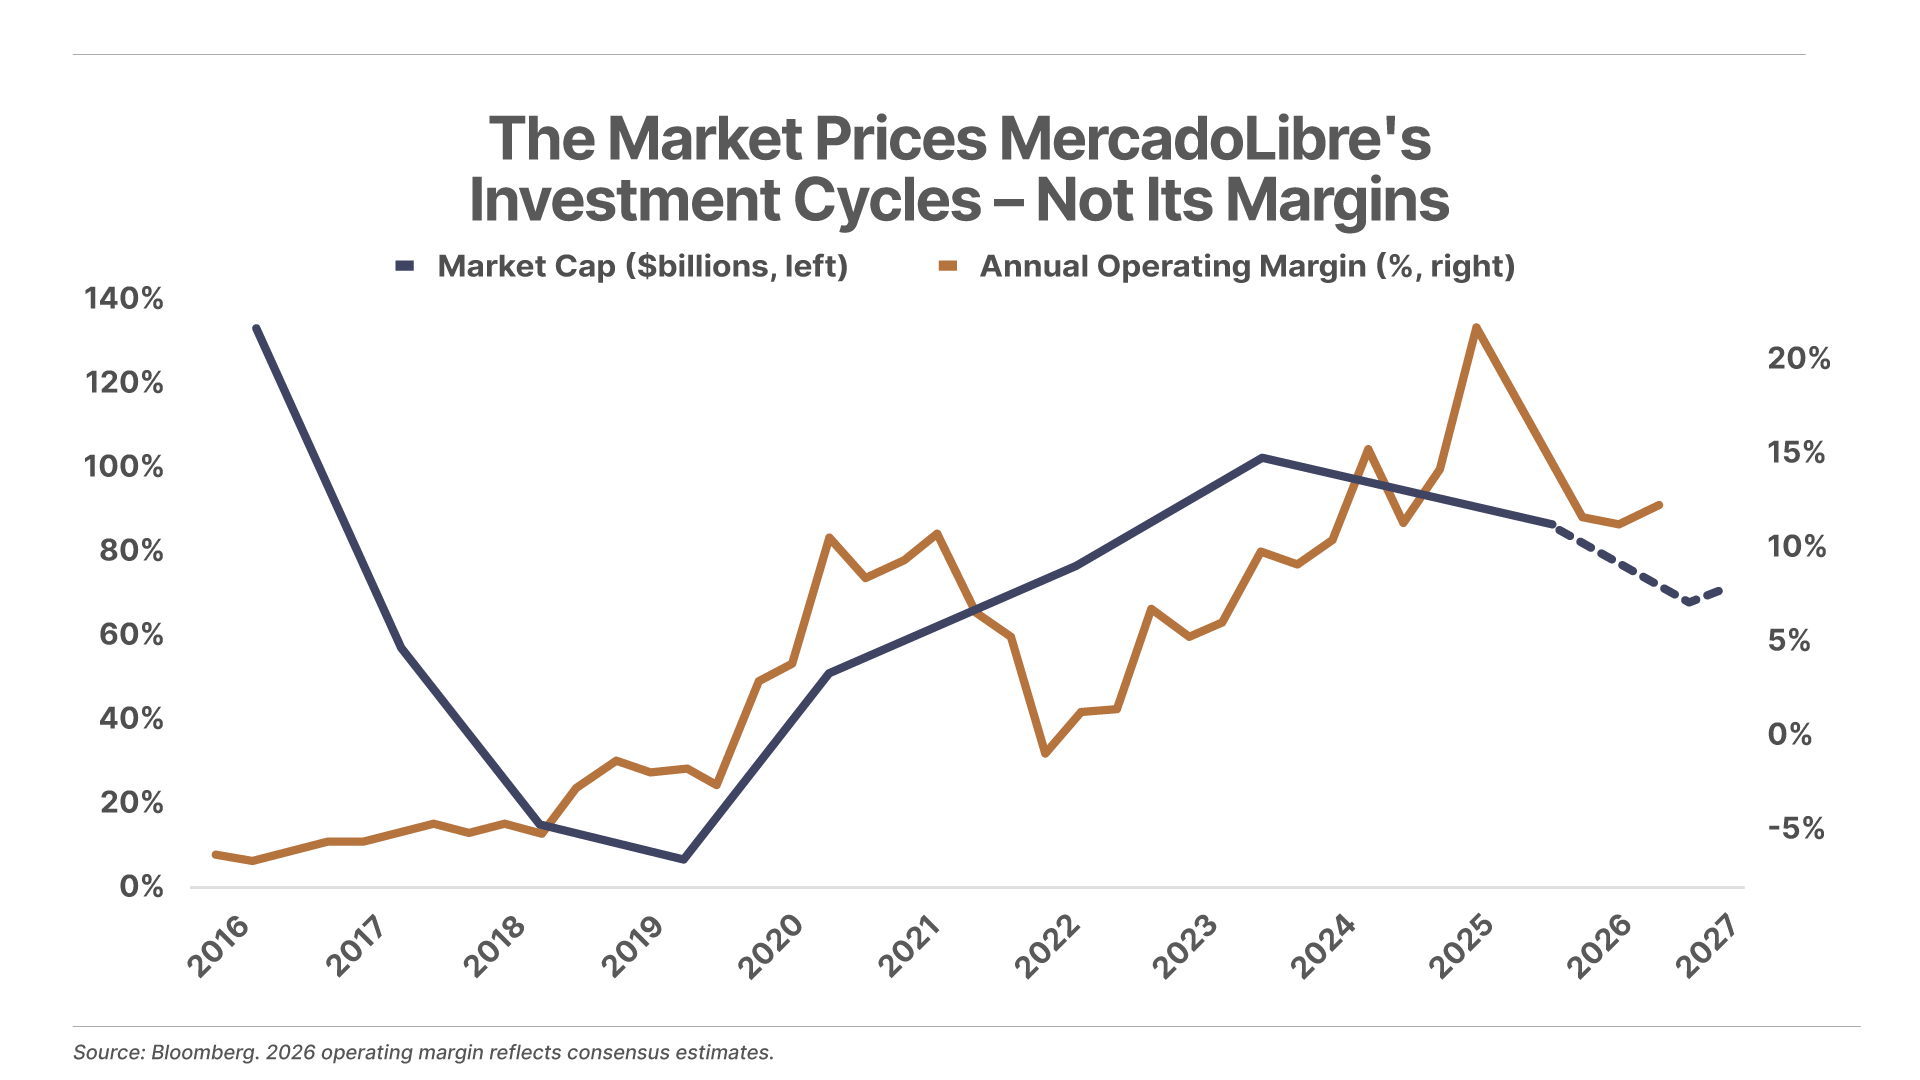
The 2021-2022 drawdown is the counterexample that sharpens the rule: margins improved steadily and the stock still fell more than 65% peak-to-trough as rising rates crushed growth multiples. The market prices the expected return on MercadoLibre’s investments – margins are one signal within that judgment, and often a lagging one.

Today’s cycle is the broadest yet, and the result is the paradox in last quarter’s report – revenue up 50%, operating margin down about 50% (at 6.7% versus 12.2% a year ago). And the early evidence looks like 2019: conversion, purchase frequency, retention, and category breadth are all rising.

What has not happened yet is the payoff. By our math, the realized incremental return on the roughly $9 billion to$13 billion deployed in this cycle so far is only about 2% to 3% – versus the mid-teens-to-30%-plus returns the prior cycles eventually earned. That gap is the current opportunity.

The segment data makes the strategy legible: Argentina is the fortress that funds the wars, Brazil is the battleground, Mexico is the contested frontier, and everything else is seed corn for the next cycle.

Argentina generated $6.0 billion of 2025 revenue (21% of the total), up 56%, and more than $2.5 billion of direct contribution profit – more than Brazil, on 40% of Brazil’s revenue. With 68% market share and a fintech-heavy mix, it is a monopoly tollbooth earning a contribution margin above 40%, with enormous macro torque as credit strengthens under Argentina’s normalization.

Brazil, at $15.2 billion of revenue (53%), up 33%, is where the money is going. Direct contribution profit fell from $2.3 billion to $2.1 billion in 2025 even as revenue grew by $3.8 billion – each incremental dollar of Brazil revenue arrived with slightly more than a dollar of direct costs attached. The engagement response has been immediate: items sold up 56% last quarter, items per buyer up 19%, and conversion up 1.1 points.

Mexico, at $6.5 billion of revenue (22%), up 39%, is the one major market where Amazon leads – roughly 40% to 30% share – and the capital allocation shows how seriously it believes in this opportunity. Mexico’s gross property and equipment now nearly equals Brazil’s on only 40% of the revenue, while the segment still earns an 18% contribution margin.

The remaining markets – Chile, Colombia, Peru, and Uruguay – produced $1.3 billion of revenue (4%), up 41%.

Three levers drive the next leg of growth. Credit is the largest and MercadoLibre is well positioned with years of granular purchase data no bank can see, formal credit penetration in Latin America still a fraction of developed-market levels, and mature non-card lending that is highly profitable today. Advertising is the highest-margin opportunity: Mercado Ads grew 62% last quarter and now exceeds 10% of Latin American digital advertising. And AI is quietly deflating the cost base: the majority of the company’s code is now AI-written, product development fell from 8.4% to 7.2% of revenue, and customer service headcount dropped from 10,000 to 7,000 while the business tripled.

The credit book is the real risk. This cycle is far more credit- and balance-sheet-intensive than 2016–2019, and credit metrics always look best right before they do not. Competition is intensifying, currency remains a permanent tax on reported results, and the valuation – nearly 50x trailing earnings – is cheap only against the stock’s own history. And unlike 2019, there is no help from lower rates – long yields are moving higher globally, so the re-rating must be carried by the operating evidence alone.

The stock sits roughly 25% below its June 2025 high while revenue grows 50%. And the multiple is measured against earnings the company is deliberately suppressing – so the 50x trailing earnings overstates what investors are paying for the underlying earning power. If revenue reaches $50 billion and margins recover merely to 10% to 12%, operating profit climbs toward $5 billion – meaning today’s roughly $95 billion market capitalization is paying about 20x that earning power, for a business still compounding revenue at more than 20% a year.

Management has spent 27 years proving it knows how to allocate capital across a reinvestment runway that is nowhere near exhausted. History says the stock will not wait for the evidence to be complete – which is what makes MercadoLibre a strong candidate for the Complete Investor recommendation list… but not yet.

Porter & Co.
Stevenson, Maryland

The post Following The Smart Money In Q2 appeared first on Porter & Co..

  •  
❌