❌

Reading view

Follow The Flow Of Money

Issue#143, Volume#3

⚙ Edit 🗑 Delete
⚙ Edit 🗑 Delete

For Those Who Aren’t Careful, It’s Total Amputation Without Anesthetics


Editor’s note: Today’s the final essay in a multi-part series on how the massive spending into the AI buildout will play out over the economy and for the companies involved. Please see the first essay here, the second essay here, the third essay here, the fourth essay here, and the fifth essay here.

Here’s Porter now…


How do I know the funding and the buildout won’t continue? Because this entire bubble was never about technology. The bubble around the artificial intelligence (“AI”) buildout was caused, like all financial bubbles, by a corruption of the money supply.

The railroad boom of 1865-1873 was fueled by the paper money of the Civil War. The telecom bubble of 2000 was fueled by the Federal Reserve’s response to the Russian default and fears about Y2K. And, of course, the mortgage bubble of 2008 was fueled by the Fed’s aggressive response to 9/11 and the “War on Terror.”

The AI bubble is a direct result of the Federal Reserve’s response to COVID. Our central bank created an unimaginable amount of new money – roughly $7 trillion.

By late 2021, the money market funds that received most of this cash couldn’t find enough safe, short-term places to put it. So the Fed opened up what amounts to a giant parking lot for cash. It’s called the reverse repo facility (“RRP”).

Don’t let the jargon fool you. This is simply the government printing money and handing it out to favored financial institutions.

Technically, it works by a money market fund depositing its cash to the Fed overnight. (Note: there’s no reason the Fed, which can create as much cash as it wants, would ever need to borrow money from a money market fund.) The Fed then gives the fund a Treasury security as collateral for the night. The next morning the Fed gives the cash back plus a tiny amount of interest. It’s called “reverse repo” because from the Fed’s point of view it’s the reverse of a normal repo – the Fed is borrowing the cash rather than lending it. Once again – as with neocloud, which I wrote about on Monday – when something is called a made-up word that has no actual meaning in the English language, beware.

With the Fed handing out money for nothing, it was no surprise that the RRP “parking lot” filled up fast. At its peak in December 2022, the RRP held about $2.5 trillion in money market fund cash.

And that money is what has been powering the entire AI bubble.

Let me show you what happened.

Early in 2023, the interest rate on Treasury bills rose above the rate the Fed was paying on RRP cash. That happened because the Fed was responding, finally, to the massive inflation their policies and the government’s massive deficits had caused.

Money market funds are legally required to seek the best safe yield they can, so as interest rates rose, they pulled cash out of the RRP and bought T-bills instead. This happened continuously from mid-2023 through October 2025. Roughly $3 trillion of cash came out of the RRP over that period – from $2.5 trillion at peak down to essentially zero by October 2025.

As you’ll see below, what happened to this capital as it entered the private financial system is complicated. But all you have to know is that from mid-2023 until last October, trillions in capital flooded into our financial system. And that’s what’s driven equity valuations higher and higher, and that’s what’s funded the entire AI buildout.

The key thing to know is this: that money is now all spent.

Our private financial system works primarily on two tiers. Money market funds (when they can’t get a completely free ride from the Fed) lend cash to primary dealers (the biggest banks). The primary dealers relend cash to everybody else: hedge funds, private credit funds, real estate financing vehicles, and increasingly, the AI-capex financing engine.

When the RRP started draining in 2023, the money that came out went into T-bills at first. But it didn’t stay there. Through private repo lending, it funded the primary dealers (the big banks). And because the big banks now had an enormous amount of cheap short-term cash coming in, they lent out more and more to non-bank borrowers. Why? Because trillions in capital had to land somewhere in only about two years.

Non-bank is finance jargon for any lender or credit institution that isn’t a chartered bank. It includes hedge funds, private credit funds, private equity firms, mortgage lenders that aren’t banks, insurance companies, pension funds, real estate investment trusts, business development companies, structured product vehicles, and so on.

Collectively, they are called the “shadow banking system” because they perform banking functions – they extend credit – but they don’t take insured deposits and don’t have direct access to the Federal Reserve’s liquidity facilities.

The shadow banking system has grown enormously over the last 15 years. It’s where most private credit lending lives – Blue Owl Capital (OWL), Apollo Global Management (APO), Ares Management (ARES), Blackstone (BX), and KKR (KKR). It’s also where most of the AI-capex financing sits. Not the equity – that’s on the hyperscalers’ balance sheets – but the debt behind the data centers, purchases of the high-speed GPU chips, and neocloud operators. That financing gets warehoused in the shadow banking system and eventually distributed as securitized paper, which, hey, why not, Moody’s says it’s AAA!

The shadow banking system funds itself largely through repo. It borrows short-term cash from the primary dealers, secured by whatever collateral it holds – Treasuries for the most part, but also mortgage bonds, corporate loans, structured products rated AAA. That’s what’s so valuable about that Moody’s rating.

As a result, from mid-2023 through October 2025, both sides of the plumbing grew at the same time.

The primary dealers’ repo funding grew because money market funds pushed more and more cash into it as they pulled out of the RRP. Non-bank lending grew because the primary dealers, flush with all that new cheap cash, extended it out to the shadow banking system, which used it to fund private credit, hedge fund leverage, and – most importantly for our purposes – the entire ecosystem of data center loans, GPU-backed term loans, and neocloud financings.

Both grew because the same exogenous force – the RRP draining – was pushing money into both simultaneously. It looked like the private credit system was generating its own growth out of business demand. It wasn’t. It was being lifted from underneath by the parking lot emptying.

By October 2025, the RRP was effectively empty. The parking lot was drained. The COVID “credit card” was tapped out.

From that point on, the financial system became zero-sum. Any new dollar of primary-dealer repo funding has to come from somewhere else in the system. It can’t come from the RRP anymore because the RRP is empty.

Money market funds have a finite amount of cash to lend. If they lend more of it to primary dealers in repo, they have less to lend elsewhere. And the primary dealers, if they want to keep their own repo books growing, have to pay higher interest rates to attract that cash. Higher repo rates raise the shadow banking system’s funding cost. Higher funding costs mean the shadow banking system can either extend less credit or charge borrowers more.

The mechanical result: if primary dealer repo grows, non-bank lending shrinks by approximately the same amount. The two lines that had been rising together for three years – bank repo and non-bank credit – now move inversely.

That’s what’s happening. The correlation flipped in October 2025 and has stayed flipped. Repo went from a rising tide that lifted both dealer and shadow-bank balance sheets to a zero-sum competition between them.

Nvidia (NVDA) saw this coming and raised $25 billion to survive what’s about to happen. CoreWeave’s (CRWV) most recent financing tanked because of the impact of a zero-sum financial world.

Shadow banking is being squeezed. The most-leveraged, weakest-collateral, most-concentrated shadow bank borrower – a neocloud with GPU collateral serving AI customers – gets repriced first.

But this is only the beginning.

The two-year Treasury to Fed Funds interest rate spread sits at +50 basis points – the same level reached in the second halves of 2001, 2008, and 2021. Emerging-market inflows just posted one of the largest sudden stops on record. Real U.S. personal income is falling at recession pace. Year-to-date household-survey employment losses exceed both 2001 and 2008. Prime-age labor-force dropouts are at ex-COVID records. Except for mortgages, credit delinquency rates are at crisis highs.

What ends a capex boom? It eventually runs out of money.

Jesse Livermore described what happens when a capex boom runs out of money in Edward Lefevre’s book Reminiscences Of A Stock Operator.

Finally there came the awful day of reckoning for the bulls and the optimists and the wishful thinkers and those vast hordes that, dreading the pain of small loss at the beginning, were now about to suffer total amputation – without anesthetics. A day I shall never forget, October 24, 1907… No money anywhere, and you can’t liquidate stocks because there is nobody to buy them. The whole Street is broke at this very moment.

Livermore made $1 million on that day. He saw his signal to start shorting when the railroads began advertising equity offerings that had earlier and earlier execution dates and accepted payment in installments.

He recognized a death struggle for capital.

Will you?

Tell us what you think of today’s Daily Journal:porterstansberrydirect@gmail.com

Good investing,

F. Porter Stansberry
Stevenson, Maryland


⚙ Edit 🗑 Delete


⚙ Edit 🗑 Delete

Presented By: Porter & Co.


3 Things To Know Before We Go…

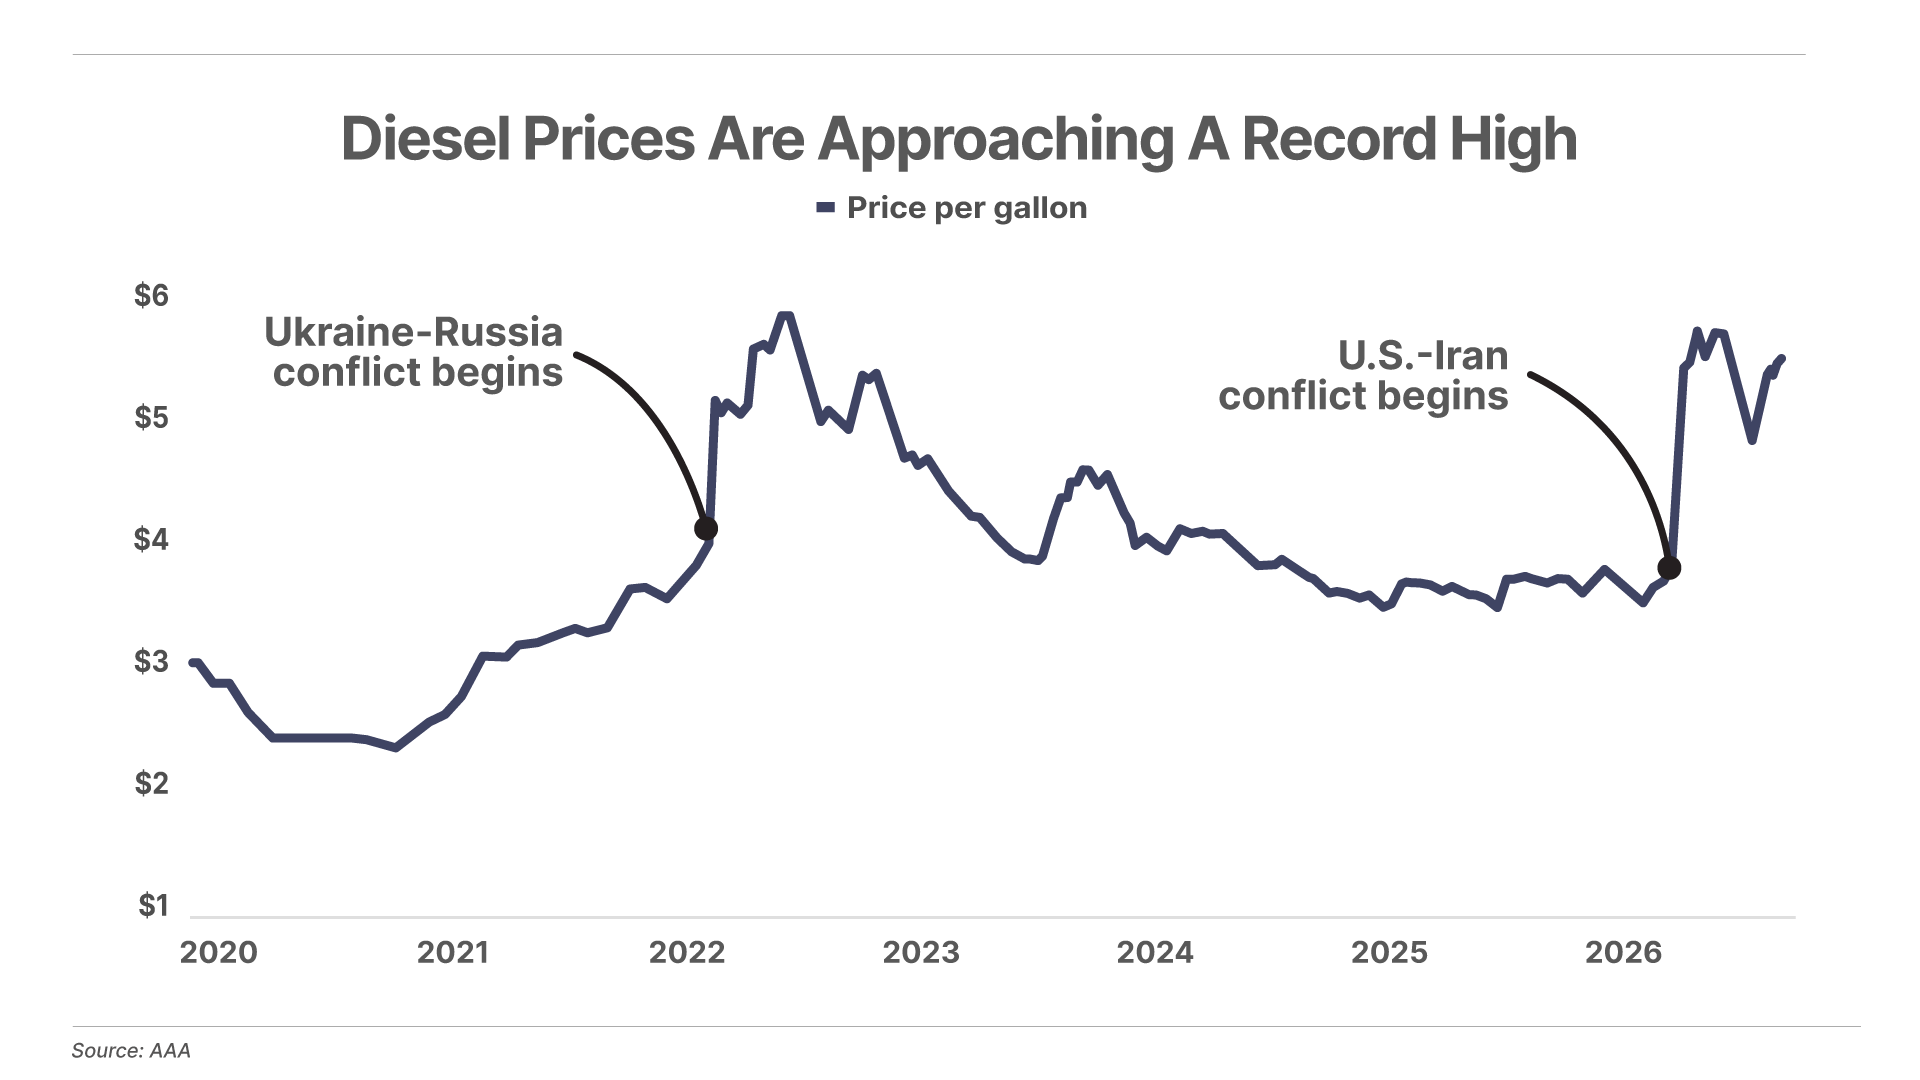
1. Diesel prices are surging. The pump price hit $5.47 a gallon Tuesday, up 8% in a month and just 35 cents below the June 2022 record, as the Iran war and Ukrainian drone strikes on Russian refineries pull supply offline. The premium diesel commands over crude – the refiner’s margin – hit a record $100 a barrel, triple last year’s average. Farmers, truckers, and heating-oil buyers have no substitute.

2. The cockroaches are coming for private credit. Loans on non-accrual status – meaning the borrower has stopped paying or is about to – hit 2.8% at the 20 largest publicly traded private-credit firms in Q2, the highest level in a decade. The riskiest lending migrated into the $2 trillion private-credit channel where nothing gets marked until someone is forced to mark it. Now the marks are being forced. Major funds are taking writedowns and selling loans at discounts. First came the redemption gates – investors trying to get out. Now come the non-accruals – borrowers failing to pay.

3. Three times as many stocks are hitting one-year lows as one-year highs. On Tuesday, 173 securities listed on the New York Stock Exchange closed at their lowest price in 52 weeks, versus just 57 closing at their highest. The S&P 500 finished the same session 1.4% below the record close it set on August 13. In the 15 prior cases since 1928 when the S&P 500 sat within a week and 2% of a record high while new lows ran three times new highs, the index averaged a 2.8% loss over the following 12 months and finished higher only a third of the time. At their worst point during those years, stocks were down an average of 16%.


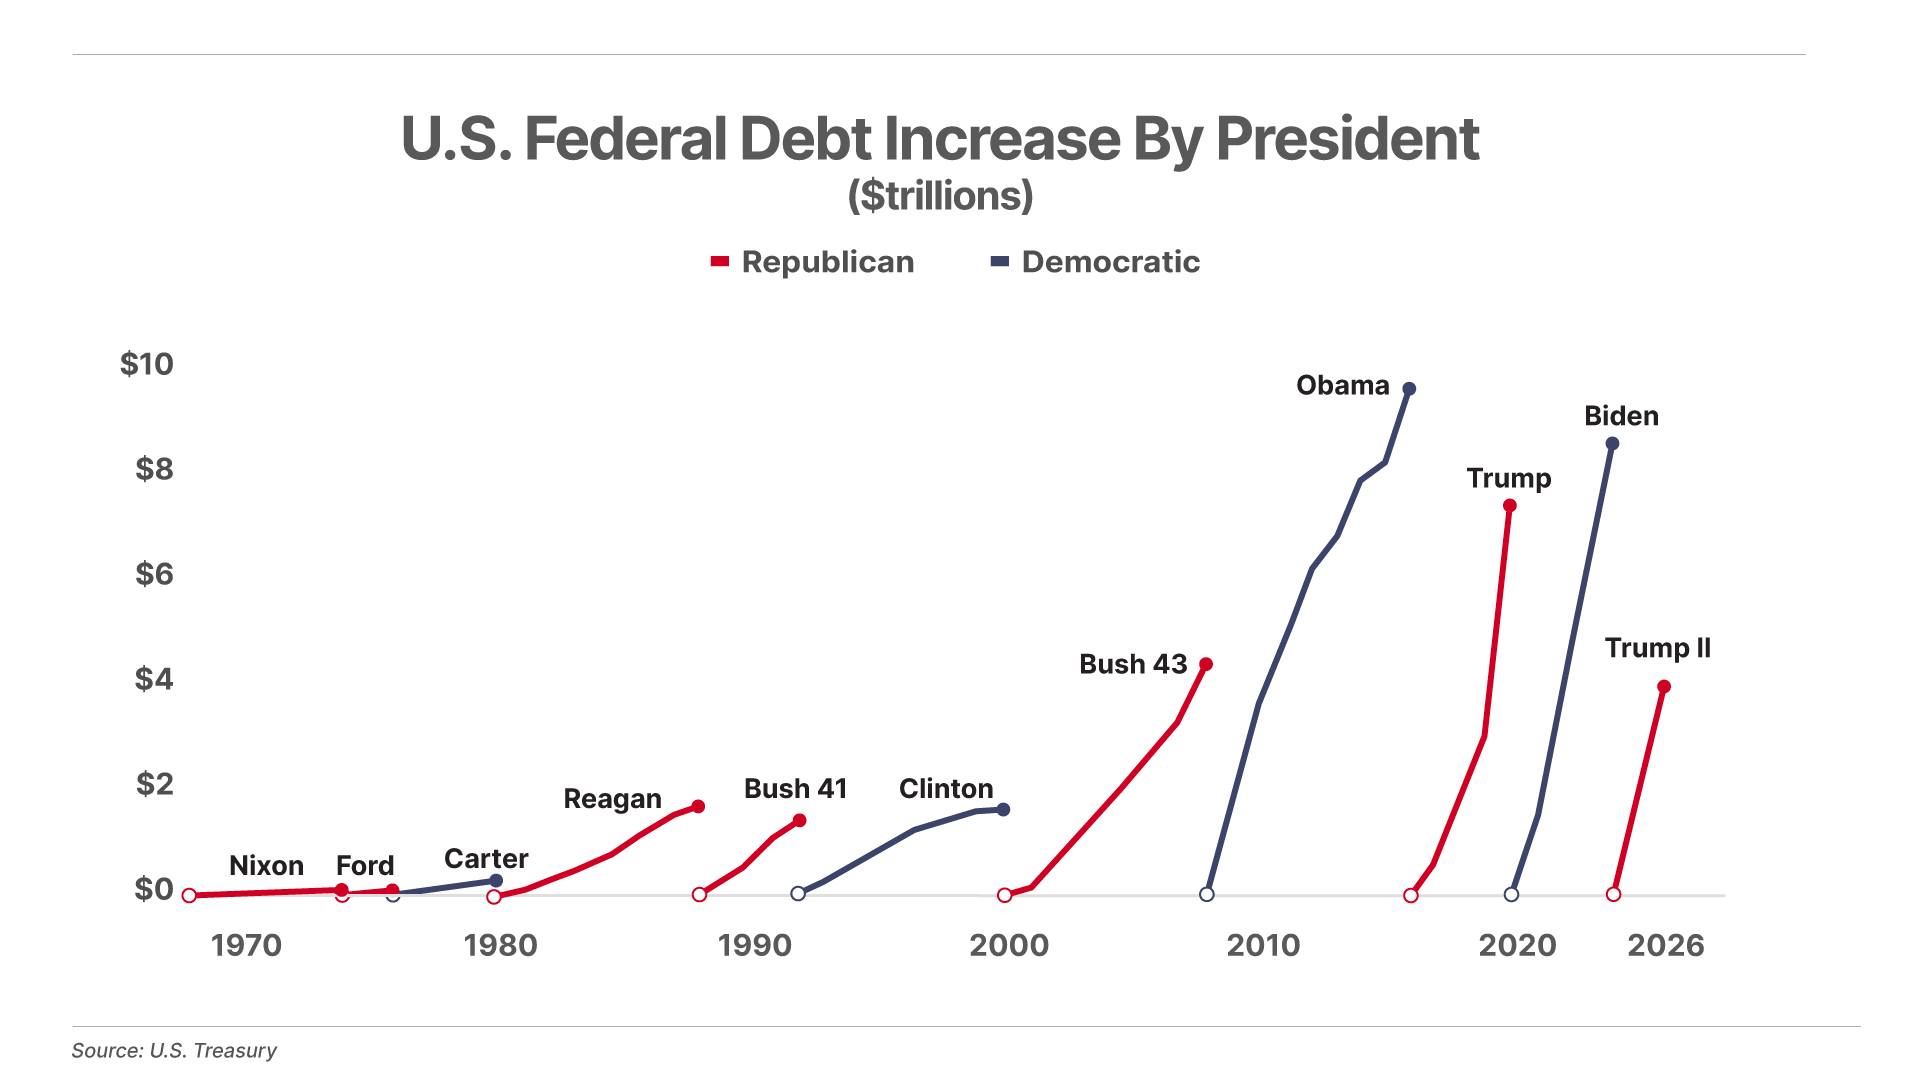
Chart Of The Day… Presidential Debt

Federal debt crossed $40 trillion this week. Nearly three-quarters of that total was added by just four presidents: Bush 43 (+$4.4 trillion), Obama (+$9.6 trillion), Trump’s first term (+$7.4 trillion), and Biden (+$8.3 trillion). Two Democrats, two Republicans – and Trump’s second term has added roughly $4 trillion more in just 19 months. Both parties are responsible for our debt crisis.

Mailbag

In yesterday’s Daily Journal, Porter reported that the entire artificial-intelligence bubble will depend on credit by the end of this year…

“A Better Investor”

James B. writes:

Porter,

Enjoyed your essay, and I’m glad I got out of Hut 8 (HUT) and IREN (IREN) back in May.

I bought heavily into both in April 2025, knowing at the time it was a high-risk move. I knew I was playing with fire, so I sold out in May of this year.

It helps to be a little older and wiser and to recognize that it wasn’t necessarily because I was smart – I just got lucky and ended up on the right side of the trade. The timing happened to work in my favor. Years ago, I would have thought it was because I was brilliant and kept buying more.

Appreciate your work, Porter. You’re making me a better investor.


Pat B. writes:

Excellent analysis!


“Sick And Tired”

Jeff H. writes:

I am sick and tired of this “privatize the profits, socialize the losses” cycle. The ratings agencies are absolute crooks and investors who believe in their ratings are fools.

Thank you for the excellent analysis and writing.


Andy S. writes:

Unfortunately you are correct. I am trying to figure out how to protect my assets!


Porter & Co. Market Snapshot

Price Yesterday’s Return Year-to-Date Return
S&P 500 Index $7,691.76 -0.69% 13.2%
Gold per ounce $4,366.00 -1.85% 1.1%
Bitcoin $64,680.71 0.31% -26.5%
Oil (West Texas Intermediate) per barrel $84.94 -0.05% 49.2%
Berkshire Hathaway (BRK) $753,600.00 0.83% -0.2%
Porter’s Permanent Portfolio – 0.17% 2.1%
The Better Than Berkshire Index – 1.07% 10.5%
Total Return Annual Return
Porter & Co’s Top Ranked* 34.8% 16.2%
Yield Yesterday’s Change Change
Year-to-Date
U.S Treasury 30-Year Yield 5.28% -2 bps 46 bps
Prices as of 4:00 pm ET August 18, 2026 | bps = basis points (or 0.01%)
*A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


Porter & Co. Top Positions

Publication Ticker Description Total Return
Biotechnology QURE uniQure 237%
Biotechnology SGMT Sagimet Biosciences 197%
Complete Investor BWXT BWX Technologies 191%
Biotechnology NUVB Nuvation Bio 174%
Biotechnology ROIV Roivant Sciences 165%
Biotechnology TGTX TG Therapeutics 142%
Complete Investor BTC/USD Bitcoin 139%
Complete Investor SKWD Skyward Specialty Insurance 137%
Complete Investor PM Philip Morris 133%
Biotechnology SGMT Sagimet Biosciences 131%
Prices as of 4:00 pm ET August 18, 2026

Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

The post Follow The Flow Of Money appeared first on Porter & Co..

  •  

No More Repo Facility = No More Free Money

Issue#142, Volume#3

⚙ Edit 🗑 Delete
⚙ Edit 🗑 Delete


Why There’s No More Cheap Capital For AI


Today is Porter’s fifth essay in a multi-part series about the enormous financial risks of the ongoing artificial intelligence (“AI”) bubble. Please see the first essay here, the second essay here, the third essay here, and the fourth essay here.


Hyperscaler free cash flow is on track to fall roughly 50% from its late-2024 peak through early 2026, and to turn negative for the first time in 2027.

That means the entire bubble will depend on credit by the end of this year.

Microsoft (MSFT), Alphabet (GOOG), Amazon (AMZN), Meta (META), and Oracle (ORCL) have added roughly $350 billion of on-balance-sheet debt in five years, plus $1.1 trillion of off-balance-sheet data-center lease commitments and GPU supply deals – $1.65 trillion of hidden obligations across five names.

Morgan Stanley estimates the sector faces a $1.5 trillion external financing gap against $2.9 trillion of capex through 2028.

Where will the money come from…? Some of it will come from Nvidia’s (NVDA) new $500 billion credit fund. And even more will come from the public.

Pay attention: This is where the artificial intelligence (“AI”) buildout goes from something that will threaten tech companies to something that will threaten our entire banking system and our entire economy.

Banks, ever ready to package dodgy debt for other people to hold, have begun operation “AI bag holder.”

Outstanding data-center debt securitization issuance grew from $4 billion in 2020 to $61 billion year-to-date 2026. Barclays projects $180 billion in securitizations by year-end 2028 (!).

How will so much AI data-center debt possibly be sold to investors? By regulatory arbitrage of course! How do you make dodgy debt attractive to the financial system? By “proving” to the regulators that it’s risk-free.

On February 11, 2026, $500 million of Compass Datacenters’ $830 million asset-backed security (“ABS”) became the first data-center securitization rated AAA by Moody’s. Pricing: +120 basis points over Treasuries.

Keep in mind, Moody’s only began rating the sector in September 2025.

Thus, on a credit channel that’s scaled 15x in six years, using a rating methodology that’s about a year old, Moody’s delivered its first AAA rating just as the bubble reaches its zenith.

Where have we seen this before? The AAA-rated collateralized debt obligation (“CDO”) of the AI era is here!

And regulators just gave the AI credit machine the same free pass that created the entire mortgage fraud bubble. On July 29, 2026 – the same day CoreWeave (see Friday’s Journal) paid an extra 125 basis points to force through its loans backed by fast-processing GPU chips – the Securities And Exchange Commission’s (“SEC”) Office of Structured Finance sent a letter to Latham & Watkins – the law firm representing the case – that will move a trillion dollars of debt.

The staff wrote:

Based on the representations in your letter, we agree that the fixed-income or other securities issued in data center securitizations of the type described in your letter are not asset-backed securities as defined in section 3(a)(79) of the Securities Exchange Act of 1934.

Translation: AI debt isn’t an ABS. So the rules Congress and the SEC wrote after 2008 specifically to prevent another AAA-rated credit blowup do not apply.

Regulation RR’s 5% risk retention – the Dodd-Frank rule (a federal law passed in 2010 to prevent another Global Financial Crisis) that was supposed to force the sponsor of a securitization to keep skin in the game – gone. Regulation AB’s loan-level disclosures – gone. Rule 192’s prohibition on conflicts of interest, the one written to stop the Abacus-style short-your-own-deal trades – gone. Rule 15Ga-2’s pre-sale disclosure of third-party due diligence findings – gone.

The $200 billion of data-center debt Barclays expects to be sold by 2028 will move without any of these investor protections. Put that together with the Moody’s AAA rating and you’ve got the makings of an epic financial bubble – and collapse.

The rating agency that stamped AAA on subprime CDOs is back with a rating methodology less than a year old, on a market that grew 15-fold in six years, issuing AAA on paper the SEC has just exempted from the risk-retention, disclosure, and conflict-of-interest rules that were written to prevent exactly this. This is not a bug in the system. This is the system moving $1 trillion of AI credit onto insurance-company, pension-fund, and bank balance sheets by pretending the risk isn’t there.

History rhymes because leverage rhymes.

Jay Cooke & Company financed the Northern Pacific Railway on the theory it could always sell more bonds to European investors. A Vienna real-estate bust froze European demand in mid-1873. Cooke was left holding 75% of the bonds himself. He declared bankruptcy on September 18, 1873. The New York Stock Exchange closed for 10 days. Eighty-nine of the country’s 364 railroads failed. Eighteen thousand businesses went under. Unemployment reached 14% nationally and 25% in New York City. Rail construction fell from 7,500 miles laid in 1872 to 1,600 miles in 1875.

The AI collapse will be similar. What’s the first domino? Oracle.

Its credit spreads will blow out when its $300 billion of committed revenue disappears and its equity will collapse.

Data-center ABS spreads will widen from 400 to 800 basis points within six months of the first hyperscaler cancellation.

Digital Realty Trust (DLR) and Equinix (EQIX) marks drop 50%.

Regional banks with data-center and office exposure will fail: Zions Bancorporation (ZION), Regions Financial (RF), KeyCorp (KEY), Truist Financial (TFC), and Fifth Third Bancorp (FITB).

Index fund concentration is worse today than it was in March 2000. The top seven S&P 500 stocks are 35% of the index today, versus 18% for Cisco Systems (CSCO), Microsoft, Intel (INTC), and General Electric (GE) at the 2000 top. A 50% to 60% Magnificent 7 drawdown takes the S&P 500 down 35% to 45%.

Treasuries rally… at first. Flight to quality will push the 10-year yield down 75 to 100 basis points. But then the fiscal deficit will soar as capital-gains tax receipts collapse, and unprecedented government borrowing demand will push yields to levels we haven’t seen in decades. Over 10% on the 10-year U.S. Treasury bond.

Unemployment will soar. Direct tech and hyperscaler layoffs of 300,000 to 500,000. Data-center construction workers, utility contractors, and second-order services take another million-plus. Prime-age labor-force participation will fall another 100 basis points.

Then the 2028 election will become a critical referendum on how we’re going to run our country. The Democrats will win. And they will choose socialism.

The CHIPS Act passed in 2022 shelled out $50 billion in federal money to support the semiconductor industry. Expect CHIPS Act 2.0, with federal grants converted to equity. Expect direct Fed liquidity facilities to backstop the data-center ABS and GPU-collateralized-loan markets, resembling the 2008 federal emergency lending programs. Total emergency fiscal envelope, 2026 through 2028: $500 billion to $800 billion, on top of existing deficits.

How to protect yourself?

  • Gold, in the long run
  • Cash, in the short run
  • Regulated utilities that captured the AI power-purchase agreements before the mania
  • Tobacco and energy majors with capital discipline
  • Biotechnology, because compute cannot destroy a 20-year patent

What to short: Oracle. CoreWeave. Nebius Group N.V. (NBIS). IREN (IREN). Vertiv Holdings (VRT). Digital Realty. Equinix.

Tell me what you think of today’s Daily Journal: porterstansberrydirect@gmail.com

Good investing,

F. Porter Stansberry
Stevenson, Maryland

⚙ Edit 🗑 Delete

⚙ Edit 🗑 Delete

Presented By: Paradigm Press


Oil Prices Could Send These Three Stocks Soaring

If the turmoil in the Middle East has you rushing to buy oil stocks right now – STOP and read this.

The biggest gains from the last oil crisis didn’t come from oil companies.

The top-performing energy stocks were tiny. Practically unknown. And every major oil company in America was completely dependent on them.

Today, it’s the exact scenario— except the scale is roughly 13,000 times larger.

That’s why I just vetted three of these companies in this exact same position.

But this time it’s not just oil that’s driving them higher…

Trump’s latest initiative could lead this sector to a major surge.

Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Paradigm Press is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.


3 Things To Know Before We Go…

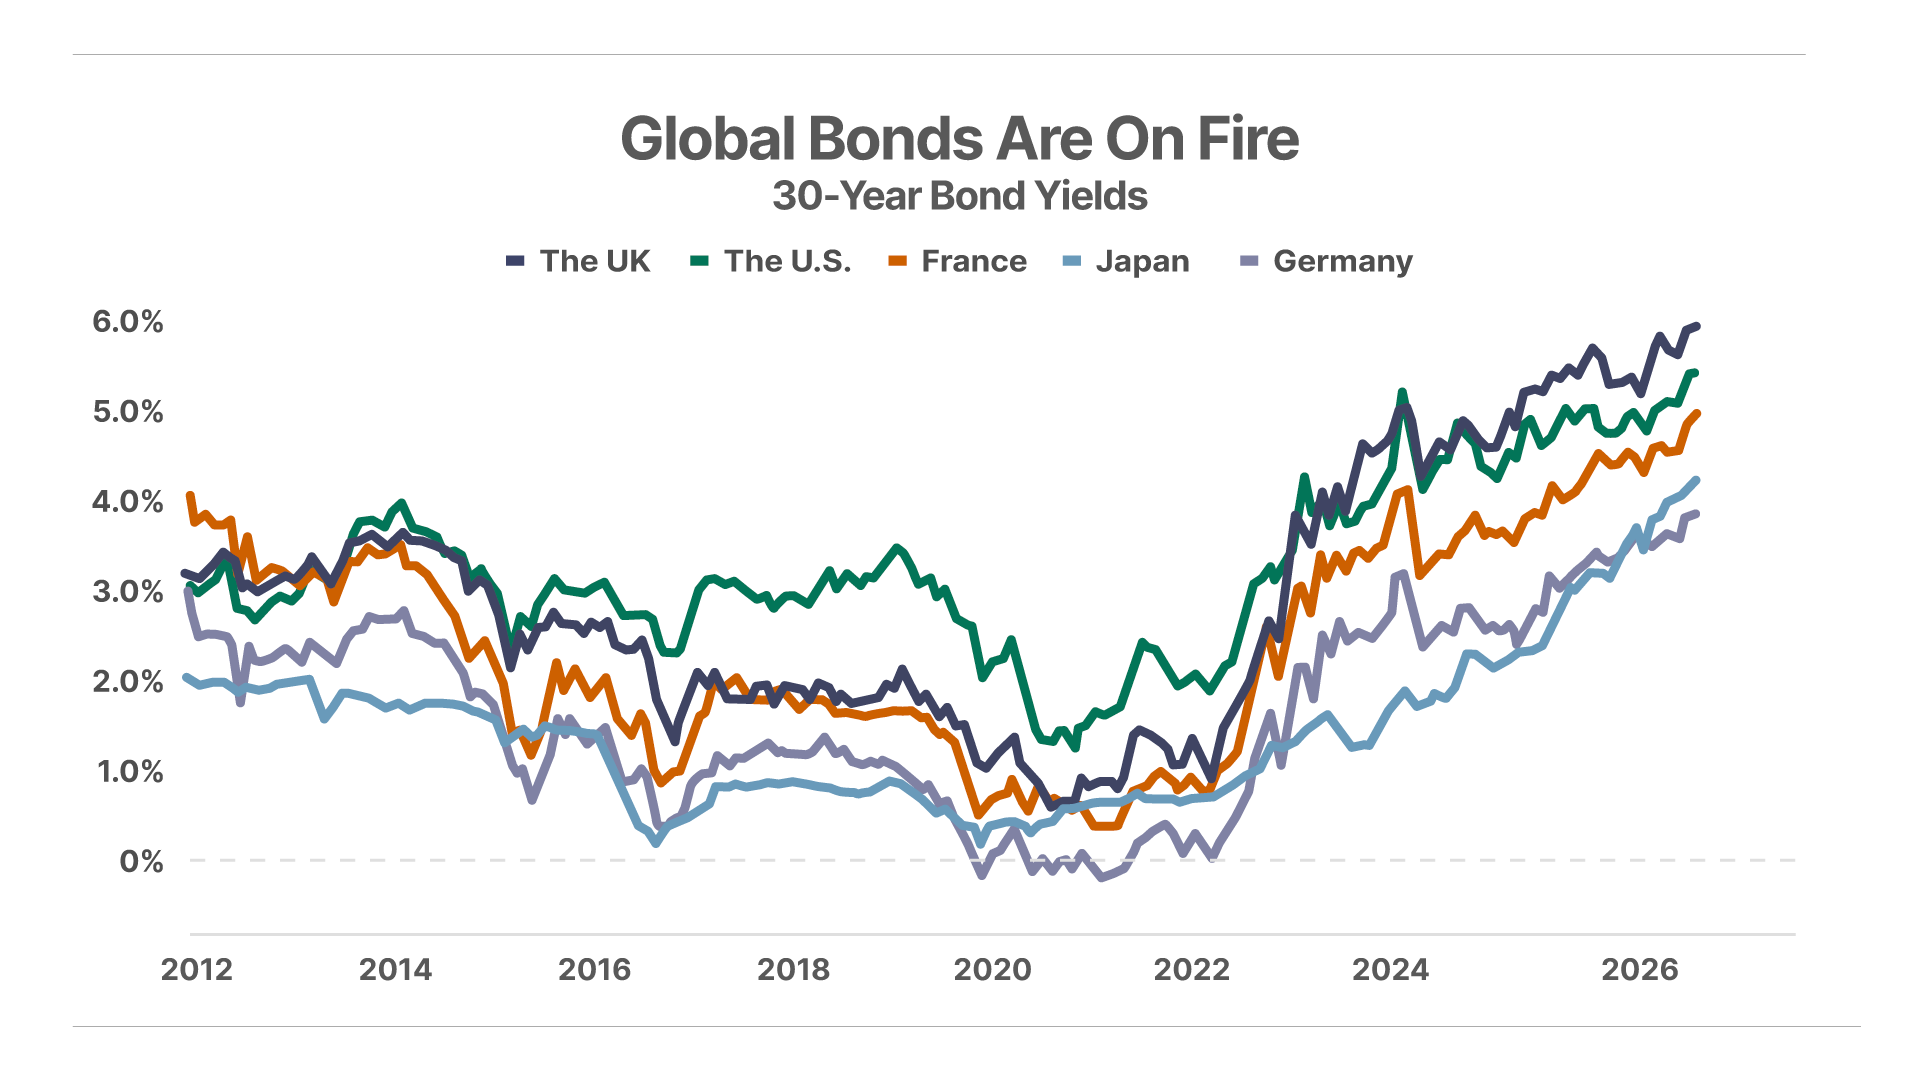
1. The global bond market is repricing the cost of government debt. Britain’s 30-year gilt yields 5.85% – the highest since 1998. The U.S. 30-year Treasury hit 5.33%, a level last seen in 2007. France’s is near 4.9%, an 18-year high. Germany’s reached 3.78%, the highest in 15 years. Japan’s is near a record just above 4%. This is not an inflation scare. All of it came from the real yield – reckless fiscal policy is driving investors to demand higher yields to lend to governments worldwide.

2. Traders are betting against tech while tech execs are buying. Hedge funds and asset managers have built their largest-net short position on record in Nasdaq 100 futures – contracts that pay off when the index falls – at nearly $20 billion. At the same time, corporate insiders at technology companies, the executives and directors with the clearest view of their own businesses, are buying their own shares at close to a 15-year high.

3. Home Depot (HD) shrugs off the frozen housing market. Home Depot reported fiscal Q2 2026 results (quarter ending August 2) that exceeded analyst estimates across the board this morning. Revenue grew 5.7% year-on-year (“YOY”) to $47.86 billion, while net income increased 4.7% YOY to $4.8 billion. Comparable sales rose 1.7% YOY, notching the strongest growth since Q3 2022, fueled by 11% growth in online sales. CFO Richard McPhail described the macro environment as challenging due to “frozen housing market conditions,” but noted that the company is taking market share and reaffirmed full-year fiscal 2026 guidance.


Chart Of The Day… Axon Enterprise (AXON)

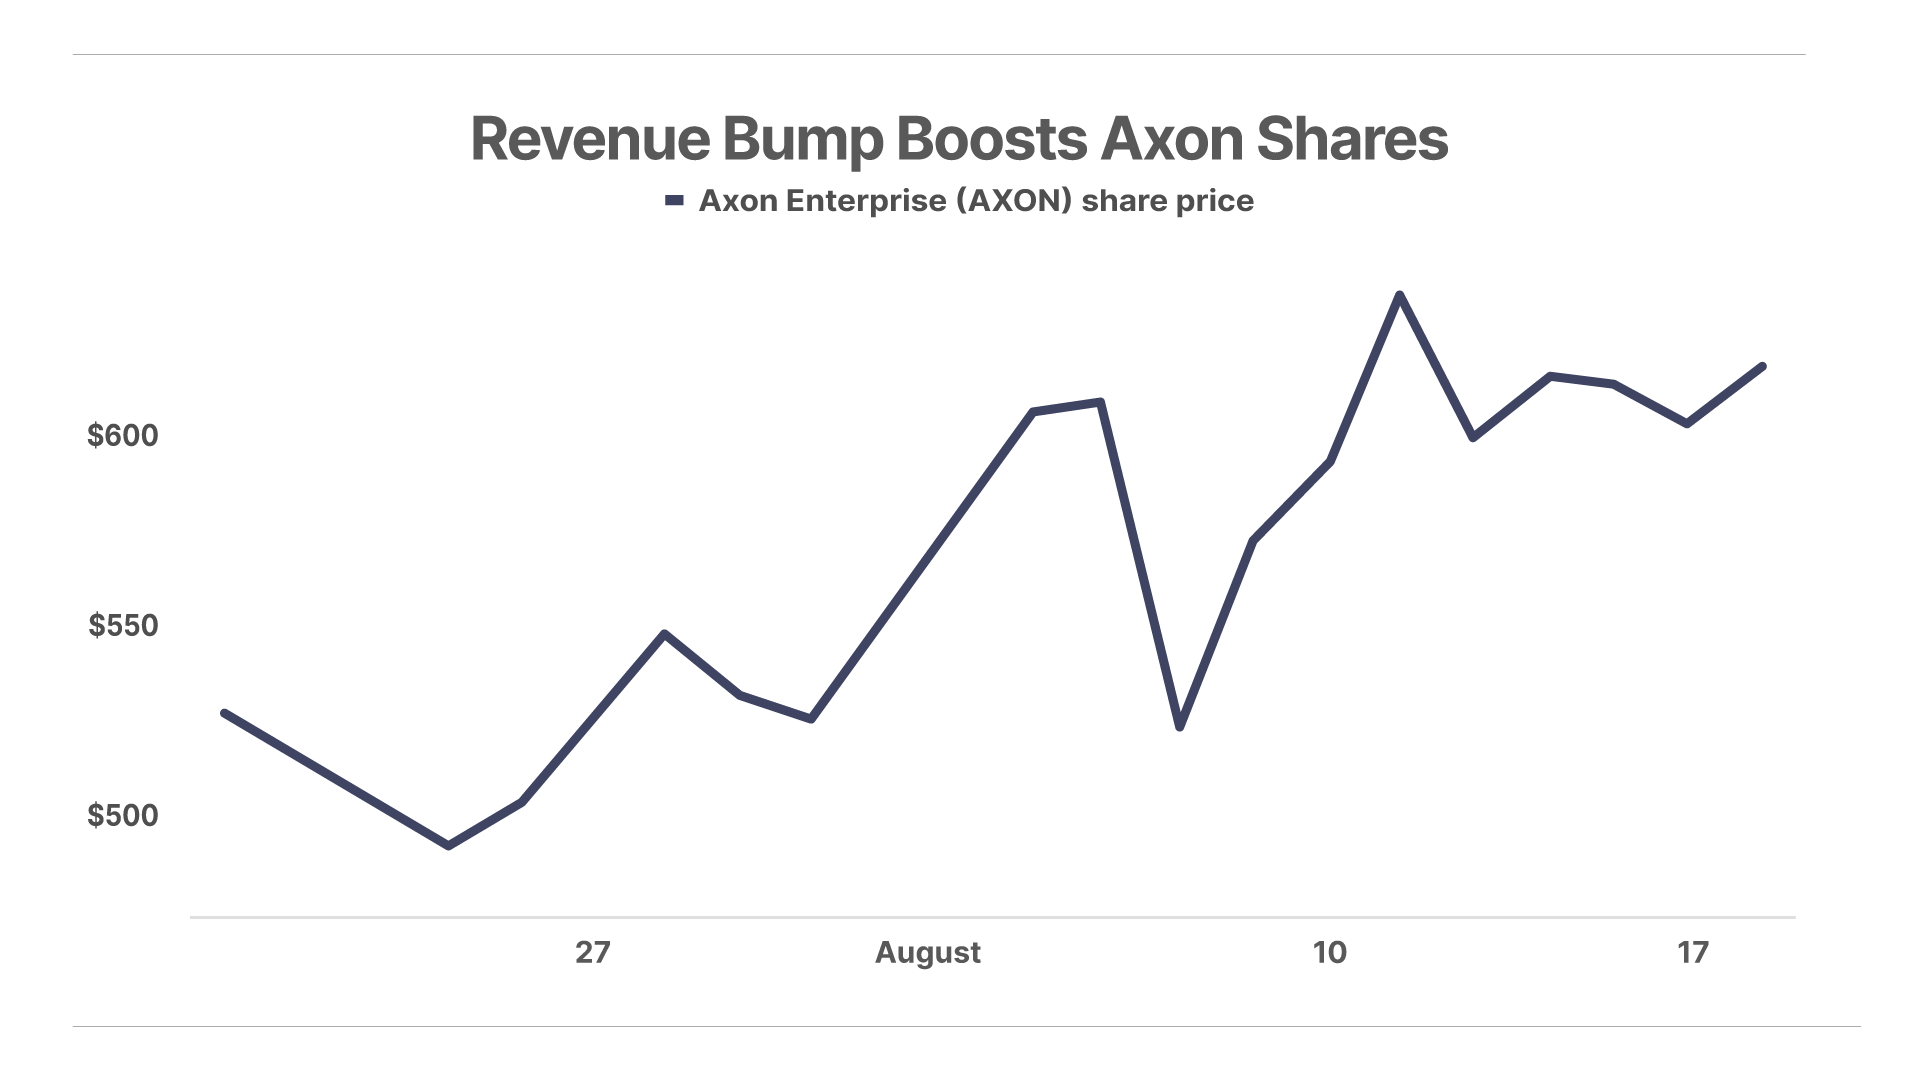
Shares of law-enforcement hardware and software supplier Axon Enterprise (Axon) have gained 20% since our July 18 Complete Investor recommendation. The gains have been fueled by Axon’s stellar Q2 earnings on August 5, which included a 35% YOY increase in revenue that marked Axon’s 10th consecutive quarter of 30% or better revenue growth.


Mailbag

Yesterday, Porter wrote about the questionable business model of CoreWeave in the Daily Journal titled “From Him Who Hath Not, Much Will Be Taken.”

George F. writes:

Hi, Porter:

While I like your investing acumen and your often deep thinking through many issues that affect investment decisions and world affairs, it’s quite disturbing when you reference Scripture and take the word of God out of context.

Your reference to the words of Jesus in Matthew 25 was from The Parable of the Talents: Matthew Chapter 25, Verse 29, “For to everyone who has will more be given, and he will have an abundance. But from the one who has not, even what he has will be taken away (ESV).”

This parable spoken by Jesus has nothing to do with earthly wealth, even though He used a landowner/master and his servants as an example for the story. The Parable of the Talents is actually about the spiritual gifts provided by the Holy Spirit (sent by Jesus) and how those gifts are used to advance the kingdom of God. Two of the slaves doubled the measure of their master’s trust (talent = a unit of measure), and the third slave did nothing with the trust given to him. Note that in this case the master leaving on the journey is representative of Christ. The third was cast as a worthless servant into the outer darkness (verse 30) where there will be “weeping and gnashing of teeth,” which speaks of inconsolable grief and unrelenting torment. Jesus commonly used that phrase to describe hell.


Another reader writes:

Wow! What a damning message. I invested some money in CoreWeave – it sounded too good to be true. Well, I ended up with losses that I can deal with. My bad! What I see is other investors chasing the rainbow and losing much more. Good luck to them. Thanks for a great article. Keep them coming.


Porter & Co. Market Snapshot

Price Yesterday’s Return Year-to-Date Return
S&P 500 Index $7,745.06 -0.51% 13.9%
Gold per ounce $4,415.99 0.81% 1.7%
Bitcoin $64,354 2.13% -26.8%
Oil (West Texas Intermediate) per barrel $84.50 2.39% 48.3%
Berkshire Hathaway (BRK) $747,400 -1.08% -1.0%
Porter’s Permanent Portfolio – -0.33% 2.0%
The Better Than Berkshire Index – -0.89% 9.4%
Total Return Annual Return
Porter & Co’s Top Ranked* 33.4% 16.1%
Yield Yesterday’s Change Change
Year-to-Date
U.S Treasury 30-Year Yield 5.31% 5 bps 46 bps
Prices as of 4:00 pm ET August 17, 2026 | bps = basis points (or 0.01%)
*A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.

Porter & Co. Top Positions

Publication Ticker Description Total Return
Biotechnology QURE uniQure 237%
Complete Investor BWXT BWX Technologies 201%
Biotechnology SGMT Sagimet Biosciences 194%
Biotechnology ROIV Roivant Sciences 160%
Biotechnology NUVB Nuvation Bio 155%
Biotechnology TGTX TG Therapeutics 140%
Complete Investor BTC/USD Bitcoin 139%
Complete Investor SKWD Skyward Specialty Insurance 133%
Biotechnology QURE uniQure 131%
Complete Investor PM Philip Morris 130%
Prices as of 4:00 pm ET August 17, 2026

Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

The post No More Repo Facility = No More Free Money appeared first on Porter & Co..
  •  

From Him Who Hath Not, Much Will Be Taken

Issue#141, Volume#3

Why Nvidia’s Neoclouds Will Collapse

Editor’s note: Today is Porter’s fourth in a series about the enormous financial risks of the ongoing AI bubble. Please see the first essay here, the second essay here, and the third essay here.


It’s no surprise, but investors must remember that when the financial plumbing goes zero-sum, the pain will not be meted out equally. It’s the weakest who will suffer the most.

As Jesus says in Matthew 25:

From him that hath not, even that which he hath is taken away.

Here’s one “hath not” that I’m certain will soon go to zero: CoreWeave (CRWV).

CoreWeave is a “neocloud.”

When a business model is described by a made-up word that has no actual meaning in the English language… buyer beware.

Neoclouds are companies that buy huge quantities of Nvidia fast graphics processing unit (“GPU”) chips, house them in data centers, and rent them out by the hour or the month, primarily to artificial intelligence (“AI”) companies. CoreWeave’s biggest customer (both directly and indirectly through Microsoft) is OpenAI. OpenAI isn’t funded from earnings. It’s funded by investors (who are taking losses) and Nvidia vendor financing.

CoreWeave has a business model only a sadistic mother would love. It is enormously capital-intensive because it must buy the Nvidia GPUs upfront – billions of dollars at a time. But the customer revenue comes in slowly over the following years. It is far from certain whether this future revenue will outpace the rapid depreciation of Nvidia’s GPUs.

And here’s the bigger problem: its collateral is also Nvidia GPUs. GPUs are physical hardware that Nvidia itself has said will be obsolete on a roughly two-year cycle. A GPU-backed loan is a claim on hardware that is losing value from the moment the loan is signed. And the price of these rapidly depreciating assets is likewise correlated to demand for CoreWeave’s services. It’s similar to how car-rental companies all go broke. When there’s a recession and no one is renting cars, the price of used cars likewise collapses.

The same will happen to CoreWeave’s data centers and its GPUs.

On July 29, 2026, CoreWeave came to the leveraged loan market to raise $2.6 billion of new debt secured by its GPUs. But the death scramble for capital had already begun. CoreWeave’s collateral looked shakier than it had 10 weeks earlier, because the market had started digesting the possibility that AI-application revenue wasn’t scaling as fast as the capex commitments.

The loan came to market with initial price talk of SOFR+425 to +450 at 99 OID. Translation: the interest rate would be the standard short-term rate (the Secured Overnight Financing Rate, currently around 4.3%) plus roughly 4.4% on top – so about 8.7% all in – and the buyer would pay 99 cents on the dollar and get repaid at 100, giving them a small extra return over the life of the loan. That’s “price talk” – where the underwriters expected the deal to clear based on pre-marketing to buyers.

The deal actually cleared at SOFR+550 at 97 OID. Translation: the interest rate rose to about 9.8%, and the buyer only paid 97 cents on the dollar and would get repaid at 100 – another chunk of return.

That’s a “125-basis-point flex” – the interest rate had to be widened by 1.25 percentage points from the initial guidance to get buyers to take the paper. The total yield to maturity ended up at 10.44%. And to get even that, CoreWeave had to accept a covenant requiring a 1.35x debt service coverage ratio, meaning if its EBITDA falls below 1.35 times its debt payments, the lenders can take action, aka, force the company into liquidation.

Only 10 weeks earlier, CoreWeave had raised $3.1 billion at SOFR+450, and the deal had actually tightened by 50 basis points during marketing – meaning demand was so strong the underwriters could offer worse terms to buyers. By late July, the same borrower had to offer 125 basis points more, plus a discount on the paper, plus a tighter covenant, just to get the deal done.

The borrower didn’t change materially in 10 weeks. But the credit environment did.

What kills capex booms isn’t poor earnings. Investors, seeing revenue soaring, will always put up more capital.

What kills capex booms is the money running out.

And the money is running out.

In the next essay, I’ll show you exactly what sparked the industry’s desperate scramble for capital, and I’ll show you why the AI buildout is on borrowed time.

Tell me what you think of today’s Daily Journal: porterstansberrydirect@gmail.com

Good investing,

F. Porter Stansberry
Stevenson, Maryland

Presented By: Brownstone Research

How to Profit From”The SpaceX Supercycle”

Act Before August 26

According to legendary tech investor Jeff Brown…

Three words on page 37 of the SpaceX IPO filing…

Signal Musk is about to trigger a rare wealth supercycle…

And send billions into a sector nobody associates with tech.

Click Here Now To Watch His Urgent Strategy Session

Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Brownstone is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.


3 Things To Know Before We Go…

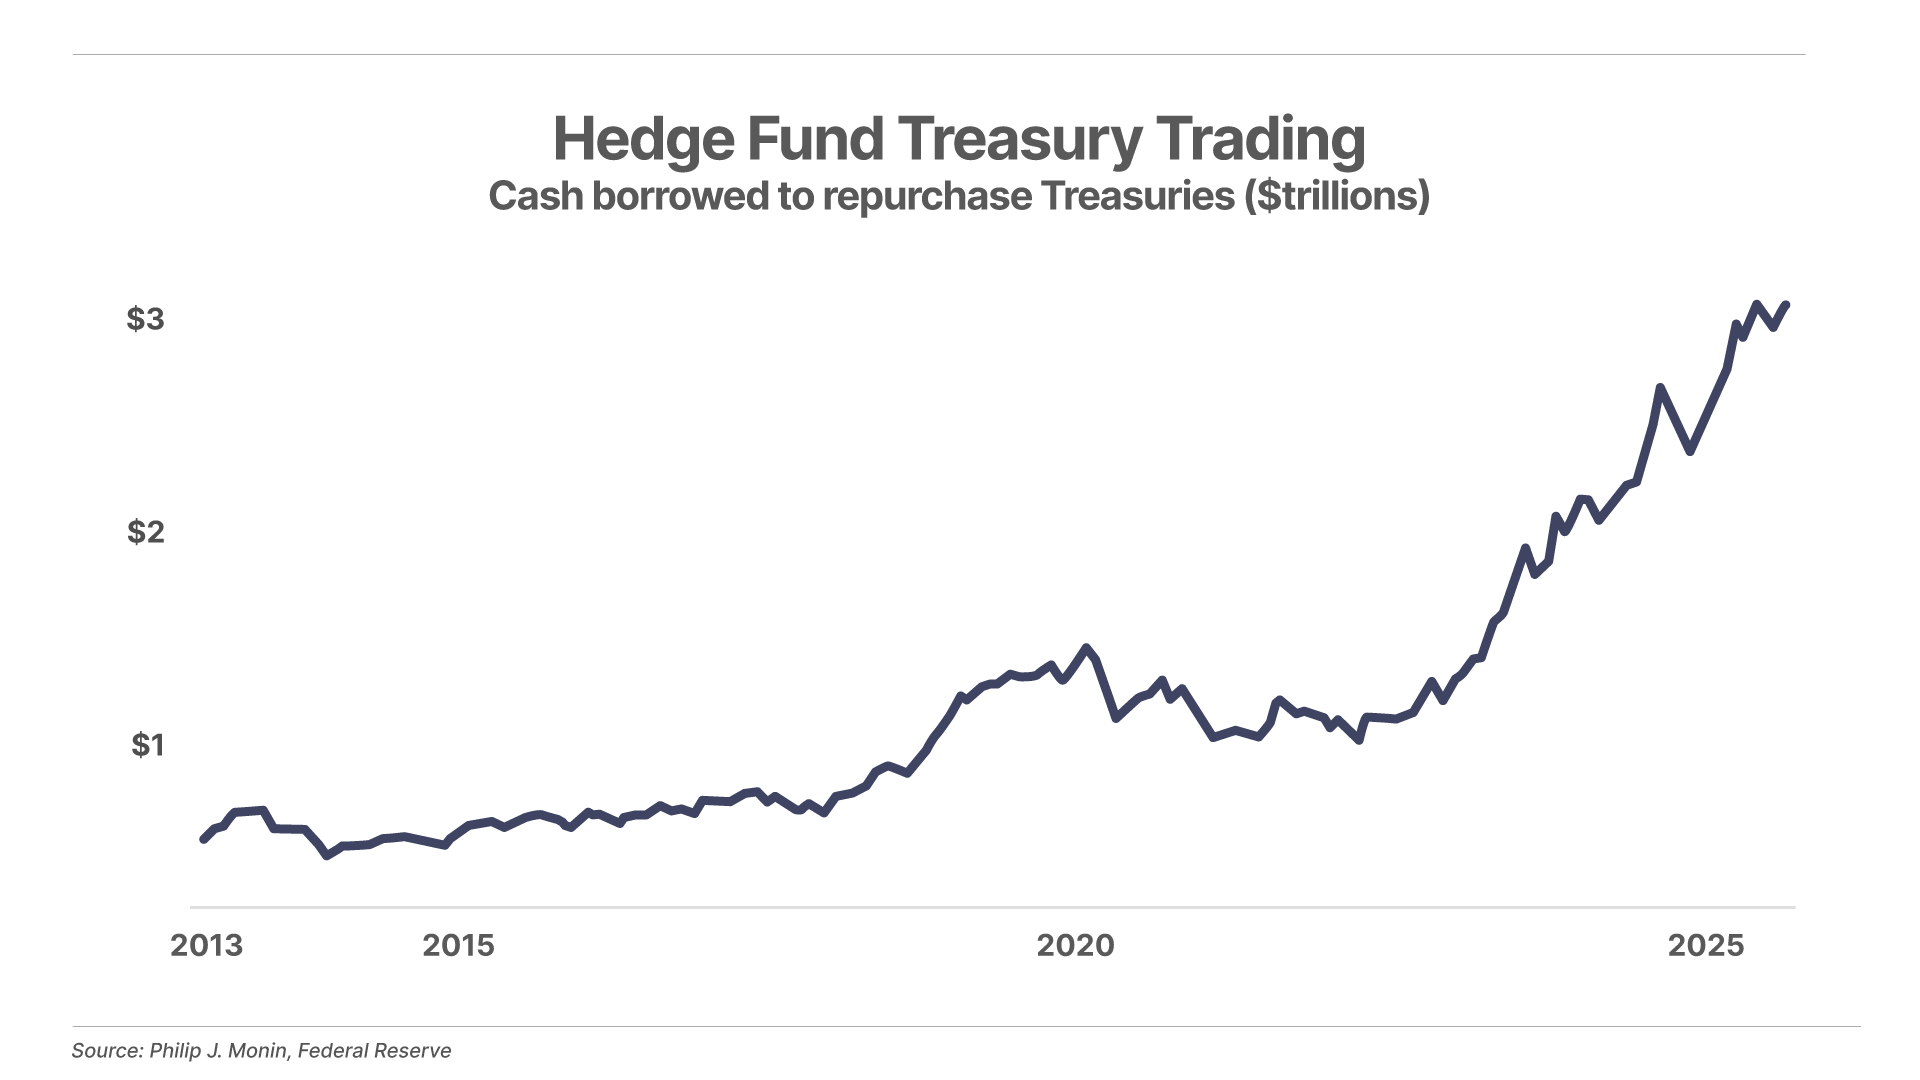
1. Money managers trade big on Treasuries. Hedge funds currently own $2.4 trillion in U.S. Treasury bonds, up from $600 million a decade ago. Part of that growth comes from the increasingly popular “basis trade” – buying Treasuries and simultaneously shorting Treasury futures, pocketing the small spread between the two. To make this worthwhile, funds can borrow money to use 15x leverage from the “repurchase” (repo) market, which now supplies over $3 trillion in overnight funding. It’s all good until the market goes against you.

2. Big tech’s AI bill is 4x bigger than it looks. Alphabet (GOOG), Amazon (AMZN), Meta (META), and Microsoft (MSFT) now carry $2.4 trillion in off-balance-sheet commitments – versus just $604 billion on the balance sheet, reports the Wall Street Journal. This is locked-in future spending on purchase commitments for chips, cloud capacity, energy, and leases. The inertia is bullish near term for the entire AI value chain – Nvidia, Broadcom, memory, power – but hinges on AI revenue actually materializing.

3. The AI build-out is now raising everyone’s borrowing costs. The highest-rated corporate borrowers have issued nearly $1.5 trillion of investment-grade bonds this year, up 36% from a year ago – and $200 billion of that came from the biggest tech companies. Treasury Secretary Scott Bessent has leaned on short-term bills to fund the deficit, which Barclays estimates will cut the supply of new Treasury notes and bonds by about $440 billion this year. Corporate supply is more than filling the gap – growing by $474 billion. Now, bond funds are selling Treasuries to buy the higher-yielding corporate debt. The AI trade was built on cheap capital. It is now making capital more expensive.


Chart Of The Day… LandBridge (LB)

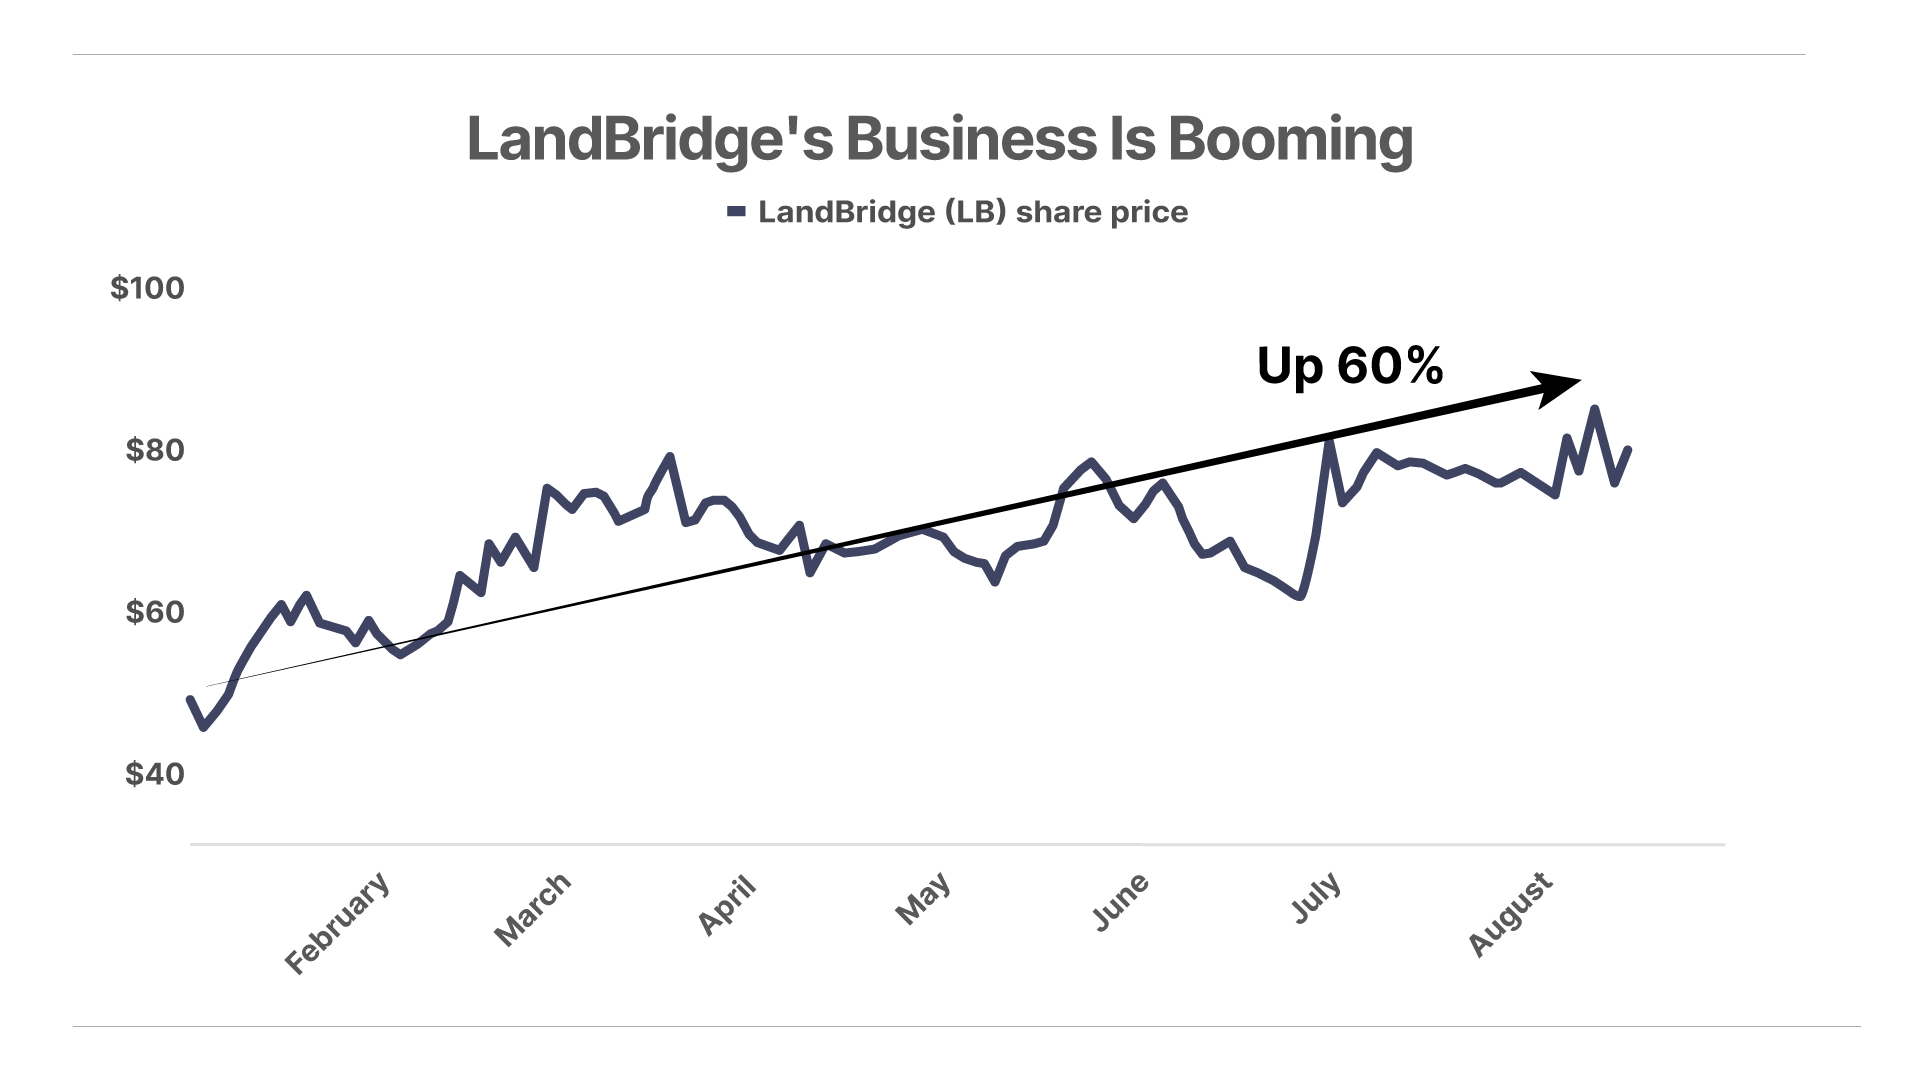
Shares of the West Texas land-leasing company (and Complete Investor recommendation) LandBridge (LB) are up 60% this year – with revenue up 41% year-on-year (“YOY”) and net income up 68% YOY. And it’s now further positioned to capitalize on the data center boom, with the company reporting advanced discussions with seven counterparties representing over 10 gigawatts of power and data center capacity in its latest quarterly.


Mailbag

“Incredibly Impressed”

Samuel B. writes:

Dear Porter,

I have been meaning to write to you for a few weeks, and on this quiet morning by the lake, I am finally taking the time to do so.

I am very pleased to hear that you are continuing Tech Frontiers (now Biotechnology) as a Partner service. Historically, biotechnology has been outside my comfort zone, even when backed by an analyst I deeply respect. Instead, my investment comfort zone leans toward sectors like oil, gold, commodities, and capital efficient businesses. However, I decided to step outside my usual lane when Erez Kalir’s newsletter first launched. I invested in every single one of his recommendations proportionately to my account size, and it proved to be an excellent decision.

I have been incredibly impressed with the product. Beyond the strong returns, the educational depth of Erez’s presentations was outstanding. I also thoroughly enjoyed listening to his sessions via your recorded conference archives on the website.

When the announcement came that Erez was leaving, I was naturally disappointed. My immediate thought was how difficult it would be to replace someone of his caliber. Coming from the construction industry, I know firsthand how painful it is to lose a key player, and how that heavy workload usually lands squarely back on leadership’s shoulders. I imagine you are navigating that exact burden right now.

That said, I have followed your work for a long time, and I have complete confidence that you will continue to do great things with this publication. After reading your first issue under the new transition, I just wanted to say: please keep up the excellent work. The Partner Pass at Porter & Co. has already delivered immense value to me, and I am incredibly happy to be a part of the team.

Best regards


In Friday’s Journal, Porter continued his series on the consequences of the massive amounts of capital being poured into the AI buildout.

“Trillion With A T”

Sherwin R. writes:

Porter, thank you for this extremely insightful article. The auditor note is a doozy. It’s also worth noting, although it was not part of your topic, that it’s possible that Meta will be facing a trillion – with a t – dollar judgment in connection with the trial that I believe began this week relating to its improper influence over children.


“Meta’s Vulnerabilities”

Edward B. writes:

Great article. It definitely shows Meta’s vulnerabilities.


Pravin M. writes:

Agree with you 100%. I am amazed at how Meta has gotten away with wasting so much money, with seemingly little impact on share price.


Bill W. writes:

Meta… whew!


Porter & Co. Market Snapshot

Price Friday’s Return Year-to-Date Return
S&P 500 Index $7,785.76 -0.16% 14.5%
Gold per ounce $4,376.40 0.60% 1.4%
Bitcoin $63,013 -0.06% -28.3%
Oil (West Texas Intermediate) per barrel $82.40 7.03% 43.5%
Berkshire Hathaway (BRK) $755,570.01 -0.84% 0.1%
Porter’s Permanent Portfolio – 0.14% 2.3%
The Better Than Berkshire Index – 0.32% 2.3%
Total Return Annual Return
Porter & Co’s Top Ranked* 35.4% 16.6%
Yield Friday’s Change Change
Year-to-Date
U.S Treasury 30-Year Yield 5.26% 5 bps 42 bps
Prices as of 4:00 pm ET August 14, 2026 | bps = basis points (or 0.01%)
*A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.

Porter & Co. Top Positions

Publication Ticker Description Total Return
Biotechnology QURE uniQure 237%
Complete Investor BWXT BWX Technologies 204%
Biotechnology SGMT Sagimet Biosciences 196%
Biotechnology ROIV Roivant Sciences 160%
Biotechnology NUVB Nuvation Bio 145%
Complete Investor SKWD Skyward Specialty Insurance 142%
Biotechnology TGTX TG Therapeutics 138%
Complete Investor PM Philip Morris 136%
Complete Investor BTC/USD Bitcoin 133%
Biotechnology QURE uniQure 131%
Prices as of 4:00 pm ET August 14, 2026

Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

The post From Him Who Hath Not, Much Will Be Taken appeared first on Porter & Co..

  •  
❌