❌

Normal view

  • ✇Porter & Co
  • The End Of The Credit Card Cartel Porter &#38 · Co.
    Disrupting The Market For How Consumers Borrow To Buy Edit Delete This is the free version of Porter Stansberry’s Complete Investor, which provides market analysis and investor insights. Paid subscribers get access to the full issue, including investment recommendations with buy-up-to prices, a real-time list of holdings, and more. Click here for details. Two scalps taken, 30 stolen horses recovered, and a good yarn to tell when he went back East. All in all, it had been a pretty suc
     

The End Of The Credit Card Cartel

19 September 2026 at 07:00

Disrupting The Market For How Consumers Borrow To Buy

⚙ Edit 🗑 Delete

This is the free version of Porter Stansberry’s Complete Investor, which provides market analysis and investor insights. Paid subscribers get access to the full issue, including investment recommendations with buy-up-to prices, a real-time list of holdings, and more. Click here for details.


Two scalps taken, 30 stolen horses recovered, and a good yarn to tell when he went back East. All in all, it had been a pretty successful expedition for wilderness scout Kit Carson.

He’d escaped death multiple times, helped map 2,000 miles of the Oregon Trail, and along the way, unwittingly launched the J.C. Penney department store.

Penney’s came about by accident when Carson put his foot down a rabbit hole in Kemmerer, Wyoming. In June 1843, Kit and his exploring buddy, John Fremont, quickly realized they’d stepped in the first known coal deposit in Wyoming Territory – definitely something to write home about.

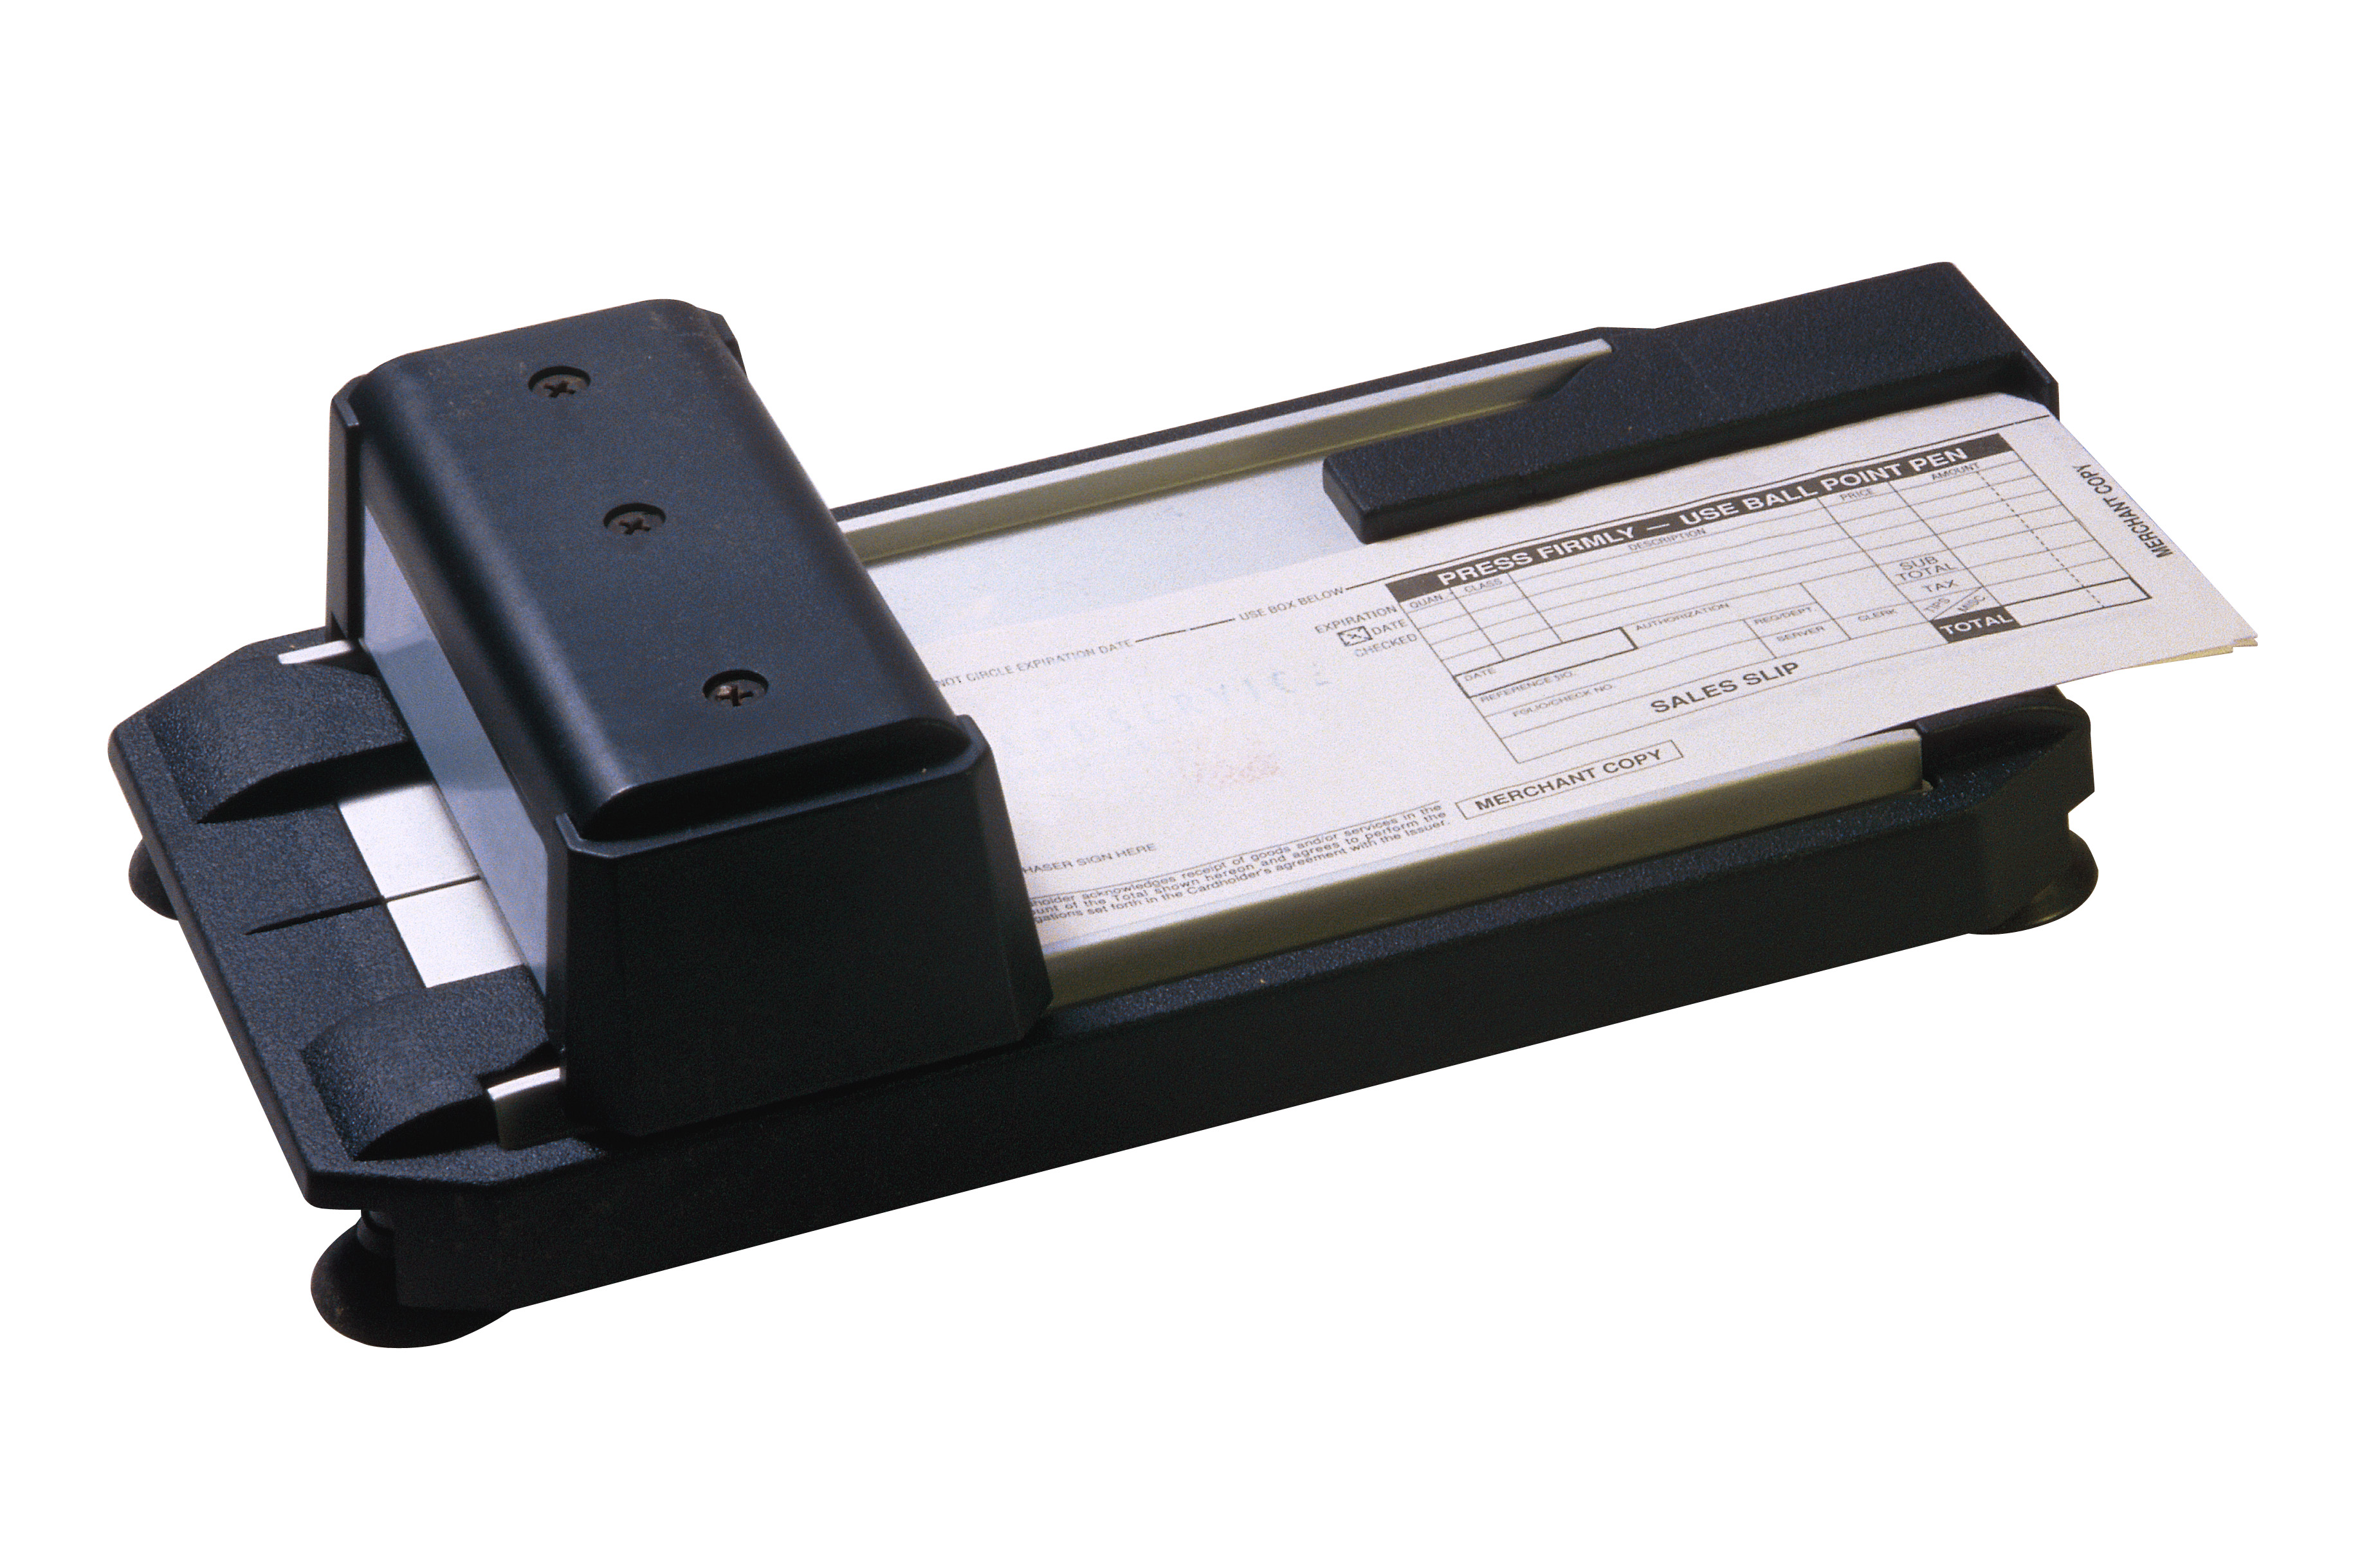
A few maps and a newspaper notice later, Kemmerer was a booming mine town with railroads, shanties – and a shiny new general store called the Golden Rule, run by straight-laced Baptist shopkeeper James Cash Penney… (pictured below)

Penney took “do unto others” so seriously that he refused to allow his customers to go into debt. Where most stores in frontier towns issued piles of store credit or scrip, Penney ran a strictly cash-only establishment – pay upfront or get out.

Surprisingly, the coal miners loved it. Penney’s first year in business scored him $29,000 in a town of a thousand, well over $1 million in today’s money. Dropping the Golden Rule name, but keeping the gold-only ethic, he opened up nine more newly named J.C. Penneys across the Rocky Mountains over the next decade… and then kept expanding.

By the mid-1950s, with over 1,600 locations across 48 states, Penney’s had established itself as one of the Big Three American dry-goods stores, neck-and-neck with catalogue kings Montgomery Ward and Sears. The difference was that Sears and Montgomery Ward offered store credit… and JCPenney still refused.

By 1957, that stance had started to pinch Penney just a bit.

Post-World War II, young baby-boom families eagerly purchased cars and Frigidaires on credit (via a growing assortment of bank-licensed charge cards, in addition to store credit). Ward and Sears were only too happy to feed the beast. If JCPenney didn’t start offering credit too – proclaimed then-vice president William Batten – they’d be out of business by 1970.

Reluctantly, James Cash Penney – a year or two away from retirement – agreed. Batten took over as president in 1958, stamped out the J.C. Penney Charge Card, and the long-delayed credit party got started. Even James Cash himself had to admit “It seems to be working,” as he prepared for the chain’s first year of $3 billion sales in 1970, one year before his own death.

Apparently, JCPenney customers just loved to be in debt. And that insatiable appetite for credit caught the eye of Dee Hock, the mysterious man who invented the Visa card.

Finding The Chaordic Way

Dee Hock had cut up all his credit cards by 1968.

“I have absolutely no use for credit cards,” he explained. Like James Cash Penney, he believed in exchanging money, not debt.

The only difference was that Hock envisioned a giant, cashless, cooperative network of virtual money, where merchants, consumers, and banks freely traded value back and forth. He called this system – a decentralized, self-governing organization – “chaordic,” because it was a blend of chaos and order.

He dreamed all this up while twiddling his thumbs as a mid-level manager at the National Bank of Commerce in Seattle.

And when his boss knocked on the door and asked him to fix the bank’s broken credit card system, 39-year-old Hock jumped at the chance…

Bank of America had tried to “license” its proprietary credit cards out to other banks (like Hock’s employer, Bank of Commerce) for $25,000 a franchise, but the clunky arrangement rapidly imploded on itself.

Hock’s vision was radically different: He proposed that Bank of America should give up its rights to the card, and that the new credit card, called VISA, would be owned and operated jointly by a cooperative of banks. Privately, he didn’t believe VISA should be a credit card at all, but something more akin to a debit card: a global “exchange of value.” (The member banks nixed this idea, because credit made them a lot more money than debit ever would.)

Still, Hock’s powers of persuasion were almost magical. Within two years, he’d convinced Bank of America to relinquish its rights to the “Americard”… gotten 3,000 banks on board as cooperative owners… and risen to CEO of the newly-formed company. He’d also turned the stumbling business around and grown it at 50% annually.

And then he took things a step too far.

Building The Visa Empire

In a move far ahead of his time, Dee Hock decided to loop merchants in as part of the credit card transaction. Specifically, JCPenney, which he knew was ga-ga for credit cards.

Credit cards worked then – and still work – as direct communication between banks. The merchants and consumers don’t have access to payment information. They are just dragged along for the ride (and dinged for fees). But in Hock’s democratic vision, this wasn’t fair: Every participant should be in the loop.

As he put it:

Many bankers refuse to realize that many large retailers can do everything a bank can do, and often better. [J.C.] Penney is more sophisticated in data capture and data communications than any bank I know of.

Credit-crazed Penney was also an easy sell. In 1979, Hock offered them a deal they couldn’t refuse: He’d cut them into the VISA network as direct partners, without routing them through a third-party bank.

Of course, the problem there is… if merchants can do anything a bank can do, what do we need banks for?

That’s what spooked Hock’s bank colleagues at VISA – and why they forced him out of his boardroom chair and sleek penthouse office in 1985. He spent the next decade sulking on a ranch in Pescadero, California, before reemerging to give lectures on chaordic management.

Without Hock, VISA continued to grow into a $700 billion credit card juggernaut – but along strictly conventional lines. It boxed out merchants and consumers and operated as a bank-to-bank-only network. And in 2008, it ditched its cooperative structure and became a standard shareholder-owned corporation.

As for JCPenney… like many tee-totaling Baptists who take their first drink later in life, JCP couldn’t hold its liquor.

Drunk on credit, the chain eventually found itself $3.6 billion in debt and filed for bankruptcy in 2020, following which, its stores have been slowly going dark in malls across America. James Cash Penney would disapprove.

Dee Hock, too, expressed disappointment in how his brainchild had turned out:

By the standards of what VISA ought to be, it would be a lie to deny a sense of failure. I do not believe that VISA is a model to emulate. It is no more than an archetype to study, learn from, and improve upon.

Strangely, in the 40 years since Dee Hock left VISA, no one’s managed to do that. Nobody seems to be able to build a Hock-style payments network that satisfies banks, merchants, and consumers. Walmart, Target, and Lowe’s have all tried and failed.

And then – not long ago – one tiny payments company succeeded…

Directly inspired by Hock’s cooperative network, virtual monetary exchange, and bank-merchant-customer equality, this is an under-the-radar fintech that’s solved almost everything wrong with Big Credit Card. It’s a company with insane scale and a pristine balance sheet, one we recommended live on stage at last year’s Porter & Co. Annual Conference… and one that we’re officially adding to our portfolio in this issue.

Sixty Years Of Nothing

Nobody has built a payments network to supersede what Dee Hock created with VISA. Visa (V) and American Express (AXP) went live in 1958, and Mastercard (MA) followed in 1966. Then there were 60 years of no innovation, while these incumbents compounded. And still do…

But consider how much a retailer pays to use the card networks every year. Large retailer Target (TGT), for example, recorded $105 billion of sales in fiscal 2025 – and about $75 billion of that filters through the card networks. Credit transactions cost a merchant 2% to 3% and regulated debit closer to 0.5%, so blended across the mix Target pays on the order of 1.5%. Target does not break out the figure, but the arithmetic is not hard – call it $1.1 billion a year to card processing against $3.7 billion of net income, roughly a third of what Target earned last year.

Across the top 15 retailers, with a trillion dollars of sales, the prize was some $15 billion a year. In 2012, those 15 retailers – Walmart, Target, Best Buy, and others – formed a consortium called the Merchant Customer Exchange (“MCX”) to build a payments network of their own, and four years later it was dead, having asked consumers to scan a QR code at the register in exchange for nothing at all.

But one company understands the lesson that Dee Hock understood in 1968 and the one MCX did not. A network is not assembled from the side holding the money. It is assembled from the side holding the choice. Every attempt to build a competing network had failed because none addressed a consumer need.

That is the company we are recommending today. It started from the other side – the consumer side.

⚙ Edit 🗑 Delete

Subscribe to Porter Stansberry’s Complete Investor to unlock the rest of this issue and more.

Become a Complete Investor subscriber today to get instant access to the rest of this issue and other valuable subscriber-only content.

A Complete Investor subscription gets you:

  • Monthly Issues – a detailed analysis on a new recommendation plus ongoing updates on the existing list of recommendations

  • Special Reports – deep-dive analyses covering every major market-moving trend such as artificial intelligence and other breakthrough technologies. Plus, why property & casualty insurance stocks are a must-own, the best ways to invest in energy and commodities.

  • Buy / Sell Alerts – instant notifications when any stock in our recommended list makes a major move worthy of your attention.

  • Monthly Roundtable – listen in to this exclusive podcast as Porter and his editorial team discuss the markets, the open recommendations, and the strategies subscribers can use to maximize their returns

  • Custom Investment Indexes – such as the Better Than Berkshire Index, a systematic approach to building your own Berkshire Hathaway holdings using superior companies, and The Lindy Index, the top-40 companies that have been compounding returns for at least 50 years, to name just two

  • Porter’s Permanent Portfolio – a fully balanced portfolio with 25% allocated to bond-like investments, 25% in the world’s best businesses, 25% in hard assets, and 25% in cash-like investments. Despite having half the risk of the market, this portfolio has consistently outperformed the S&P since inception

  • And more…

Use the link below today and lock in our lowest available rate –> a savings of $575 off the usual annual rate.

The Millionaire Who Was Denied A Car Loan

Affirm Holdings (Nasdaq: AFRM) is the company we are recommending in this issue. Started in 2012 and still run by the founding CEO, it generates $50 billion in total volume, $4.26 billion in annual revenue, with 28 million active customers, an increase of 21% over the last year.

A credit card is an open tab – the bank grants a limit, the balance revolves, and interest compounds. It’s a system some call “buy now, pay forever.” There is currently $1.2 trillion in outstanding credit card debt, $10,000 in existing revolving debt per household, and $15 billion in late fees collected per year.

Affirm’s model – built upon the buy now, pay later (“BNPL”) concept – inverts it. Each purchase is its own small loan, with a fixed number of payments, a fixed end date, and the total cost disclosed before the buyer commits. There are no late fees and no deferred interest. Affirm earns money only when its borrowers repay. That focus is the design principle the entire network is built on – underwrite every transaction, and never profit from a customer’s failure – and has been Affirm’s mission since 2012:

Deliver honest financial products that improve lives.

Affirm’s CEO is Max Levchin. Levchin is part of the PayPal mafia – a small group of entrepreneurs who helped start the payment platform and have gone on to lead other successful ventures. But two years after the PayPal IPO in 2002 – making him a multimillionaire – Levchin was denied a car loan. He had immigrated from Ukraine as a teenager, put himself through the University of Illinois, and used a credit card to fund one failed venture after another without understanding what it meant to his credit score. The pain and embarrassment from getting denied a car loan sticks with Levchin to this day.

The denial kept him away from credit cards for good, but also got him thinking: Why is the American credit system designed so that the lender wins when the borrower stumbles?

So in 2012, he went back to his friend and fellow PayPal engineer Nathan Gettings and asked him to take on the part PayPal never reached – credit, where the abuses live. Levchin explains…

The way to disrupt the financial system at the very core is you have to go after credit. Credit is the heart of what banking is. That’s how money gets created – banks lend out money, and that’s how it’s manufactured. And financing is probably the single most important thing. It’s the way to invest in your better self.

Gettings left Palantir Technologies (PLTR) – which he helped found with Peter Thiel – to co-found Affirm with Levchin as its chief risk officer. While at PayPal, Gettings and Levchin read patterns and data to discover fraudsters or terrorists. Now at Affirm they were looking at the behavior of ordinary borrowers, and the question was how much to lend.

This was the work Levchin knew best. Every bank in America runs on a core system built to underwrite an account – one decision, one credit line, rarely revisited. Affirm needed to underwrite a transaction: this buyer, this merchant, this item, this term, decided in the split-second time a checkout page takes to load. No vendor sold that system, because no lender had ever wanted it. So in the first two years before it made its first loan, Affirm built its own ledger from scratch.

What the ledger made possible is a risk score calculated for each transaction rather than each customer. Like any lender, Affirm takes in data from the credit bureaus (Equifax, TransUnion, and Experian are the top three), then adds what only Affirm can see – the merchant, the item, the cart, and, with permission, the cash flows in the borrower’s bank account. Affirm created what it calls ITACs (an acronym without an expansion name) – a proprietary score from zero to 100 assigned to nearly every loan. ITAC’s edge over a bureau score is significant. Cutting originations 30% using ITACs would eliminate 70% of delinquencies, while the same cut using a traditional FICO credit score would catch only 36%.

All of it – the ledger, the models, the years of losses – was a fixed cost built into a vertically integrated, data-preserving network. This meant Affirm could go straight to the merchants that wanted out from under the card networks but had no way else to go.

Selling Demand, Not Payments

Layaway is the oldest merchant-funded financing in American retail. The customer pays over time, the store holds the goods, and the store absorbs the cost because it sells a product and converts a shopper into a buyer. Affirm has a new take on layaway. The customer takes the item home today, the merchant pays Affirm a merchant discount rate or the consumer pays in simple interest, and the underwriting happens at checkout with Affirm taking the credit risk.

Affirm started with the hardest problem it could find. The early businesses were furniture, engagement rings, and Peloton exercise bikes – purchases too large for a credit card and too small for a bank loan. These are among the hardest underwriting transactions in consumer finance – unsecured, discretionary, and extended to consumers with thin credit history – which is why banks had left them alone for decades. If Affirm’s model worked here, it would work anywhere.

A $2,500 Peloton bike does not sell itself – but 0% over 39 months does.The merchant – in this case Peloton – can offer financing it could never have underwritten itself, on terms it chose, with no exposure if the borrower fails.

Then Affirm proved it worked. Merchants who added Affirm at checkout saw conversion rates rise 28%, and roughly 70% saw larger average carts. Affirm took the credit risk, the servicing, and the collections, so the retailer got the sale without becoming a lender.

The checkout page is the most contested real estate in retail, and a merchant adds a payment option only when it makes the best business sense to do so. Amazon (AMZN), Shopify (SHOP), and Walmart (WMT) all put Affirm directly onto their checkout pages.

The traditional card system generally benefits banks issuing credit cards. Affirm asked merchants to offer their pay-over-time solution, so that consumers could buy what they wanted, and the merchants said yes because it ultimately drove them higher conversions. The value moved in the direction that forms a network.

The Rise Of A Network

Now, 14 years later, Affirm has grown gross merchandise volume (“GMV”) by 37% to $50.2 billion in fiscal year 2026. Affirm added $13.5 billion in GMV in a single year. Behind those numbers are 28 million active consumers, transacting roughly seven times a year each, and 571,000 active merchants – merchant count grew 51% in 12 months, with the growth rate itself accelerating.

The reason behind that acceleration is what matters, and Levchin described it himself in the most recent shareholder letter. Affirm is a network, and the defining property of a well-built network is that the cost of staying out of the network rises as the network grows. Consumers increasingly expect to see Affirm on a merchant’s checkout page, and every additional merchant gives a consumer one more place to buy with Affirm. The two sides feed each other – the merchant that stays away from Affirm to save on fees pays in lost sales.

Well-managed networks see very little churn. In fact, Affirm’s merchants have expanded their volume at a dollar-based net expansion rate averaging 120% over the past three years – so if Affirm never signed another merchant, the existing base alone would grow the network by 20% a year. Every new Affirm merchant is upside on top of a base that compounds by itself.

The second effect is what makes Affirm stand out over the traditional card network. When a merchant offers Affirm at checkout, it hands Affirm its customers. To state the obvious… each of the 28 million consumers using Affirm has an Affirm account and a repayment history on Affirm’s ledger. Increasingly, they also have an Affirm Card in their wallet.

Affirm paid nothing to acquire any of them. The merchants paid Affirm – the discount rate on the first transaction is the acquisition cost – that means Affirm has a negative customer acquisition cost. Merchants accept this because they would rather Affirm be the bad guy so they don’t have to send their own customers a late notice. The merchant introduced their customers to Affirm. Affirm owns the relationship. Now, once a consumer has repaid the loans through Affirm, Affirm can offer them the next product.

The same mechanism is now doing Affirm’s international expansion for it. Shopify, for example, carries Affirm into each new market as the exclusive provider behind its Shop Pay Installments – Canada and the U.K. in 2025, Australia at the end of August, then Western Europe – and every Shopify merchant in those countries can switch it on from their admin dashboard without an integration. Affirm arrives in a new country with a merchant base already attached, and acquires local consumers the way it acquired American ones: paid to do it.

The Affirm Card: The Walmart Test Case

Walmart is the proof point. In 2019, the giant, low-price retailer was one of the first enterprise merchants to integrate Affirm, and it built its financing offer around it. By late 2024, Walmart was roughly 5% of Affirm’s GMV and about 2% of adjusted operating income. Then in March 2025, Walmart’s fintech arm, OnePay, signed leading BNPL platform Klarna Group (KLAR) as exclusive installment provider and moved the checkout. Affirm shares fell 10% on the news, and the transition was substantially complete by the September 2025 quarter.

Conventional wisdom would say that if a major retailer ends access to your product, your sales will suffer significantly. But what happened next is the most important data point in the Affirm story. At Affirm’s investor day this May, CEO Levchin said Affirm did not lose volume at Walmart. A large majority of Walmart shoppers who had been using Affirm at its checkout got Affirm Cards and kept using Affirm – online and in the aisle – with no direct Walmart integration at all.

The Affirm Card is a Visa debit card that lets a consumer pay in full from a linked account or turn any purchase into an Affirm BNPL loan on the spot. Because it runs on Visa’s rails, it works at every merchant that accepts Visa, whether or not that merchant uses Affirm (more on the Affirm Card below). Walmart had introduced its customers to Affirm. Affirm kept them, and carried them straight back into Walmart’s own aisles.

Affirm volume at Walmart continues to grow despite the termination of Affirm’s contract. Klarna reports that its Walmart business is running in line with expectations. Both can be true. The point is not that Klarna failed. It is that the consumer relationship, not the merchant contract, turned out to be the asset – exactly what Hock’s framework predicts.

What the Walmart example demonstrates is that merchants no longer need to be sold. Since April, Bed Bath & Beyond, Crate and Barrel, and ServiceTitan have gone live, Etsy has signed, and Samsung has renewed. The merchant without Affirm is now the one with the conversion problem. And the network is nowhere near full. Affirm is present on about 80 of the top 250 U.S. e-commerce sites, and only about one in 10 U.S. e-commerce merchants offers it.

Dee Hock had hoped Visa would evolve from a credit card – an instrument of debt – into a transaction device for the exchange of value. The banks that owned Visa chose interest instead. Walmart demonstrated what Affirm’s consumers are worth once they carry the Affirm Card with them. That is the second growth vertical, and it is the card Hock never got to build.

Serial S-Curves: The Affirm Card

Each of Affirm’s businesses has followed an S-curve – slow adoption while the product finds market fit, a steep run of growth as it catches on, then a plateau as the market matures. Checkout is well up its curve. The Affirm Card is the second, and it is on the steep part right now.

The card brings Affirm’s model – per-transaction underwriting – to the physical world, where roughly six times as much spending happens as online. It works as a debit card for everyday purchases, but any eligible purchase over $50 can be converted into an installment plan from the Affirm app within 48 hours, and a consumer can also set up a plan in the app before walking into the store.

Card GMV grew 124% last quarter to an annualized run rate above $11 billion – about 22% of the total – and active cardholders doubled to 5.2 million. Before the card, using Affirm in a store meant opening the app, generating a virtual card number, adding it to a phone wallet, and tapping. The card established Affirm’s presence in the physical world. Offline volume has more than doubled year over year in every quarter since the card began scaling in 2023.

The Affirm Card is still in its early innings. Cardholders spend roughly $4,000 a year on Affirm, more than twice the average active consumer. And only 19% of active consumers have signed up for an Affirm Card, and the ones who have spend double – the steep part of the curve is ahead.

The card also told Affirm where to go next. Cardholders began using it for elective medical procedures, professional services, and automotive repairs – categories with no Affirm integration and, historically, no good financing. Affirm is now building direct integrations in each category. Volume from those verticals is in the billions annually and growing at twice the rate of the overall business: professional services up 74%, elective medical up 85%, automotive up 140% in Q2 of 2026.

There is a third opportunity within the Affirm Card – and it could take it from 5 million holders to 20 million. In August, Levchin promoted Michael Linford from chief operating officer to president – freeing the founder to spend more time with a small team, known internally as zt1 (Zero-to-One), that works exclusively on early proofs of concept.

The shape of it is already visible. Merchants now pay to reach Affirm’s consumers directly. The Affirm app hosts a marketplace where brands fund 0% offers to be featured, and twice a year Affirm runs the Big Nothing – a network-wide sale, modeled on Amazon’s Prime Day, where participating merchants offer 0% APR (annual percentage rate) on purchases made with Affirm, and pay for the privilege by absorbing the interest. The second Big Nothing drew twice the merchants of the first and generated roughly $500 million of GMV in a few days.

That is an advertising business in its infancy: 28 million consumers Affirm can underwrite individually, and merchants pay Affirm for demand. The next step is to route that merchant funding into rewards on the card. Rewards bring more consumers onto the card, consumers are what merchants pay Affirm to reach, and the underwriting loop tightens as Affirm processes more transactions. Affirm’s long-term goal is an everyday payment card with 20 million cardholders spending $7,500 a year – $150 billion of GMV from the card alone, three times Affirm’s entire network today.

This is what the vertically integrated, data-preserving, software-defined network was built for – managing, aggregating, mining, and modeling data, and around preserving all of it. Its successful implementation means merchants and consumers hand Affirm far more to work with than any other payment network receives. The payoff is that a very large set of possible applications can be built on top of this foundation.

The Bank Option, And How Affirm Funds Itself Today

Every loan Affirm makes has to be funded, and how it is funded is the difference between a lender and a network. Affirm uses three channels.

  1. Warehouse lines – revolving credit facilities from banks, secured by the loans themselves – fund the loans Affirm keeps on its balance sheet. Affirm draws as it originates and repays as borrowers pay, the way a retailer finances inventory
  2. Asset-backed securities (“ABS”) package those loans and sell them to bond investors, in both revolving and one-off static deals
  3. Forward-flow agreements sell whole loans to partners such as Canada Pension Plan Investment Board, which take the assets off Affirm’s books entirely and pay Affirm to service them

At the end of June, committed capacity across the three stood at $30 billion, up from $26 billion a year earlier – enough on the platform’s five-month weighted-average loan duration to support more than $70 billion of annual GMV.

Affirm’s loan book turns over roughly twice a year, which means Affirm’s cost of funding tracks the market within quarters. When rates rose in 2022 and 2023, funding costs jumped and margins compressed almost immediately. When Affirm repriced its loans, the recovery came just as fast. A bank with a 30-year mortgage book cannot do that, but a network with a five-month duration book does it naturally.

It is a lender with a bank’s volume and a software company’s capital base. Affirm’s total platform portfolio – every loan outstanding, on its books or sold – was $20.2 billion in June. Of that, Affirm funds just $896 million with its own equity, an equity capital required ratio of 4.4%, and management guides to keeping it at or below 5%. A conventional bank holds roughly twice that against its loans. Affirm also carries $1.5 billion of net cash against its convertible notes. And the price of that capital keeps falling. The credit spread on Affirm’s revolving ABS deals has decreased from a range of roughly 240 to 310 basis points in 2023 to about 95 to 110 basis points in 2026 – a decline of some 175 basis points in three years. Average cost of funds fell 103 basis points in the past year to 5.8%. The most recent static deal, in June, was four times oversubscribed and priced at the best blended spread of any Affirm securitization to date, the fourth in a row to clear with a duration-weighted yield below 6%.

Affirm publishes the loss curve for every static securitization it has issued since 2023 against the loss investors assumed when they bought it. In all six deals, realized losses have tracked at or below pricing. Bond investors are being paid for risk that has not materialized, and they respond the way anyone would – by bidding tighter next time. Forward-flow partners also respond by expanding. Year-end forward-flow capacity has grown from under $1 billion in 2021 to nearly $11 billion in 2025, and the investors who signed in 2021 are still adding capacity four years later. It is the merchant retention story again, this time in the debt markets.

Now Affirm is gaining distribution through the banks themselves. Affirm Edge embeds Affirm’s installment lending directly inside bank and credit union apps, with pilots launching in early 2027 and a $140 billion addressable market by management’s estimate. In 2022 the thesis was that the Affirm Card would compete with bank debit cards. But Affirm Edge becomes the pay-over-time layer inside the bank’s own card. The institutions that were supposed to crush this business are becoming its distribution channel, while Affirm keeps the origination, the servicing, and the data.

Since its founding, Affirm has originated most of its loans through a partner bank and in its prospectus it named that dependency as a risk factor and deposit funding as the structural advantage its bank competitors held. On January 23, Affirm applied to the Federal Deposit Insurance Corporation (“FDIC”) – a federal agency that protects accountholder deposits – and the state of Nevada to establish Affirm Bank, a Nevada-chartered industrial loan company, with John Marion, a JPMorgan Chase veteran, as its president.

If approved, Affirm would originate its own loans and, over time, fund a portion of them with insured deposits rather than capital markets. Management’s near-term estimate of the benefit is modest – on the order of 15 to 30 basis points of originated volume. The ceiling is considerably higher: every 100 basis points of funding cost saved across the roughly $10 billion Affirm funds on its own balance sheet is about $100 million of pre-tax income, against $417 million of operating income today. The application is pending in the friendliest charter environment in two decades, with leading car manufacturers General Motors (GM) and Ford Motor (F) both winning FDIC approval the day before Affirm filed.

The comparison is the architecture behind the most durable consumer finance franchises in America, American Express – a payments network attached to a deposit-funded bank. Neither path contributes revenue today, but either could be the next S-curve down the line.

Affirm’s Growth: Fueled By Network Effects

Affirm has reached the point every network builds toward – where the majority of fixed investment is behind it, and growth converts to profit at the incremental rate rather than the blended one. Every projection here reduces to two variables: how much volume crosses the network, and how much of each dollar Affirm keeps.

In fiscal 2026, Affirm processed $50.2 billion of GMV and collected $4.26 billion of revenue – 8.5 cents per dollar, half of it interest income, a quarter merchant fees, the rest loan sales, card, and servicing. Four costs scale with volume: credit losses, processing, funding, and the loss on loans purchased from its originating bank. Those costs consumed 4.3% of revenue. What remains is revenue-less transaction costs (“RLTC”) – $2.08 billion, or 4.15% of GMV, earned after absorbing credit losses the card networks never touch.

RLTC is the closest thing Affirm has to a traditional revenue line, and it shows both faces of the business. In fiscal 2023, the interest rate shock pushed funding costs up faster than Affirm could reprice, and RLTC fell from 4.3% of GMV to 3.3% in a year – the lender’s dilemma. Because the book turns over every five months, Affirm repriced loans within quarters, and RLTC recovered to 4.2% – the network’s answer.

The same shock produced Affirm’s largest operating loss – $1.2 billion in fiscal 2023. Three years later, the same business model the market had written off produced $417 million of operating profit, a $1.6 billion swing. From fiscal 2024 through fiscal 2026, roughly 53 cents of every incremental revenue dollar reached the operating line – about $44 million of operating profit for every additional $1 billion of GMV.

Incremental margin – the change in adjusted operating income over the change in RLTC – ran 81% in fiscal 2025 and 76% in fiscal 2026. The ledger, the risk models, and the merchant integrations are built and paid for. Lenders scale costs with their book. Networks do not. That is why Affirm’s adjusted operating margin went from 16% of revenue to 29% in two years – and why, in our base case, operating income will more than quadruple by fiscal 2029, to roughly $1.9 billion on a 21% margin.

The volume is still arriving – Affirm will add as much GMV in fiscal 2027 as it processed in all of fiscal 2022. Affirm trades at roughly $25 billion today – about 12x trailing RLTC and 9x fiscal 2027. Our $60 billion base case is 14x fiscal 2029 RLTC, on a business that will have doubled and still be growing 25% a year.

We ran five RLTC paths through the same volume and cost assumptions. The matrix shows what each is worth per share across a range of RLTC multiples, against $70 today and 370 million diluted shares.

At 12x – today’s multiple – Affirm is worth $139 per share on fiscal 2029 RLTC: 86% above the current price, a 28% annualized return to the target date. At 14x, the multiple behind our $60 billion target, it is $162 and 35% a year. On a price-to-earnings equivalent, a $139 share price implies 33x normalized fiscal 2029 earnings compounding at roughly 40% a year, or 23x adjusted earnings. For a business growing that fast – on infrastructure already built, and paid for through a decade of reported losses – that is not a demanding multiple.

At 8x – the trough multiple a credit shock would produce – the bear case is $80, still above today’s price. The market is pricing Affirm as though fiscal 2029 will look like the bear case and the multiple will decline on the way there while our base case requires neither.

None of the five paths includes 20 million Affirm Card holders, Affirm Edge, or the rewards engine. Those are the reasons the range may prove conservative.

The 30-Year Mission

Dee Hock wanted two things Visa never accomplished. He wanted the merchant and the consumer inside the network as members rather than paying tolls outside it, and he wanted the card to be an exchange of value rather than an instrument of debt. The banks that owned Visa refused both, pushed him out in 1985, and built a $700 billion company on the design its founder called a failure. Hock explained it this way:

I could devise no way to include cardholders and merchants as owner/members of the system. They should have been, for they are certainly relevant and affected parties.

Levchin has called Affirm his 30-year mission, and the company is 14 years into it.

The first half built what Hock could not: a ledger that underwrites every transaction on its own, merchants that pay to bring Affirm their customers, consumers who carry the network in their wallet, and funding partners that bid tighter every year.

The second half is the card Hock described in 1968 – an everyday payment card in 20 million wallets, funded by deposits from Affirm’s own bank, reaching up-market into affluent households whose spending the card networks built their economics on. Every party Hock wanted inside the network is inside it, on one ledger, and each is better off in the network than left out. This is what the early stage of a true network looks like: GMV compounding at nearly 40%, 571,000 merchants, and nearly 30 million consumers.

The person who has to finish the job is the one who started it. Levchin is 50, has run Affirm since 2012, and controls it – roughly 8% of shares outstanding, while controlling 44% of the voting power. In August he handed daily operations to a president so that he could go back to building products from zero. His net worth is tied to the stock, and his job is the next S-curve – he literally only wears Affirm branded merchandise.

Today a merchant pays the card networks a toll to get paid. On Affirm, the merchant pays for demand – Peloton funded 0% because it sold bikes, and in the Big Nothing campaign, merchants across the network funded 0% and paid Affirm for the traffic. That is an advertising business in its infancy, and unlike any other advertising platform, Affirm knows not only who wants to buy but who will be approved, and can make the offer in the same second.

The consumer side is the mirror image. Route that merchant funding into rewards on the card, and more consumers carry it into their daily spending. Approved consumers are exactly who merchants pay most to reach, because on Affirm the merchant is buying a sale it would otherwise have lost.

Everyday spending is the volume the card networks have never had to earn – and it is the volume Affirm is building the rewards to take. The value of a network is that merchants feel they have to be a member. Max Levchin is building this network with the owners he chose, and at less than $25 billion the market is pricing it as a lender and not a network.

Action to Take: Buy Affirm (Nasdaq: AFRM) up to $92 per share

Affirm is among the most volatile large stocks in the market – it fell 10% in one day on the Walmart news, and the shares have traded between $42 and $92 in the past 12 months. We recommend patiently sizing the position so that a 30% drawdown is survivable, because one will come, and the thesis will not have changed if it does. We are assigning Affirm a risk rating of 4 and will add it to the Exponential Growth category.


Review Of Recommendations

This month’s “buy” recommendations:

  • LandBridge (LB)
  • Amrize (AMRZ)
  • Uber Technologies (UBER)
  • Salesforce (CRM)
  • Vicor (VICR)

This month’s existing “hold” positions:

  • Deere & Company (DE)

This month’s new “hold” positions:

  • Axis Capital (AXS)
  • Chubb (CB)
  • International General Insurance (IGIC)
  • Kinsale Capital (KNSL)
  • Loews (L)
  • Progressive (PGR)
  • Skyward Specialty Insurance (SKWD)
  • W.R. Berkley (WRB)

LandBridge Thriving On Higher Oil Prices, With Data Center Upside

The West Texas landlord, LandBridge (NYSE: LB), reported excellent Q2 results on August 5. Revenue increased 41% year-on-year (“YOY”) to $67 million, while net income jumped 68% YOY to $31 million. Cash flow margins reached 60% with the company generating $40 million in free cash flow during the quarter.

The company is benefitting from the acceleration in U.S. drilling activity in response to higher oil prices. Domestic oil production recently set a new high of 13.9 million barrels per day, led by supermajors like Chevron (CVX) and ExxonMobil (XOM) in the Permian Basin. The increased drilling activity in the Permian is driving greater volumes of produced water in the basin, translating into higher royalty payments for LandBridge.

LandBridge reiterated its 2026 outlook for EBITDA (earnings before interest, taxes, depreciation, and amortization) to reach $220 million. It also announced advanced discussions with seven counterparties representing over 10 gigawatts of power and data-center capacity for land leasing deals. LandBridge CFO Scott McNeely characterized these as projects with signed documents undergoing diligence or agreements currently under negotiation, rather than preliminary outreach. He also noted that the counterparties include a mix of hyperscalers, engineering, procurement companies, and power-generation businesses.

Management expects that “multiple” of these negotiations could convert into firm leases with revenue beginning to flow in by the end of next year, although no formal deals have been announced. West Texas has become home to one of America’s hottest spots for data-center construction, given the abundance of dirt cheap fuel via natural gas – which often trades at negative prices due to lack of pipeline takeaway capacity. And as one of the largest landholders in the area, LandBridge is perfectly positioned to capitalize on this boom.

With the core business performing exceptionally well, and the future upside potential from data-center leasing activity, we remain bullish on shares of LandBridge.

Action to Take: Buy LandBridge (NYSE: LB) up to $104.31 per share

Inflation Continues Weighing On Amrize

Concrete and aggregates maker Amrize (NYSE: AMRZ) continues facing the same macro pressures weighing on the overall sector: commodities inflation pushing up costs. In the company’s latest Q2 earnings report on August 6, management lowered its earnings outlook as a result of $155 million in added cost inflation it expected for the full year. Since then, oil prices have risen 33% while diesel prices have jumped to a new high above $200 per barrel.

Meanwhile, interest rates have also increased substantially, with the 10-year U.S. Treasury yield hovering near multi-decade highs of 5% while mortgage rates are firmly above 7%. This has added further downward pressure on an already-weak housing market, a major source of demand for concrete and aggregates.

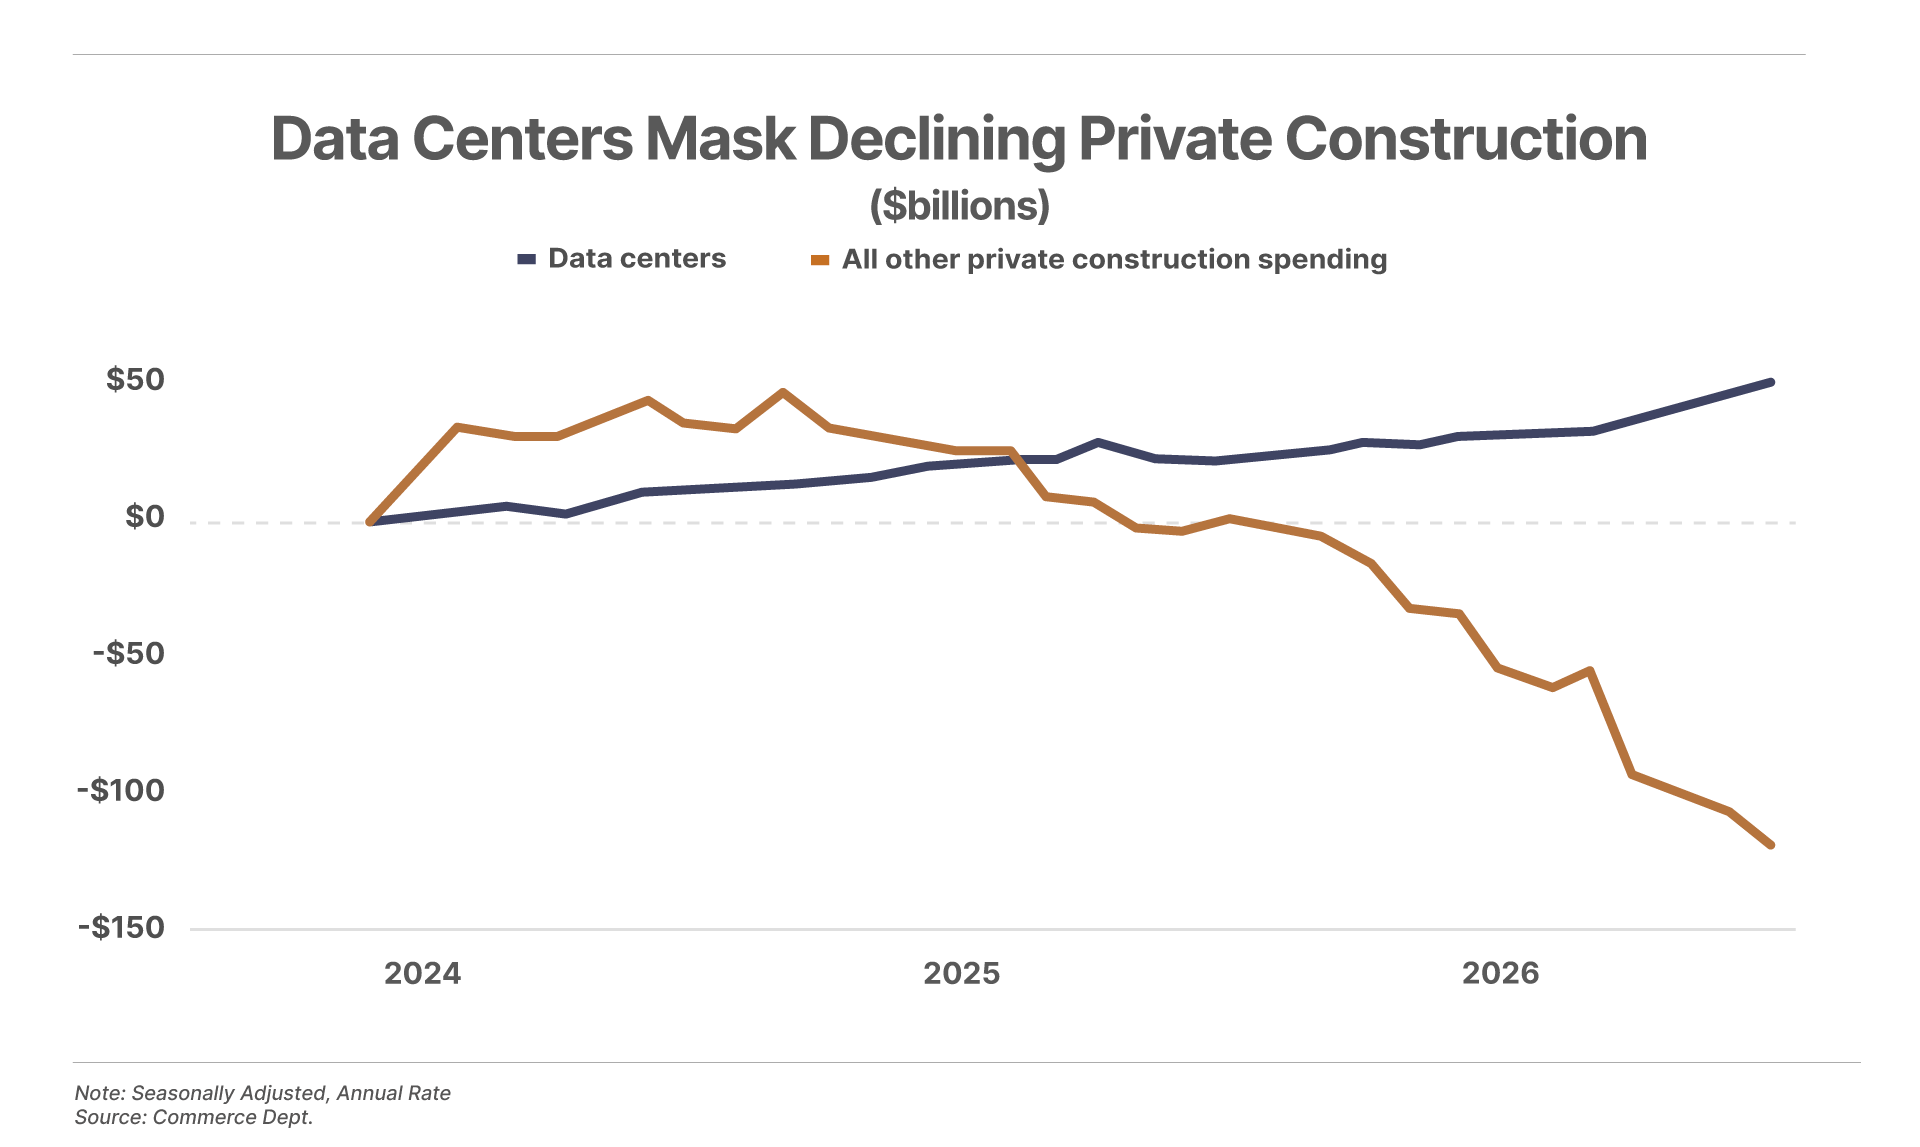
But it’s not all bad news. On the plus side, the data-center build-out shows no signs of slowing, as AI capex estimates continue getting revised higher. Following the latest Q2 earnings results from the leading technology companies, data-center spending is expected to eclipse $1 trillion this year and $1.3 trillion in 2027. Strength in data-center construction is offsetting the weakness in residential housing and non-AI construction, and we expect this trend to continue fueling overall growth for Amrize revenue.

Putting it all together, we see a mixed picture for Amrize over the next several quarters. The strength in data-center spending will likely keep revenue growth trending solidly at mid-single-digit rates. But rising costs will weigh on margins, with analysts lowering their earnings estimates by 8% over the past several weeks for both 2026 and 2027.

Amrize shares are down 30% this year, and now trade at just 13x forward earnings – the lowest valuation on record, and a substantial discount to peers like Vulcan Materials (VMC) and Martin Marietta Materials (MLM) that trade at low-20s forward price-to-earnings (P/E) ratios. Thus, we believe the near-term margin pressure has been more than priced in, with the shares offering significant value for long-term investors willing to look through the next few quarters of weak earnings. Insiders also apparently see value here, with seven insider buys since August, totalling over 50,000 shares at prices in the mid-$40 range.

We remain bullish on the long-term potential of the business once today’s commodities inflation passes.

Action to Take: Buy Amrize (NYSE: AMRZ) up to $73.80 per share

Uber Execs Buy Shares As The Stock Retreats

Two of Uber Technologies’ (NYSE: UBER) top executives bought stock on the open market this month. On September 4, President and Chief Operating Officer Andrew Macdonald purchased $5.3 million of shares at prices about 6% above where the stock trades today. On September 10, CEO Dara Khosrowshahi bought $10 million at prices within 2% of today’s, on a day the shares touched their lowest level since early August. Speaking at a Goldman Sachs conference that afternoon, Khosrowshahi said U.S. mobility demand has accelerated since late last year, and that management considers the stock “really cheap.”

The purchases followed a September 2 restructuring that cut roughly 3,300 corporate roles, about 10% of Uber’s global workforce and its largest reduction since 2020, to remove management layers and redirect spending toward rides, delivery, and autonomous vehicles (“AV”). Rather than keep the savings as margin, Khosrowshahi said Uber will reinvest it, along with declining insurance costs, in lower rider prices and growth.

Uber is also pressing ahead with its largest acquisition. In July, it agreed to acquire German food-delivery platform Delivery Hero for $14.8 billion in cash, or $13.7 billion net of the stake Uber already owned. The offer document was published on August 27, opening an acceptance period that runs through November 5, and on September 2, Delivery Hero’s board recommended that shareholders tender. Uber expects the deal to add to non-GAAP EPS on closing, rising to high-single-digit accretion by year three, and to nearly double the number of markets where it offers both rides and delivery, from 34 to 58. Completion, which requires antitrust clearances, is expected in the second half of 2027. On September 15, Uber closed its first euro-denominated bond offering, raising €4.5 billion (about $5.2 billion) across five maturities from 2029 to 2046 at coupons of 3.75% to 5.25%, versus more than €21 billion in orders.

The AV network kept expanding. On August 19, the Croatian city of Zagreb became the first in Europe where riders can book an autonomous ride through the Uber app, using Pony.ai (PONY) technology with a safety operator on board. On September 10, the operator began fully driverless test rides on an airport route. Khosrowshahi said Uber now works with nine AV partners and expects 15 by year-end. Competition is arriving too: Tesla (TSLA) began charging fares for its two-seat Cybercab in Austin on September 3, with about 45 vehicles registered, and Uber’s shares fell 3.5% on September 8 as investors weighed the launch. Alphabet’s (GOOG) Waymo has reportedly told Uber it plans to operate on its own in Austin and Atlanta from January 2028, when their agreement allows.

Shares trade nearly 30% below the 52-week high set last September, while Q2 gross bookings grew 24% YOY and trailing 12-month free cash flow exceeded $10 billion for the first time. Since our January 2025 recommendation, the stock has gained roughly 6%.

Action to Take: Buy Uber Technologies (NYSE: UBER) up to $100.38 per share

AI Fears Give Way To AI Profits For Software

Leading enterprise software company Salesforce (NYSE: CRM) has clawed back much of the ground it lost earlier in the year. Investors haven’t forgotten the scale of the selloff: software-as-a-service stocks shed $285 billion in market cap in a single February session, and the iShares Expanded Tech-Software ETF (IGV) fell 35% from its 2025 high by April, as the market grappled with the idea that AI is eating software.

After bottoming out in June, Salesforce has regained roughly 70% of that loss. The turnaround coincides with a shift in the narrative: instead of asking whether autonomous agents will cannibalize Salesforce’s seat-based licensing model, investors are now digesting hard evidence that the company is monetizing AI directly, and that the survivors of this paradigm shift will end up more valuable than the old software incumbents ever were.

Salesforce has pivoted its pricing structure toward consumption-based billing, charging per automated task completed rather than per human worker.

The centerpiece of that shift was Claudeforce, an expanded partnership with leading AI platform Anthropic announced alongside earnings that makes Anthropic’s Claude the default reasoning model across Agentforce and Slack, while turning Salesforce into a plugin inside Claude itself. The relationship already runs deep enough that Salesforce expects to spend around $300 million on Anthropic tokens this year, on top of a stake in Anthropic now valued at about $5 billion.

Salesforce’s fiscal Q2 2027 results (released August 26) showed revenue of $11.3 billion, up 11% YOY, but net income of $3.53 billion – with earnings per share (“EPS”) of $4.29 – jumped 87% from a year ago, with the company pointing to a $2.6 billion gain on strategic investments from its Anthropic stake. Stripping out that gain, the underlying business still accelerated: current remaining performance obligations grew 14% YOY in constant currency to $33.5 billion, the strongest quarter for net new annual order value in four years. Agentforce annualized revenue crossed $1.5 billion, up 240% YOY – an acceleration from the roughly 205% pace of Q1.

Management raised full-year revenue guidance to $46.1–$46.4 billion and hiked full-year EPS guidance to $16.67–$16.71, up sharply from the $13.11–$13.19 range given back in February. Salesforce has since closed its $3.6 billion acquisition of customer-agent platform Fin, with the Contentful deal expected to close shortly, and Dreamforce 2026 kicks off this week in San Francisco under the banner “Becoming The Agentic Enterprise,” where the newly announced Salesforce-in-Claude plugin moves into open beta.

The capital-return story we highlighted after Q1 has only gotten more aggressive. Salesforce plowed a record $27.1 billion into buybacks in Q1 as part of its $25 billion accelerated repurchase program, part of a $50 billion board authorization, and continued repurchasing shares in Q2 – pulling the diluted share count down 14% to roughly 821 million. Even after the rally to around $256 per share, Salesforce trades at roughly 17x forward earnings on its newly raised guidance, well below Microsoft’s and Google’s 25x, despite comparable AI-driven revenue growth. That’s still a multiple that prices in a fair amount of disruption skepticism the last two quarters have started to disprove.

Action to Take: Buy Salesforce (NYSE: CRM) up to $263 per share

Vicor Buys The Land For Fab 2 and Fab 3

On September 11, power-systems producer Vicor (Nasdaq: VICR) announced it is purchasing a 334,000 square foot building on 66 acres in Merrimack, New Hampshire, and a separate 54-acre parcel in Hooksett, New Hampshire. The two sites will house ChiP Fab 2 and Fab 3, with a combined footprint of nearly 1 million square feet. Fab 1 in Andover, New Hampshire, is 320,000 square feet on 16 acres, and its utilization is approaching capacity.

Two details matter for our thesis. First, Vicor put a one-year lead time on initial deployment of Fab 2, which moved the expansion date up from 2028 to late 2027. Second, Fab 3 is new. On the July earnings call CEO Patrizio Vinciarelli described a second fab sized at two to three times Fab 1. Friday’s release describes two fabs on two sites, and the acreage supports a build-out roughly four times the size of Fab 1 over time.

The scale of the commitment makes more sense in light of two earlier comments from management. At the June annual shareholder meeting, Vinciarelli said second-generation vertical power delivery (“VPD”) would fill not just one fab but “a multiplicity of fabs.” And on the Q4 2025 earnings call, he disclosed that one customer alone represents enough volume to fill two fabs. That customer is not named, but the profile – massive AI hardware volume and in need of a non-infringing power solution with U.S. sourcing – points to Nvidia (NVDA).

The release also restates the licensing case in Vicor’s own words. It says original equipment manufacturers (“OEM”) and hyperscalers whose systems were banned from importation need freedom to operate and U.S. sourcing, and that Vicor’s licensing practice plus multiple fabs provide both.

On September 16, Vicor disclosed a non-exclusive VPD license to “a leading AI OEM” with the right to procure modules from unlicensed suppliers – paying royalties on all of them, with substantial discounts for buying Vicor’s own chips directly. Five days after the fab sites, this is the licensing design win that confirms the demand behind the capacity build.

The announcements follow an August 25 board authorization of a new $150 million share repurchase program with no expiration, replacing the prior $100 million plan. With $454 million in cash at the end of June, Vicor can fund the fab build-out and retire stock at the same time.

This is a capacity and demand signal. We have moved Fab 2 forward a year in our model, added Fab 3 to the bull case, and updated our long-term range of outcomes above. Our recommendation is unchanged.

Action to Take: Buy Vicor (Nasdaq: VICR) up to $275 per share

Deere Raises Guidance And Reiterates The Bottom Of The Farm Cycle

On August 20, Deere & Company (NYSE: DE) reported Q3 net income of $1.38 billion, or $5.10 per share, up 7% from a year ago and above the $4.70 consensus estimate – its first YOY profit increase since Q4 2023, after 10 consecutive quarterly declines. Net sales and revenue rose 5% to $12.6 billion. Management raised full-year net income guidance to a range of $4.75 billion to $5 billion from $4.5 billion to $5 billion, and repeated its view that 2026 will mark the bottom of the agricultural equipment cycle.

Construction and small-agriculture equipment again offset weakness in large farm machinery. Construction & Forestry sales rose 18% to $3.6 billion, and segment operating profit climbed 84% to $436 million, driven by data-center, infrastructure, and pipeline work, with order backlogs now extending into fiscal 2027. Small Ag & Turf sales rose 12% to $3.4 billion. Production & Precision Agriculture, the large-tractor and combine business, fell 6% to $4.0 billion as South America and Europe softened further. Deere now expects that segment’s sales to decline about 10% this year, the bottom of its prior range. Results also included $110 million of refunds on tariffs the Supreme Court struck down in February – $382 million so far this fiscal year – a one-time item that will not repeat in Q4 and that accounts for most of the quarter’s YOY gain.

Early orders for model-year 2027 planters and sprayers are running up mid-single digits versus last year’s completed programs. Used inventories of late-model high-horsepower tractors are down nearly 40% from a year ago, and the spread between new and used equipment values has normalized. Management still describes the coming recovery as measured, and expects net tariff costs to approach $1 billion in fiscal 2027, up from an estimated $750 million this year as refunds fall away.

On July 8, Deere settled the Federal Trade Commission’s right-to-repair lawsuit, agreeing to a 10-year order that gives farmers and independent repair shops the same diagnostic and software tools its dealers use, with no monetary penalty. That closes the government’s case, which had remained open after the $99 million class settlement we noted in April.

Deere paid $1.62 quarterly dividends in May and August and declared another $1.62 payable November 9. Share repurchases totaled $697 million through nine months, down from $1.1 billion a year ago.

Shares have gained 44% this year and 67% since our September 2023 recommendation, including dividends.

At nearly 40x the midpoint of this year’s guided earnings, the shares already discount much of the recovery management is describing.

Action to Take: Hold shares of Deere & Company (NYSE: DE)

Stepping Back From Property-And-Casualty (“P&C”) Insurance Companies

In Tuesday’s Daily Journal, Porter explained a major asset-allocation change to Porter’s Permanent Portfolio – recommending selling P&C stocks from the portfolio. For Complete Investor, that recommendation translates into “hold” status. He explained it this way:

The 10-year U.S. Treasury yield hit 5% on Monday, September 14, driven by soaring energy prices, the widening war with Iran, and a bond market losing patience with Washington’s deficits.

Then, on Wednesday, September 16, the Fed announced a 25-basis-point rate hike, meaning we’re at the beginning of a rate-hiking cycle.

There are real risks to this cycle because of the size of the national debt. Total marketable U.S. Treasury debt outstanding is $31.8 trillion, and roughly half of that will reprice in the next 18 months.

If rates average 5%, that will add $220 billion in annual interest expense – a 21% increase to current interest expense ($1 trillion currently). It would also add 12% to the annual deficit. These bigger interest payments will surely be paid for by yet more inflationary government deficit spending.

That will push us into a very dangerous situation. The Fed may not be able to raise rates high enough to stop the inflation this time because our debt stock is now so large relative to GDP.

The main concern is that this inflationary cycle may be much harder to control, because it’s being driven by factors (entitlement spending, global geopolitics) that aren’t easily constrained. And that kind of macro outlook appears similar to the 1973-1974 inflationary period, which didn’t resolve for a decade.

That means our P&C insurance stocks face a very tough outlook.

P&C insurers write the policies that cover your car, your home, and your business against loss. They invest the premiums they collect, called float because it sits in their account between the day you pay and the day a claim gets paid. And insurance companies invest mostly in bonds.

That business model works well when rates and inflation are calm. It comes apart when they spike, for three reasons that hit at once: claims get more expensive, the bonds that insurers already own lose value, and the stock market’s current multiple shrinks.

For a conservative investor, our recommendation is simple: stand aside from the P&C insurance industry until interest rates find a ceiling.

For our own track record in Porter’s Permanent Portfolio, we are selling our 25% P&C allocation (“Insurance”) in full. The proceeds move into our cash holdings, whose target allocation rises from 25% to 50% of the portfolio. The Lindy stocks (“Equities”) and the gold-and-Bitcoin allocation remain at 25% each. For Complete Investor, we change their status to “hold.”

In that Journal explaining this change in the portfolio allocation, Porter said this:

We acknowledge that this kind of tactical move is risky. Selling triggers taxes and opens us to another risk: selling too soon. I recognize the 10-year U.S. benchmark yield touched 5% in 2007 and again in 2023, and both times it reversed. If that happens a third time, we will look foolish holding half the portfolio in cash while stocks and bonds recover without us.

I see a slew of risks that our country hasn’t faced in 50 years: massive and growing deficits, an energy shock now running through the global bond market, and the automatic cost-of-living increases built into Social Security and other entitlement programs. Together they point toward double-digit inflation and a 10-year Treasury yield above 8%, not a retreat below 5%.

This change applies to our own track record, not to every account built around this idea. The Porter & Company Porter Portfolio Index ETF (PCPP) that Tuttle Capital Management runs keeps its rules-based 25% allocation to each of its four sleeves. And your own allocation may not need to change either, depending on your tax situation, your time horizon, and how much of this risk you are already hedging elsewhere.

Check out the full list of recommendations here.

Porter & Co.
Stevenson, Maryland

For important disclosures and disclaimers, please visit our Legal Disclosures page.

The post The End Of The Credit Card Cartel appeared first on Porter & Co..
  • ✇Porter & Co
  • The Second Secret Dividend Can Make You Rich… Or Ruin You Porter &#38 · Co.
    Issue#162, Volume#3 Edit Delete Edit Delete Four Companies That Are Paying Them In The Right Way Inside Today’s Issue Essay: The Second Secret Dividend Can Make You Rich… People Are Staying Unemployed Longer ExxonMobil Shuts Down Key Diesel Refinery Meta Goes “junk” Chart Of The Day… Sabre (SABR) Today’s Mailbag Edit Delete Editor’s note: Before we get into Porter’s Journal for today, we want to share his new Ignition Point broadcast. In the newly released video, he revea
     

The Second Secret Dividend Can Make You Rich… Or Ruin You

18 September 2026 at 13:00

Issue#162, Volume#3

⚙ Edit 🗑 Delete
⚙ Edit 🗑 Delete

Four Companies That Are Paying Them In The Right Way


⚙ Edit 🗑 Delete

Editor’s note: Before we get into Porter’s Journal for today, we want to share his new Ignition Point broadcast. In the newly released video, he reveals how several separate technological forces are fusing to create what Porter calls “the next Mag7.” Watch it here.


Yesterday I wrote to you about “secret” dividends.

These are the huge sums of corporate profits that end up being allocated to things besides cash dividends. Finance bros call these decisions “capital allocation,” and they frequently make all of the difference between a winning investment and a losing one. After all, only about 35% of corporate earnings come back to you directly in dividends. Most of the cash ends up in other places.

One thing a good management team will do with these funds is pay the second kind… a secret dividend. This is a way of returning capital to you – but it’s a dividend that never shows up in your brokerage account. There isn’t a record date. There isn’t an ex-dividend date. There is no particular time limit to benefit from these dividends and they’re not announced – you can’t know exactly when they will be paid. You just have to keep track of them by watching the company’s share count. If they’re paying a lot of these kinds of secret dividends, then the share count will fall. And, as a result, your ownership interest will grow over time.

That can make you extremely rich. But these kinds of secret dividends can also ruin you. The difference comes down to one question to ask:

Do You Trust The People Running The Company?

When a company sends out 90% of its cash as a normal dividend, there is less room for management to hurt you. You get the money. You decide what to do with it. But when a company keeps the cash… borrows more money… and buys back stock… you are handing your checkbook to the people in the boardroom. You are trusting them to know what the business is worth. You are trusting them to tell the truth about the cash. You are trusting them not to borrow too much. You are trusting them not to buy stock just because it makes the next quarter look better.

That is why the second secret dividend – share buybacks – is so powerful. And that is why it is so dangerous.

When it goes wrong, it can destroy even the biggest and strongest business in the world.

Look at General Electric (GE). By the year 2000, under Jack Welch, GE was the most valuable public company in the world. But just eight years later, GE had taken on so much debt that it was one of the biggest borrowers on Earth – it owed more than $700 billion, making it the 10th largest sovereign borrower in the world! Think about that. GE is not a country!

These enormous debts meant shareholders were not merely trusting GE’s managers to run their industrial business. They were trusting them to allocate around one of the biggest piles of borrowed money in the world. They were trusting them to decide how much to borrow. When to buy another business. When to buy back shares of GE.

But… GE wasn’t even telling the truth about its own earnings!

In 2009, the Securities and Exchange Commission charged GE with civil fraud. The government said GE had used improper accounting to make earnings look better than they really were. Among other things, GE was accused of pulling more than $370 million of locomotive revenue into earlier periods and using accounting changes that added $585 million to 2002 profits.

GE paid $50 million to settle the case.

That should have told investors everything they needed to know. You cannot trust a management team with $700 billion in borrowed money when it lies about its own earnings. A disaster was only a matter of time. (And yes, I knew it at the time – I told investors in 2010 that GE would soon collapse in an accounting disaster.)

In 2014, GE bought the power businesses of French engineering company Alstom. GE said the deal would cost about $13.5 billion. It told investors the deal would add to earnings right away. It promised billions of dollars in savings. But GE was not just buying turbines and power plants.

It was buying long-term service contracts. These were the same kinds of contracts GE Power already used to report earnings long before the customers paid the cash. It was all a scam. GE Power would sign a service contract that might last for many years. The company would estimate what it would cost to do the work in the future. Then it could record profit today based on those future-work estimates. If management later decided that future costs would be lower, it could report more profit right away.

The cash did not have to show up first. The estimate was enough.

You’ll never guess what happens when the people who get to make these “estimates” are the same people whose bonuses are tied to the “profits” these estimates create. I mean, you’ll never guess.

In 2016, about one-quarter of GE Power’s reported profit came from changes in estimates of future costs. In the first three quarters of 2017, nearly half of Power’s reported profit came from those estimate changes.

GE also sold future payments from those service contracts to GE Capital. That made the cash coming in today look better. But it meant GE was pulling money from the future into the present. Then the whole story fell apart.

In 2018, GE took a roughly $21 billion write-down in its Power business.

The lesson is simple. A company cannot make a bad business good by buying back stock – it can only make it look good for a very short amount of time. A company cannot borrow its way out of a business problem. And, of course, a company cannot survive for long on paper profits that never end up accruing cash.

GE did all three. And it very nearly went bankrupt.

The Same Thing Happened At Boeing

Jim McNerney came from the Jack Welch school. He spent years at GE before becoming Boeing’s (BA) chief executive in 2005.

Boeing was one of the greatest engineering companies in the world. Its job was simple: build the best airplanes in the world. But the company became more focused on cost cutting, outsourcing, margins, Wall Street targets, and the stock price.

To make the share price look good, it bought back huge amounts of stock.

In 2014 alone, Boeing bought about $6 billion of its own shares. Then it approved another $12 billion plan to buy more. Buying back stock did not cause the 737 MAX crashes. But the buybacks tell you something about what management cared about. Boeing did not need a better plan for buying back shares. It needed to protect the thing that made Boeing valuable in the first place: great engineering, great manufacturing, safety, and trust.

A secret dividend cannot replace any of those things.

That’s to say, simply finding companies that pay huge secret dividends isn’t enough.

What matters, ultimately, is how the underlying business performs and whether or not the share buybacks happen at the right price and for the right reasons.

Who does it best? Apple (AAPL).

Apple has bought back nearly $880 billion of its own stock since 2013. That is more money than any company in history has spent buying back its own shares. But Apple was not buying back stock to hide a broken business.

Apple was buying back stock because it was one of the best businesses in the world… and because the stock market badly misunderstood it.

From 2016 through 2018, many investors looked at Apple and saw a phone company. They worried the iPhone would stop growing. They worried about China. They worried that Apple depended too much on one product. They worried that the next iPhone would not be good enough. So they gave Apple an ordinary share price.

But Apple was not an ordinary company. Apple developed an entirely new business model, based on intellectual property. Apple did not need to build any factories. It did not need to own huge amounts of land. It did not need to spend most of its money building new facilities. Instead, Apple simply designed great products. It made the software. It owned the brand – not the stores, not the factories, not the land.

That meant Apple could return huge amounts of cash to shareholders – far more than most companies with the exact same amount of earnings. In 2016, Apple spent about $10.5 billion on buildings, equipment, and other long-term items. That sounds like a lot of money. But Apple generated $216 billion in sales that year. So it spent less than five cents of every sales dollar on the long-term things it needed to keep the business growing.

In 2017 and 2018, the number was about the same: roughly five cents out of every sales dollar.

That is tiny for a company of Apple’s size. Most companies are not like that. Most companies need giant new factories, trucks, machines, land, inventory, and debt just to stay in business. But not Apple.

Apple had a mountain of cash left over after it paid for the things it needed. But the market didn’t give Apple the premium share price its business model deserved. In fact, it was so mis-priced relative to its return on invested capital that even Warren Buffett noticed. Berkshire Hathaway started buying Apple in 2016. It kept buying through 2017 and 2018, when Apple still traded like a big hardware company instead of the cash machine it had become.

By the end of 2018, Berkshire owned about 245 million Apple shares on a split-adjusted basis. That was roughly 5.7% of Apple. Buffett did not need to understand every new phone feature. He saw a company with a great brand, loyal customers, huge cash, low spending needs, and a stock price that did not match the business.

Apple’s board saw the same thing. So it took a mountain of cash and used it to buy more and more of its own AAPL shares.

Apple’s incredible buyback campaign over the last decade is an excellent example of how much wealth can be created for shareholders with secret dividends – when they’re executed in the right way. GE and Boeing are the cautionary tales.

Today there are several companies that are paying big secret dividends in the right way.

MSCI (MSCI) sells the stock indexes, ratings, and data tools used by the biggest money managers in the world. It is a tollbooth business. Once a big pension fund or investment company builds its work around MSCI’s data, changing is hard. That gives MSCI huge cash and very low spending needs. In 2025, its board approved a new $3 billion plan to buy back stock. MSCI is the kind of company that can make the second secret dividend work because it earns a lot of cash without needing to build giant factories.

O’Reilly Automotive (ORLY) sells brake parts, batteries, belts, filters, and the other things drivers and repair shops need right now. It has bought back roughly $27.5 billion of its own stock since 2011. This works because the business is strong. A repair shop cannot wait a week for the right part. O’Reilly’s stores, warehouses, delivery system, and deep parts list matter every day.

Tractor Supply (TSCO) sells feed, fencing, tools, work clothes, dog food, truck supplies, and the things rural homeowners and farmers need. Since 2007, it has spent more than $6.6 billion buying back stock. It has cut the number of shares by nearly 8% since 2021. The company has kept buying even as sales have slowed and investors have worried. That does not guarantee the stock is cheap. But it shows you what owner-like management looks like: a simple business, real cash, and a board willing to buy more when the market is less excited.

Next plc (NXT.L) is a British clothing and home-goods seller. Most clothing stores are not great businesses. But Next is different because it treats every pound of cash like it matters. It uses cash for online growth, small deals, dividends, special B-share payments, and share purchases when the price makes sense. In its latest year, Next returned £839 million ($1.1 billion) to owners.

These are not identical companies. But they share one important thing. They make real cash. They do not need to make big capital investments to grow. And their boards understand that buying their own stock is an investment – not a trick.

If you want to specialize in investing in companies that pay big secret dividends, there are several funds and exchange-traded funds (“ETF”) that are based on this strategy.

But most have the same problem. They look only at the number of shares that disappeared. They do not ask whether the business is good. They do not ask whether the company has too much debt. They do not ask whether the company bought stock when it was cheap.

Here is a quick guide:

If you want one fund today, I would choose Cambria Shareholder Yield ETF (SYLD).

Its founder, Meb Faber, is a friend of mine. More important, he is one of the most honest people in this business. Cambria understands something that most Wall Street firms miss. A company should not get credit just because it buys back stock. If it pays down debt, pays a dividend, and buys stock with real cash, that is much better than borrowing money just to make its share count smaller.

Tell me what you think of today’s Daily Journal: porterstansberrydirect@gmail.com

Good investing,

F. Porter Stansberry
Stevenson, Maryland

⚙ Edit 🗑 Delete
⚙ Edit 🗑 Delete

Presented By: Porter & Co.


3 Things To Know Before We Go…

1. People are staying unemployed longer. One in four unemployed Americans has been looking at least six months for work. As of August, 1.93 million people, or 27.0% of all unemployed, have been out of work 27 weeks or longer, up from 17.8% in February 2023. While unemployment holds steady at 4.1%, it’s getting harder to find a job.

2. Diesel supply is tightening on both sides of the Atlantic. With diesel and heating-oil supplies already drastically low, ExxonMobil’s (XOM) Joliet, Illinois, refinery, which makes roughly 11 million gallons (6% of Midwest capacity) of gasoline and diesel a day, has been offline since a power outage on Sunday. Meanwhile, state-run oil producer Saudi Aramco told European refiners this week that they will get no crude next month after a drone strike shut the East-West pipeline, which bypasses the Strait of Hormuz.

3. Meta (META) taps the junk bond market. Bitcoin miner, now data-center operator, CleanSpark (CLSK), is seeking to raise $2.2 billion in a junk-bond offering to fund a Meta-backed data center in Georgia. This is a notable shift in credit quality for Meta’s AI-infrastructure financing, previously done through investment-grade bonds. Data-center operators have issued $39 billion of high-yield debt so far this year, making it one of the fastest growing areas of the junk bond market.


Chart Of The Day… Sabre (SABR)

Yesterday, travel-software provider Sabre (SABR) issued new bonds and repurchased existing ones, reducing the company’s total obligations coming due in 2029 and 2030 by 45% to $1.7 billion. SABR shares rose 11% to $2.32 on the news. Year to date, shares of Sabre, a Distressed Investing recommendation, are up 70%.


Mailbag

Yesterday, Porter shared details about various types of dividends that companies pay – and not all of them are cash paid out on a specific date as the business details in advance.

“Secret Dividends”

Brady G. writes:

Hi Porter,

Your work has educated, surprised, and impressed me over the years. 2029: The End Of America was outstanding – I read it twice. Thank you. This Daily Journal, however, may be at the top of my list.

I had never heard of these types of dividends and do not understand how they are legal. From bond traders and private-equity firms to politicians engaged in insider trading and IPO insiders, retail investors are constantly reminded that the deck is stacked against them.


Kenneth P. writes:

As we say down south, that shit ain’t right!!!

Thank you for talking about this type of dividend. That is why I am a Partner – to learn how to really make money and how the smart and savvy people do it!

Keep on preaching and exposing the real way!

Crawdaddy.


Jack P. writes:

It is an absolutely interesting article.

How can I, an average investor, access such secret dividends?


Porter & Co. Market Snapshot

Price Yesterday’s Return Year-to-Date Return
S&P 500 Index $7,637.76 1.14% 12.5%
Gold per ounce $4,341.70 1.83% 1.0%
Bitcoin $76,500 0.52% -11.1%
Oil (West Texas Intermediate) per barrel $101.91 -0.26% 76.8%
Berkshire Hathaway (BRK) $763,936 -2.10% 1.2%
Porter’s Permanent Portfolio – 0.57% 3.6%
The Better Than Berkshire Index – -0.10% 5.1%
Total Return Annual Return
Porter & Co’s Top Ranked* 33.7% 15.3%
Yield Yesterday’s Change Change
Year-to-Date
U.S Treasury 30-Year Yield 5.28% -8 bps 44 bps
Prices as of 4:00 pm ET September 17, 2026 | bps = basis points (or 0.01%)
*A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


Porter & Co. Top Positions

Publication Ticker Description Total Return
Biotechnology QURE uniQure 237%
Biotechnology SGMT Sagimet Biosciences 208%
Complete Investor BTC/USD Bitcoin 183%
Biotechnology ROIV Roivant Sciences 177%
Biotechnology TGTX TG Therapeutics 159%
Complete Investor BWXT BWX Technologies 158%
Biotechnology NUVB Nuvation Bio 139%
Biotechnology SGMT Sagimet Biosciences 138%
Complete Investor PM Philip Morris 137%
Complete Investor SKWD Skyward Specialty Insurance 130%
Prices as of 4:00 pm ET September 17, 2026


Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

The post The Second Secret Dividend Can Make You Rich… Or Ruin You appeared first on Porter & Co..
  • ✇Porter & Co
  • Moving Arrowhead Pharmaceuticals Off The Watchlist Porter &#38 · Co.
    In Porter’s first issue of Porter & Co. Biotechnology, he recommended one of the key players in gene silencing, Arrowhead Pharmaceuticals (Nasdaq: ARWR). However, he felt that we needed to wait for a better entry price. In that August 1 issue, he said that Arrowhead had done everything right: its triglyceride drug is approved and selling, it has pushed gene silencing into muscle, fat, lung, and brain, and the large drugmakers have paid Arrowhead billions for access. The stock had run from
     

Moving Arrowhead Pharmaceuticals Off The Watchlist

18 September 2026 at 08:17

In Porter’s first issue of Porter & Co. Biotechnology, he recommended one of the key players in gene silencing, Arrowhead Pharmaceuticals (Nasdaq: ARWR). However, he felt that we needed to wait for a better entry price. In that August 1 issue, he said that Arrowhead had done everything right: its triglyceride drug is approved and selling, it has pushed gene silencing into muscle, fat, lung, and brain, and the large drugmakers have paid Arrowhead billions for access. The stock had run from $15 to $87 in the past year. We want to own this company below $75, he concluded.

Shares of Arrowhead Pharmaceuticals are now trading around $67 per share, so we are moving them from our watchlist into a “buy” recommendation, below $75.

Action to Take: Buy Arrowhead Pharmaceuticals (Nasdaq: ARWR) below $75 per share

The post Moving Arrowhead Pharmaceuticals Off The Watchlist appeared first on Porter & Co..

  • ✇Porter & Co
  • Trade Alert And Update – Week Of September 14, 2026 Porter &#38 · Co.
    The value of The Trading Club tracking portfolio settled at $125,872 as of Thursday, September 17 – up 25.9% since the May 30, 2025, inception date (see the detailed portfolio snapshot below). Based on last Friday’s trade alert, we made the following transaction in our Trading Club tracking account on Monday: Bought to open one Invesco QQQ Trust (Nasdaq: QQQ) $680 put, expiring October 16, 2026, at $9.06 per share. In this update, we review the options set to expire today, September 18, and set
     

Trade Alert And Update – Week Of September 14, 2026

18 September 2026 at 07:39

The value of The Trading Club tracking portfolio settled at $125,872 as of Thursday, September 17 – up 25.9% since the May 30, 2025, inception date (see the detailed portfolio snapshot below). Based on last Friday’s trade alert, we made the following transaction in our Trading Club tracking account on Monday:

Bought to open one Invesco QQQ Trust (Nasdaq: QQQ) $680 put, expiring October 16, 2026, at $9.06 per share.

In this update, we review the options set to expire today, September 18, and set the stage for our next series of trades to be released next week. As a reminder, the upcoming recommendations will be shorter-duration “interim” trades, expiring in mid-October. Later in the month, we will return to our normal schedule of publishing quarterly trades, as well as a video recording that walks through each position.

Options Expiration Review

Eight options positions in The Trading Club portfolio are scheduled to expire at the close of trading today, including five covered-call positions and three cash-secured put trades. No action is needed, as we plan to hold all positions through the expiration date.

We’ll begin with a review of the covered-call positions, listed below.

Covered Calls Expiring Today

  • One Celsius Holdings (Nasdaq: CELH) $35 covered call, covering all 100 shares of our 100-share long position
  • Two Figma (NYSE: FIG) $25 covered calls, covering 200 shares of our 300-share long position
  • One WaterBridge Infrastructure (NYSE: WBI) $35 covered call, covering all 100 shares of our 100-share long position
  • Two Viper Energy (Nasdaq: VNOM) $46 covered calls, covering 200 shares of our 400-share long position
  • One WaterBridge Infrastructure (NYSE: WBI) $35 covered call, covering all 100 of our 100-share long position

Based on Thursday’s closing prices, each of the underlying stock prices for these call options are well below the call strike price. As such, these covered calls will likely expire out-of-the-money and become worthless at the close of trading today. In this scenario, we pocket the premiums free and clear, while still retaining the underlying shares, meaning we are then able to repeat a similar trade.

Conversely, if any of the underlying stocks rally and close above the option strike prices today, the options will expire in-the-money. This means our shares will get “called away” and sold at the strike price after the close of trading.

We’re happy with either scenario, and thus no action is needed for these trades.

Next, we’ll review the cash-secured put positions, listed below.

Cash-Secured Puts Expiring Today

  • Two Celsius Holdings (Nasdaq: CELH) $30 cash-secured puts, representing a $6,000 capital commitment to purchase 200 shares at $30
  • One Philip Morris International (NYSE: PM) $175 cash-secured put, representing a $17,500 capital commitment to purchase 100 shares at $175
  • One WaterBridge Infrastructure (NYSE: WBI) $30 cash-secured put, representing a $3,000 capital commitment to purchase 100 shares at $30

Based on Thursday’s closing prices, shares of Celsius were well below the put-option strike price, meaning this option will likely expire in-the-money at the close of trading today. In this scenario, our broker will automatically purchase 200 shares of Celsius on our behalf at $30 per share, for a $6,000 purchase commitment.

Alternatively, if Celsius shares rally above the strike price by the close of trading today, the option will expire out-of-the-money, and we pocket the premiums free and clear, while our obligation to purchase shares disappears.

Conversely, shares of Philip Morris and WaterBridge were above their respective put-option strike prices at the close of trading on Thursday. If shares remain at or above these recent prices, the put options will expire out-of-the-money, removing our obligation to purchase shares. Conversely, if shares fall below their option strike prices, we will be on the hook to purchase 100 shares of stock at the option strike price.

In all cases, since these are cash-secured puts, our broker has already set aside enough restricted cash to make good on these purchase commitments in the event that any of these put positions expire in-the-money. And because we are willing buyers of each of these underlying stocks at the option strike prices, we will simply hold these positions through the expiration date.

Next, we’ll briefly review our plan for Monday’s trades.

Monday’s Game Plan

To set the stage for our overall market outlook and trading plan going forward, we’ll begin by addressing the following subscriber question from The Trading Club Forum:

Today [September 15], Porter published a very worrying post about the national debt situation and rising interest rates. He recommended selling P&C insurance stocks. I know we don’t hold these stocks, but clearly he is very concerned about the market. I am hoping you can provide your thoughts on the state of the market and how you plan to prepare for what seems like an inevitable market fall. Very worrying times ahead for sure and NOT a time to take risks and not have a clear strategy in place in advance. As the Boy Scouts motto says, “Be Prepared,” which sounds smart to me.

Yes, I share the same concerns as Porter regarding the sharp rise in interest rates, along with the global energy supply crisis, on top of the risks associated with the potential unwind of the artificial intelligence (“AI”) boom. We’ve written about these threats in our prior two weekly updates, which you can find here and here. And in response to these risks, we’ve begun aggressively adding defensive positions into the portfolio, including our recent covered-call sales and protective put purchases.

Of course, it’s also worth pointing that Porter included one key caveat with his warning about the threat from higher interest rates. That is, no one – not even God himself – can predict the future path of interest rates. And I would extend that caveat to the broader idea that no one can reliably predict the near-term swings in any market prices. The past week provided yet another reminder of this fact. Energy prices fell despite additional attacks on energy infrastructure. Long-term bond yields fell despite the Federal Reserve hiking overnight interest rates. And technology stocks rallied even as the two leading AI companies warned of an imminent AI-apocalypse and a potential slowdown in large-language-model development.

So, yes, we are mindful of the downside risks in the market. But the flip side is that we can be wrong, or early (which is the same thing), in recognizing and reacting to these risks. And ultimately, it’s up to every individual investor to decide how they will allocate their capital in the face of the potential risks in the market.

As for our approach in The Trading Club, our goal is to strike a balance between both sides of the risk/return equation – a goal we believe is made possible with a prudent options-trading strategy. Right now, that means foregoing upside on a substantial portion of the portfolio in order to harvest consistent options premiums with our covered-call and put-selling strategies. And to reinvest a portion of these premiums into downside hedges in the technology sector, which we believe is most at-risk from an inevitable (but unpredictable) turn in the market cycle.

Finally, we also plan to maintain a focus on stocks that are beaten down and out of favor, where the discounted valuation means the long-term risk of capital impairment is low. But of course, that doesn’t mean that a cheap stock can’t get cheaper, or won’t get swept up in overall market volatility, as we’ve seen across a large number of our holdings recently.

Over a full market cycle, we have confidence that this basic process of buying good stocks on the cheap, harvesting consistent options premiums, and hedging the downside is a winning formula. That confidence comes from having seen this process work in our own investing portfolios, and it’s why we put real money behind this strategy and promised to show you every trade along the way, warts and all.

On Monday, we plan to continue executing our same basic strategy with a series of similar trades to the ones that expired today. We remain bullish on each of the existing holdings in the portfolio. But given the risks we see in the broader market, we will continue playing defense by harvesting consistent options premiums on many of these stocks, and reinvesting a portion of these premiums into additional hedging trades.

Stay tuned for more on Monday, when you can expect to receive the next trade recommendations in your inbox.

Next, we’ll show each position in the portfolio broken down by trade type.

Portfolio Review

The table below shows all current holdings as of the close of trading on Thursday, September 17. Please note that we have recently modified some of our recommended prices.

A few notes on how to read and interpret this portfolio table.

Please pay special attention to the “Action” column, where we specify whether each trade is a “buy” or “sell to open” transaction.

Next, the position size for each trade is equal to the current value of the position, with the exception of the cash-secured puts. In the case of the cash-secured puts, we define the position size as the total value of our future commitment to purchase 100 shares for each contract. This number is calculated as follows:

Position size = number of contracts x 100 x put strike price

We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade.

For example, in the case of the Celsius Holdings (Nasdaq: CELH) $30 puts, the position size equals 2 x 100 x $30 = $6,000. We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade.

To see the current profit/loss across each open position and other details, please see the live snapshot of our tracking portfolio at the end of this update.

We have compiled a summary overview of the latest quarterly trades released on June 22, which you can find here. Since then, we have recommended the additional trades listed below:

  1. On July 17, we recommended purchasing shares of Novo Nordisk (NYSE: NVO), which you can find here
  2. On July 21, we recommended purchasing shares of Hims & Hers Health (NYSE: HIMS), and we provided the analysis for the company on July 24, which you can find here

If you have any questions or feedback, The Trading Club Forum is the best chance to get a quick response from our team.

Alternatively, you can always email us at mailbag@porterandcompanyresearch.com.

Good investing,

Ross Hendricks
Porter & Co.


The post Trade Alert And Update – Week Of September 14, 2026 appeared first on Porter & Co..

  • ✇Porter & Co
  • The Three Secret Dividends Porter &#38 · Co.
    Issue#160, Volume#3Why The Insiders Never Talk About The Dividends That Matter Inside Today’s Issue Essay: The Three Secret Dividends Gold Beats Out Treasuries The Fed Raises Rates Private Credit Slips Again Chart Of The Day… Veeva Systems (VEEV) Poll Results Today’s Mailbag You will not get rich on regular dividends. And you’ve probably never heard of the three kinds of secret dividends that public companies use to make the insiders incredibly rich. The average payout ratio of the S&P
     

The Three Secret Dividends

16 September 2026 at 13:31

Issue#160, Volume#3

Why The Insiders Never Talk About The Dividends That Matter

Inside Today’s Issue

  • Essay: The Three Secret Dividends
  • Gold Beats Out Treasuries
  • The Fed Raises Rates
  • Private Credit Slips Again
  • Chart Of The Day… Veeva Systems (VEEV)
  • Poll Results
  • Today’s Mailbag

You will not get rich on regular dividends.

And you’ve probably never heard of the three kinds of secret dividends that public companies use to make the insiders incredibly rich.

The average payout ratio of the S&P 500 is around 35%.

That means, if you’re counting on regular dividends, you’re missing out on roughly two-thirds of the earnings of the companies you own. Where does all the money really go…?

It probably won’t surprise you that company insiders try very hard to make sure that you never understand where the wealth really accrues. It ain’t the dividend you read about in the paper that matters, that’s for sure. It’s the dividends you never hear about that will make you rich.

Ask me how I know…

In October 2023, while I was CEO of MarketWise (MKTW), our board declared a “special” $50 million cash dividend. This was the largest cash distribution we’d ever made as a public company. It was about 4x more than our regular annual dividends. But it never showed up on the securities databases as an “indicated” dividend. It went virtually unmentioned and unnoticed. It doesn’t even show up as part of the total return in most equity databases. It’s like it never happened.

And unless you were a shareholder on November 10, 2023, you didn’t get any of the money. None. Even if you’d held the stock for years previously. But… if you owned the stock on that one day, you got your pro-rata portion of a huge pile of money. Otherwise, you got zilch.

A trailing 12-month dividend yield divides the regular dividends of the past year by the current share price. But the databases exclude these kinds of “special” or one-time distributions. It’s like they don’t exist. Nasdaq’s methodology only reinvests regular dividends. And market makers deduct special dividends from the price of the stock on the open after the ex-date, when the stock trades “ex-dividend.” So the largest cash payment a company makes in a decade can be absent from the yield figure on public-pricing screens and buried in the return series we use to judge the stock. It’s like they never happened.

But it’s these kinds of huge dividends that will make you rich.

It’s funny how the most powerful thing public companies can do with their cash payments is virtually a secret from the public.

Why? Well because that’s how the insiders want it. High-quality companies that are closely managed and closely held by insiders use these kinds of dividends to massively enrich themselves.

For example, RLI (RLI) is one of America’s leading specialty property-and-casualty (P&C) insurance companies. I’ve followed it and written about it in my newsletters since 2006. They sure wish I wouldn’t…

On May 14, 2026, RLI declared a $2.00 special dividend, expected to total approximately $184 million, payable June 12 to holders of record on May 29. They’ve been paying out most of their profits in this way for decades. Since the Global Financial Crisis, RLI has paid out a total of $611 million in regular dividends. But where did the real money go…? RLI has paid out a total of $1.8 billion in special dividends – 3x more.

Or there’s TransDigm Group (TDG). You’ve probably never heard of the company, but it is the best managed aerospace company in the world. On September 20, 2024, TransDigm declared an enormous special cash dividend of $75.00 per share ($4.4 billion in cash!), paid October 18, 2024, to holders of record on October 4. Where did the money come from? TransDigm borrowed it. Its stated goal is to deliver returns comparable to a well-performing private equity fund – but only to the insiders who know when these huge payments will be made.

Four dates govern every dividend. The declaration date is when the board announces it. The record date is the day you must appear on the company’s books as an owner. The ex-dividend date is the trading cutoff, set by exchange rule rather than by the company. The payment date is when cash arrives.

Since May 28, 2024, American stocks settle one business day after the trade. Buy a stock and you become the owner of record the next business day.

The TransDigm board declared the $75 dividend on September 20, 2024, with a record date of Friday, October 4, and a payment date of Friday, October 18. To collect $75 per share, you had to buy no later than the close on Thursday, October 3, so that the trade settled on October 4.

These big special dividends are fun to track and are great for padding your account with cash. But … there’s a problem with big cash distributions. First, they trigger taxes. And second – and more important – they take capital away from the company, where it will no longer compound.

If you want to become vastly wealthy, you need to look for the second kind of secret dividend.

These are truly invisible. They’re not typically announced. And no payment will reach your account directly, so there’s no taxes you’ll owe. Instead, this is a hidden way of buying more shares. Only… you don’t have to pay for them.

AutoZone (AZO) began paying this kind of secret dividend in 1998. Through November 22, 2025, the company has spent $38.9 billion on these dividends – none of which was announced publicly.

What kind of dividend is this…? The kind that buys more of a company for you, silently and automatically.

Berkshire Hathaway (BRK) bought about 10% of American Express (AXP) in 1995. It hasn’t spent a dime on the stock since then, 31 years ago. And yet… today Berkshire owns 22% of one of America’s greatest companies. Berkshire paid $1.29 billion for 10% of American Express. But today it owns 22% … worth almost $50 billion. Without the secret dividends it received, Berkshire’s stake would only be worth $20 billion.

There are many of these kinds of leading secret dividend paying stocks. And, I believe, most of the passive wealth in America today was created through these secret dividends.

My favorite example of America’s leading secret dividend payer is homebuilder NVR (NVR), a company that I’ve been recommending since 2007. It’s just a homebuilder. It’s not rocket science. But it has created massive wealth through its secret dividend program and almost no one knows it even exists.

If you bought 5% of NVR in 1996, it would have cost about $7 million (732,955 shares). You became a major shareholder in a national homebuilder. And you never bought another share. But over the last 30 years, NVR has paid out $17 billion in secret dividends. None of this money hit your account, directly. You paid no tax. But your wealth exploded as a result.

Today, your 732,955 shares would be 26% of the company. Your stake would be worth $4.59 billion. You didn’t just become rich, you became massively wealthy. All from dividends that no one else can see. All you had to do was understand how they work.

These kinds of secret dividends create so much wealth, all the libtards want to make them against the law. And they were against the law until the mid-1980s. I’m convinced there’s simply no better way to become truly wealthy in America. And it’s easy: you literally do nothing and get incredibly rich.

But even they aren’t the best kind of secret dividend.

The best kind of secret dividend is so rare and such a closely guarded financial secret that I honestly shouldn’t ever write about it. If I was smarter, I would never explain this to anyone else – ever. This is, without question, the single greatest wealth secret I have ever discovered.

You see, companies like AutoZone, American Express, and NVR become pretty famous for their secret dividends. A lot of analysts and investors know about these stocks and track the size and scope of their big secret dividends.

But no one has ever told you about HEICO (HEI). And no one ever will.

In 1990 the Mendelson family took control of a tiny $25 million South Florida company with about 200 employees. Laurans Mendelson and his sons Eric and Victor did not attempt a transforming acquisition. They didn’t fire a bunch of people to cut costs and raise profits. They didn’t borrow a ton of money, either. And like a regular business, they paid cash dividends twice a year. HEICO occasionally pays special dividends, too.

But that’s not where the money went. The Mendelsons were amongst the savviest capitalists in the United States. They weren’t going to waste their cash on dividends. HEICO’s payout ratio is 4%. The Mendelsons took 96% of their earnings and they invested in the most valuable secret dividend stream of all…

Look at last year. In fiscal 2025, HEICO reported record net sales of $4.49 billion, up 16%, and record net income of $690.4 million, up 34%, on a consolidated operating margin of 22.7%. Nothing extraordinary. Just a good business with solid growth.

But where did the money go? HEICO completed five acquisitions during the year, three at the Electronic Technologies Group and two at Flight Support, whose net sales have now grown sequentially for 21 consecutive quarters.

Thirty-five years of that arithmetic turned a $25 million company into a company earning $690 million a year.

Instead of paying you cash, HEICO invests your pro rata share of their earnings into better businesses than you can invest in yourself. It manages them. It grows them. And you reap the returns with higher earnings, higher cash dividends, and a vastly higher stock price.

These kinds of special dividends mean you don’t need the stock market to go up to get very rich. These companies are, independent of other factors, their own compounding machines.

Danaher (DHR), AMETEK (AME), Roper Technologies (ROP), and Constellation Software (CNSWF) run this same strategy in life sciences, instruments, vertical software, and industrial niches. These stocks aren’t called private equity firms, but that’s what they do. And they’re among the best in the world at it. They buy small businesses at sensible prices with modest leverage and the returns compound quietly for decades.

Shhhhhh…!

Don’t tell anyone.

Good investing,

F. Porter Stansberry
Stevenson, Maryland

Presented By: Porter & Co.

3 Things To Know Before We Go…

1. Gold Is breaking away – and cementing itself as collateral. The U.S. 10-year real yield sits at 2.6%. By the relationship that governed markets for 25 years, gold should be near $2,000 per ounce. Today it trades around $4,300 an ounce. The chart shows exactly when the two lines separated: the week Washington froze Russia’s reserves because of its invasion of Ukraine. Global central banks reacted. From their perspective, Treasury bonds stopped being a risk-free asset and became a potential tool for U.S. foreign policy. Gold now makes up 27% of their reserves against 22% for Treasurys, the first reversal since 1996, and 89% of reserve managers expect to hold more gold a year from now.

2. The Fed raised rates for the first time since 2023 and expects to raise them again. This afternoon, the Federal Open Market Committee (“FOMC”) unanimously lifted its benchmark interest rate a quarter point to a range of 3.75% to 4%. Chairman Kevin Warsh said: “The plain fact is that inflation is too high and has been for too long.” Sixteen of 18 officials project at least one more increase this year. Whether higher rates will actually lower price inflation is a separate question. Interest on federal debt passed $1 trillion in the first 11 months of this fiscal year, up 13% from a year earlier, and each hike raises it further. The four largest hyperscalers plan more than $700 billion of capital spending this year, funded mostly from cash flow rather than interest-rate-sensitive debt. Consumer spending is being carried by the top of the K – the high-income households who are still spending while lower-income households pull back – and their high cash balances will earn even more as rates rise. But higher rates will do nothing to open the Strait of Hormuz or ease energy supply disruptions.

3. New highs in private credit defaults. Credit ratings agency Fitch revealed that the private credit default rate jumped to 6.3% in August, marking the fifth consecutive month of new highs. With the majority of private loans financed with short-term floating interest rates, the pressure on the sector will likely intensify after the Fed’s decision to raise rates today for the first time in three years. Given the size of this $1.8 trillion asset class, a further rise in default rates could eventually create ripple effects in the broader U.S. economy.

Chart Of The Day… Veeva Systems (VEEV)

In August, Porter recommended the pharmaceutical software platform Veeva Systems (VEEV) to Porter & Co. Biotechnology subscribers. Shares are up 31% since then and 43% over the last six months.

⚙ Edit 🗑 Delete

Just today, Porter released explosive new details as to why we are likely to see this sector take over in dramatic fashion in the near term. To watch Porter’s video – released just hours ago – click here now.

Poll Results… Interest Rates

Yesterday, we asked readers what they thought the FOMC would do regarding interest rates… hike, cut, or keep the same… well, 60% of survey takers selected “increase rates by 25 basis points,” while 34% selected “keep rates where they are.” Just 5% expected a 50-basis-point increase while not one survey takers predicted a rate cut.

Mailbag

“What To Do About P&C”

Jon H. writes:

Thank you so much for the material I have been reading since 2007. It was an education that I never could have afforded on my own.

After reading your rebalancing of Porter’s Permanent Portfolio, I have the following question.

Will your review of these P&C companies be affecting the other Porter & Co. letters?

Thank you again for all you do for us.


Gary C. writes:

In Tuesday’s “Important Allocation Update” in the Daily Journal, you wrote that, for a conservative investor, the recommendation is to stand aside from the P&C insurance industry “until interest rates find a ceiling.

I understand the rationale behind that decision, especially the risks from claims inflation, higher bond yields, and potential valuation compression, and I agree with the rationale.

What I’m trying to understand is how that view fits with the P&C exposure that still exists elsewhere in the Porter & Co. portfolios.

Complete Investor currently holds AXS, CB, IGIC, KNSL, L, PGR, SKWD, and WRB, while the new PCPP ETF provides broader, but still concentrated exposure across a larger group of P&C insurers and offers greater diversification across the sector.

Has this macro view changed your thinking about P&C exposure across those other strategies or portfolios, or is the Permanent Portfolio action primarily a portfolio-construction decision specific to that portfolio?

I suspect this may come up at next week’s Annual Conference. I’ll be at the Farm and look forward to the discussion, but I’d appreciate any clarification beforehand.

Porter & Co. Comment: In Saturday’s Complete Investor issue to paid-up subscribers, we will recommend how this outlook on P&C stocks plays out across the eight P&C stocks there.

Regarding PCPP, Porter wrote yesterday:

Note: This change applies to our own track record, not to every account built around this idea. The Porter & Company Porter Portfolio Index ETF (PCPP) that Tuttle Capital Management runs keeps its rules-based 25% allocation to each of its four sleeves. And your own allocation may not need to change either, depending on your tax situation, your time horizon, and how much of this risk you are already hedging elsewhere.


Porter & Co. Market Snapshot

Price Yesterday’s Return Year-to-Date Return
S&P 500 Index $7,585.73 -0.45% 11.7%
Gold per ounce $4,332.80 -0.17% 0.5%
Bitcoin $75,612.51 -4.06% -13.4%
Oil (West Texas Intermediate) per barrel $105.83 3.74% 80.4%
Berkshire Hathaway (BRK) $773,825.01 0.27% 2.5%
Porter’s Permanent Portfolio – 0.55% 3.8%
The Better Than Berkshire Index – 0.36% 7.0%
Total Return Annual Return
Porter & Co’s Top Ranked* 35.0% 15.9%
Yield Yesterday’s Change Change
Year-to-Date
U.S Treasury 30-Year Yield 5.36% 2 bps 52 bps
Prices as of 4:00 pm ET September 15, 2026 | bps = basis points (or 0.01%)
*A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


Porter & Co. Top Positions

Publication Ticker Description Total Return
Biotechnology QURE uniQure 237%
Biotechnology SGMT Sagimet Biosciences 194%
Complete Investor BTC/USD Bitcoin 180%
Biotechnology ROIV Roivant Sciences 174%
Complete Investor BWXT BWX Technologies 159%
Biotechnology TGTX TG Therapeutics 150%
Complete Investor PM Philip Morris 141%
Complete Investor SKWD Skyward Specialty Insurance 134%
Biotechnology SGMT Sagimet Biosciences 130%
Biotechnology NUVB Nuvation Bio 128%
Prices as of 4:00 pm ET September 15, 2026

Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

The post The Three Secret Dividends appeared first on Porter & Co..

  • ✇Porter & Co
  • Important Allocation Update Porter &#38 · Co.
    Issue#159, Volume#3Why We’re Changing Our Allocation In A “Permanent” Portfolio Inside Today’s Issue Essay: Why We’re Changing Our Allocation In A “Permanent” Portfolio Oil Tankers: $1 Million Per Day The Oil Crisis Has Arrived Bond Yields Go Global Chart Of The Day… APA Reader Poll… Interest Rates Today’s Mailbag Today’s Journal is extremely serious, but let me begin with a joke. Normally, bond salesmen never get into heaven. If you’ve never read the classic Liar’s Poker, then you may not
     

Important Allocation Update

15 September 2026 at 13:00

Issue#159, Volume#3

Why We’re Changing Our Allocation In A “Permanent” Portfolio


Today’s Journal is extremely serious, but let me begin with a joke.

Normally, bond salesmen never get into heaven. If you’ve never read the classic Liar’s Poker, then you may not understand why. Bond prices are opaque. That means bond salesmen can frequently get away with “murder” – taking a huge spread out of the trades they do for customers. There are a lot of bond traders without scruples who take advantage of “muppets” and sell them bonds with spreads wide enough to drive a new Ferrari through.

And so bond salesmen generally don’t get into heaven. But when 9/11 happened, God made some exceptions. An entire bond trading firm (Cantor Fitzgerald) got wiped out when the planes hit the towers. So God brought them all in. And he explained:

Look, you guys really don’t deserve to be here, okay. But I feel terrible about what’s happened to you. You’ve lost your lives, your families… your Ferraris. Everything. So, I’m willing to make an exception – this time. But I need something in return…

Well, as you can imagine, the bond traders were shocked and confused at first. But then they realized that God needed something from them. And unless they could give it to him, they were going to hell – for eternity!

The emerging-markets managing director came to his senses first. (He was the one most used to everything going to hell.) He stood up and faced God.

God, you’ve saved us. Thank you. We are all in your debt. And looking back, I understand why you don’t normally allow bond traders in here. We are all grateful and want to do whatever we can to help. What can we do for you, God?

God walked over to him. He put his arm around him and said, “Walk with me a minute.”

As they walked out of earshot of the other traders, God asked…

What do you think interest rates are going to do next year…?

We’re making a substantial change to our recommended allocation in Porter’s Permanent Portfolio. We recognize that there are lots of good reasons not to follow our advice about this change.

In the first place, no one can predict interest rates, not even God. And, secondly, the entire idea of a Permanent Portfolio is that you do not have to do any trading or hedging, as the portfolio is already hedged. It holds 25% in cash and 25% in gold and Bitcoin, which is a hedge against monetary volatility. Assuming you rebalance each year, this kind of portfolio will survive a crisis and continue to prosper – just as it did in 2008/2009 and just as it did during the COVID market panic.

But even though there are real risks to making this change, we think it’s the best course – for conservative investors who are retired.

Here’s why.

The 10-year U.S. Treasury yield hit 5% on Monday, September 14, driven by soaring energy prices, the widening war with Iran, and a bond market losing patience with Washington’s deficits.

Interest rates on the benchmark U.S. bond have only touched that level once since before the Global Financial Crisis, in October 2023. But by that point, the Fed had raised its benchmark rate 11 times (!) since starting the cycle in March 2022, taking the federal funds target range up to 5.25-5.50%.

In other words, back in October 2023, the Fed was already well into a tightening cycle. Commodity prices were already coming down, and measures of inflation were moderating. And the Fed Funds rate was at par with two-year Treasury notes.

Today, commodity prices are soaring. And the Fed hasn’t begun a determined hiking cycle – putting itself way behind the curve. The Fed Funds target range is currently 3.50%-3.75%, while the two-year Treasury yield is 4.67%. That means the Fed is about 100 basis points behind the market’s rate of interest.

What does all this mean? We’re on the cusp of a rate-hiking cycle.

And there are real risks to this cycle because of the size of the national debt. We are entering uncharted waters with the massive size of the coming refundings. Total marketable U.S. Treasury debt outstanding is $31.8 trillion, carrying a weighted-average interest rate of about 3.48%. About 33% of that debt, roughly $10.5 trillion, matures within 12 months. Call it $15 trillion over the next 18 months. So roughly half of the national debt will reprice in the next 18 months.

If rates average 5% (which, again, is behind the curve currently), that will add $220 billion in annual interest expense. That would be a 21% increase to current interest expense ($1 trillion currently). It would also add 12% to the annual deficit.

While important, the bigger issue is how this big increase in interest expense will be paid for. There’s zero chance the government reforms entitlements or cuts military spending. Which means these bigger interest payments will surely be paid for by yet more inflationary government deficit spending. And the deficit is already running at 6% of GDP (gross domestic product).

That will push us into a very dangerous situation. The Fed may not be able to raise rates high enough to stop the inflation this time because our debt stock is now so large relative to GDP that a Paul Volcker-style interest rate-hiking cycle isn’t fiscally survivable like it was in 1980.

These risks are not priced into the market yet and, in fairness, these risks may not materialize for a few more years. However, I do note that Bank of America (BAC) is down 10% in the last month. It’s my best canary in the coal mine stock to gauge interest rate risks, because of its enormous, low-yielding bond portfolio. (Bank of America bought $700 billion in 2% bonds in July of 2020.) As rates go higher, the risks grow that Bank of America will fail because of the losses on these bonds.

My main concern is that this inflationary cycle may be much harder to control, because it’s being driven by factors (entitlement spending, global geopolitics) that aren’t easily constrained. And as I told you yesterday, that kind of macro outlook reminds me very much of the 1973-1974 inflationary period, which didn’t resolve for a decade.

That means our property-and-casualty (P&C) insurance stocks face a very tough outlook.

P&C insurers write the policies that cover your car, your home, and your business against loss. They invest the premiums they collect, called float because it sits in their account between the day you pay and the day a claim gets paid. And insurance companies invest mostly in bonds.

That business model works well when rates and inflation are calm. It comes apart when they spike, for three reasons that hit at once.

  1. Claims get more expensive. It costs more to rebuild a fire-damaged house, replace a wrecked car, or settle a lawsuit when the general price level is rising. State regulators approve premium rate increases with a lag, sometimes a year or more, so claims costs can outrun the premium dollars collected to pay for them. Insurers call this loss-cost inflation. On liability lines, where lawyers and juries set the price, it’s called social inflation: litigation costs and jury awards climbing even faster than the government’s own inflation figures.
  2. The bonds insurers already own lose value. A bond paying 4% is worth less the moment the market can buy a new one paying 6%. That loss shows up immediately on the balance sheet, in book value: the net worth per share that investors use to price insurance stocks in the first place.
  3. The whole stock market’s multiple, the price investors will pay for each dollar of a company’s earnings or net worth, shrinks. When a 10-year Treasury pays 5% with no credit risk, investors demand more from every other asset, including P&C stocks that already trade close to book value. Book value shrinks from the bond losses, and the multiple applied to what’s left shrinks too, so both hits land in the same quarter.

There is one important offset to these risks. As insurance companies’ old, low-coupon bonds mature, insurers reinvest the cash into new bonds paying the higher rate. Thus, investment income rises over the following one to two years, and the stocks’ dividends rise with it, usually with a lag of a year or two behind the rate move itself. But that rebuilding takes years to show up in earnings, while the bond losses and the multiple compression show up the day rates move. The stock falls first, and recovers. If it recovers, it does so on a much longer clock than the dividend does.

I wanted to know how this unfolded during the 1973-1974 inflation. So I went back to the last time inflation and rates did this to P&C insurers, and I studied their share prices between January 1973 to January 1975, the two years bracketing the oil embargo, the wage-price spiral, and the 1973-74 bear market.

I used a primary source: the Associated Press‘ own NYSE and over-the-counter stock tables, printed daily in newspapers and digitized by the University of North Texas’s Portal to Texas History. We pulled the closing quotes nearest January 1973 and January 1975 for every major P&C insurer that was trading at the time, while we carefully excluded life insurers. Then we cross-checked the prices against Yahoo! Finance.

Here is what a pure-play P&C portfolio did over those two years.

The average decline across those nine names was 42%. The median was 43.5%. The S&P 500 itself fell 41% – from 119.10 to 70.23 – over the same stretch.

P&C insurance, the industry investors buy for safety, fell in line with the broader market, and in several cases fell harder.

We left several well-known names out of that table on purpose. Aetna Life & Casualty, Travelers, CNA Financial, Old Republic International, General Reinsurance, and Kemper all traded through the same period, and all fell too, in some cases much further. CNA Financial dropped 85%, but CNA was carrying a large life and health insurance book and came within a step of insolvency in 1974, when Loews bought 83% of its stock in a rescue. Aetna and Travelers ran life insurance and group health divisions as large as their P&C operations. General Reinsurance wrote reinsurance, not primary policies.

For a conservative investor, our recommendation is simple: stand aside from the P&C insurance industry until interest rates find a ceiling.

For our own track record, we are selling our 25% P&C allocation (“Insurance”) inside Porter’s Permanent Portfolio, in full. The proceeds move into our cash holdings, whose target allocation rises from 25% to 50% of the portfolio. The Lindy stocks (“Equities”) and the gold-and-Bitcoin allocation remain at 25% each.

We acknowledge that this kind of tactical move is risky. Selling triggers taxes and opens us to another risk: selling too soon. I recognize the 10-year U.S. benchmark yield touched 5% in 2007 and again in 2023, and both times it reversed. If that happens a third time, we will look foolish holding half the portfolio in cash while stocks and bonds recover without us.

As always, I simply give you the information I would want if our roles were reversed. In my personal portfolio, I have established a $10 million short position in long-duration bonds. I’m using that to hedge my exposure to the stock market. I’m not suggesting that’s right for you. I’m only explaining that I have a substantial amount of capital at risk based on the very analysis that I’m giving you.

I see a slew of risks that our country hasn’t faced in 50 years: massive and growing deficits, an energy shock now running through the global bond market, and the automatic cost-of-living increases built into Social Security and other entitlement programs. Together they point toward double-digit inflation and a 10-year Treasury yield above 8%, not a retreat below 5%.

Note: This change applies to our own track record, not to every account built around this idea. The Porter & Company Porter Portfolio Index ETF (PCPP) that Tuttle Capital Management runs keeps its rules-based 25% allocation to each of its four sleeves. And your own allocation may not need to change either, depending on your tax situation, your time horizon, and how much of this risk you are already hedging elsewhere.

Our new target allocation, until rates stabilize, is 25% Lindy stocks (high-quality businesses with the pricing power to raise prices as fast as their costs rise), plus 25% gold and Bitcoin. The rest, 50% cash, sits ready so we can redeploy into high-quality stocks and bonds once it looks like the inflation tide is going to recede.

A 10-year Treasury yield at 5% and moving higher doesn’t break a good insurer’s underwriting. But it does change the price investors will pay for it.

Tell me what you think of today’s Journal: porterstansberrydirect@gmail.com

Good investing,

F. Porter Stansberry
Stevenson, Maryland

Presented By: Banyan Hill Publishing

Hall Of Fame Trader Jon Najarian’s Top 5 Trades This Week

For the first time ever, he went live to show folks how it’s possible, but by no means probable, to make more in a single week than most people make in a year.

Starting this week!

He even detailed his FIVE new trade alerts… and gave away the name and ticker of his #1 play during the event.

Click here to watch now and see everything.

Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Banyan Hill is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.


3 Things To Know Before We Go…

1. Oil tankers now cost more than $1 million a day to hire. The Baltic Exchange, the London body that publishes shipping’s benchmark prices, assessed a supertanker carrying crude oil from the Persian Gulf to China at $1.035 million a day on Monday, the first seven-figure reading in the index’s history. The same route set a record of about $424,000 a day when the Iran war began in late February, and before the war, shipbroker Clarksons expected these ships to average just $75,000 a day. Few owners will currently send a vessel through the Strait of Hormuz. Crude is instead ferried out to the Gulf of Oman and transferred ship-to-ship, and Houthi attacks in the Red Sea are forcing some tankers onto a detour around Africa that adds roughly 30 days to transit. Every extra day at sea removes a ship from the market.

2. Energy executives warn: “Crisis is here.” A growing chorus of energy veterans is sounding the alarm that the energy-supply crisis has officially arrived. This includes Chevron (CVX) CEO Mike Wirth, who noted at an energy conference on Friday that the short-term efforts to mitigate the supply crisis “have largely now played out.” This includes the depletion of strategic stockpiles around the world, which can no longer provide a buffer to offset a record supply deficit. The market is sending the same message, with oil prices now firmly above $100 per barrel and refined products like diesel trading above $200 per barrel.

3. Bond yields break out across the globe. The U.S. 10-year bond yield hit 5.04% overnight, reaching the highest level since 2007. Across the pond, the 10-year bond yields in the UK, France, and Germany have all hit their highest levels since 2009. And in Japan, the 10-year bond yield is now at 3% – the highest level since 1996. With government debts ballooning and a building energy crisis feeding into higher inflation, this will likely keep the upward pressure on borrowing costs globally.


Chart Of The Day… APA (APA)

Shares of oil-exploration firm APA (APA) have soared 105% over the last year and 161% since we recommended them in Porter & Co’s Asymmetry, an advisory offered exclusively to Partner Pass members.


Today’s Poll

Tomorrow, the Federal Open Market Committee (“FOMC”), led by Federal Reserve Chair Kevin Warsh, will vote on future interest rate policies. Markets are pricing in roughly a 90% chance of a 25-basis-point interest rate hike because of a higher-than-expected August consumer price index (“CPI”) report and oil trading above $100 per barrel.
Loading
Please enable JavaScript in your browser to complete this form.

Mailbag

In yesterday’s Journal, Porter wrote that the rise of yields on 10-year Treasuries to 5% will cause inflation to break out – as a result, the Fed will face a choice past Fed Chair Paul Volcker never faced: it will have to choose between fighting inflation and keeping the Treasury solvent.

“The Seventies”

Jim H. writes:

I appreciate the ’70s history, as I lived through it, and the technical explanation that I can understand. Thanks.


“It’s Very Scary”

William S. writes:

Thank you for the advice. It’s very scary. I’ve been investing in gold shares with Garrett Goggin at Golden Portfolio, 40%. I have some in gold coins, 15%, and the rest in cash.


“Thank You So Much”

Thomas V. writes:

I always feel like I’ve learned something whenever I read your commentary. Thank you so much. I’ve been following your work since around 2006 or so and I feel blessed to have found you.


Porter & Co. Market Snapshot

Price Yesterday’s Return Year-to-Date Return
S&P 500 Index $7,619.98 -0.48% 12.2%
Gold per ounce $4,299.64 -0.79% -1.0%
Bitcoin $79,085 2.28% -12.3%
Oil (West Texas Intermediate) per barrel $101.39 -0.84% 78.4%
Berkshire Hathaway (BRK) $771,770.02 0.75% 2.2%
Porter’s Permanent Portfolio – 0.54% 3.8%
The Better Than Berkshire Index – 0.36% 7.0%
Total Return Annual Return
Porter & Co’s Top Ranked* 35.0% 15.9%
Yield Yesterday’s Change Change
Year-to-Date
U.S Treasury 30-Year Yield 5.34% -1 bps 50 bps
Prices as of 4:00 pm ET September 14, 2026 | bps = basis points (or 0.01%)
*A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


Porter & Co. Top Positions

Publication Ticker Description Total Return
Biotechnology QURE uniQure 237%
Biotechnology SGMT Sagimet Biosciences 202%
Complete Investor BTC/USD Bitcoin 189%
Biotechnology ROIV Roivant Sciences 181%
Complete Investor BWXT BWX Technologies 162%
Biotechnology TGTX TG Therapeutics 152%
Complete Investor PM Philip Morris 141%
Complete Investor SKWD Skyward Specialty Insurance 137%
Biotechnology SGMT Sagimet Biosciences 135%
Biotechnology NUVB Nuvation Bio 134%
Prices as of 4:00 pm ET September 14, 2026


Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

The post Important Allocation Update appeared first on Porter & Co..

  • ✇Porter & Co
  • Ten-Year Rates Move Over 5%: The First Step Toward A Monetary Reset Porter &#38 · Co.
    Issue#158, Volume#3Why Now Is The Most Dangerous Time For Your Savings In 50 Years Inside Today’s Issue Essay: The First Step Toward A Monetary Reset Inflation Expectations Rise AI Leaders Call For A Pause Trump Gives Support For Crypto Bill Chart Of The Day… 10-Year Treasury Yield Today’s Mailbag Edit Delete Editor’s note: Join Porter for his new Ignition Point broadcast this Wednesday and discover how several separate technological forces are fusing to create what Porter calls “
     

Ten-Year Rates Move Over 5%: The First Step Toward A Monetary Reset

14 September 2026 at 13:00

Issue#158, Volume#3

Why Now Is The Most Dangerous Time For Your Savings In 50 Years


⚙ Edit 🗑 Delete

Editor’s note: Join Porter for his new Ignition Point broadcast this Wednesday and discover how several separate technological forces are fusing to create what Porter calls “the next Mag7.” Secure your seat here.


As I’ve been warning could happen since March, yields on the 10-year Treasury bond are now trading above 5%.

The 10-year U.S. Treasury bond yield jumped to 5.005% in the minutes after the August inflation report hit the wire last Friday – the 10-year traded above the 5% level again this morning. Both times, as soon as the yield broke above 5%, there was a massive intervention in the market forcing yields lower. I suspect the Fed is actively suppressing rates. Or it could be the Treasury issuing more short-term bills and buying longer term bonds.

My new book 2029 The End Of America: Why The Age Of Paper Money Is Ending And How To Survive The Coming Global Monetary Reset explains exactly why this is a very dangerous situation, not just for investors, but for our entire country. I write on page 29:

When Powell raised the federal funds rate from zero to 5%, he did not just cool the economy — he tripled the United States government’s annual interest expense. Net interest on the national debt went from $345 billion in October 2020 to $981 billion in October 2025. That is more than the entire defense budget of the United States of America… The next time inflation breaks out — and it will break out, because the structural forces driving it have not been addressed and the monetary expansion of 2020–2022 has not been meaningfully reversed — the Fed will face a choice Paul Volcker never faced: it will have to choose between fighting inflation and keeping the Treasury solvent. It cannot do both. And because no democracy in the history of the human race has ever chosen Treasury-solvency-and-austerity over inflation when the choice was forced upon it in a moment of crisis, the Fed will choose inflation.

What’s happening today — in the markets, with the Iran War, and in our politics — is almost exactly what happened the last time there was a huge, global monetary reset, which was in the early 1970s when the U.S. defaulted on its promise to redeem dollars for gold.

That decision unleashed a new, global fiat monetary regime that’s seen asset prices soar while wages stagnated, destroying the middle class in America. It led to a decade of much higher inflation rates and much higher interest rates from 1971-1981. By the time the 1970s monetary reset was over, long-term rates were 15% annually, high-quality stocks were trading at six times earnings, and the dollar’s purchasing power had fallen by more than 50%.

Could that really happen again? Absolutely.

Last year, the federal government ran a deficit of almost $2 trillion, spending 34% more than it collected. The government, already supporting unprecedented debts, is running a deficit that is 6% of GDP — during peacetime and with full employment!

This hasn’t happened since the 1970s.

And look at our politics. Who reminds you of President Richard Nixon more than President Donald Trump? Trump issued roughly 225 executive orders in the first year of his second term, and, like President Barack Obama (!), is using law enforcement to settle political scores. He’s the most “imperial” president we’ve had since Nixon. (Obama! was the most insufferable.)

The difference between 1971 and today is that the federal government is vastly larger and the spending is even more out of control. Today, all state and local governments combined spend around $3.7 trillion annually. That’s only half of federal outlays: the federal government spends more than the other 50 states, combined.

And then there’s the war.

In October 1973, Egypt and Syria attacked Israel on Yom Kippur. The Arab oil producers answered with an embargo, and oil ran from $3 a barrel to nearly $12 in a matter of weeks. America’s involvement in this war was never about Israel. It was always a war over the dollar. The Saudis had threatened to stop pricing oil in dollars after Nixon broke the gold promise in 1971. The war, and the secret petrodollar arrangement that ended it, kept oil priced in dollars for 50 years and allowed America to run endless trade deficits financed purely with paper money. That deal ended in 2024. And look whose oil industry is being destroyed in this war: Saudi Arabia’s. That’s not a coincidence.

There’s one other major similarity between today and the early 1970s that no one is talking about yet: the urgent need for entitlement reform.

In the 1972 election year, Congress and Nixon gave Social Security recipients a 20% across-the-board benefit increase.

Trump is promising something even bigger in this election: a $5,000 “dividend” for voters if the Republicans win both the Senate and the House.

But it’s the 1972 law that’s the real risk. The Social Security Amendments of 1972 did something no government had done to itself before: it wired future benefits directly to inflation. Starting in 1975, guided by the consumer price index (“CPI”), checks would rise automatically every year. No vote required, ever again.

When inflation ran higher in the late 1970s, one of the main reasons it was so hard to control was because federal spending was mandated to increase alongside inflation. The first automatic cost of living adjustment (“COLA”), in 1975, was 8%. By 1980, it was 14.3%. The government had built a machine that took the very inflation it was causing and fed it straight back into its own largest expense, automatically.

So… what caused the inflationary spiral of the 1970s? A deranged, imperial president who refused to cut spending even when it was obviously out of control, a war in the Middle East that disrupted oil supplies for a decade, and an entitlement system that vastly increased spending, automatically because it was indexed to inflation.

And what do we see today?

The federal government is $40.1 trillion in debt, running close to $2 trillion in annual deficits, and the two fastest-growing line items (Social Security and interest expenses) are linked to inflation. Printing money won’t cure these obligations – it will make them grow faster.

The Strait of Hormuz has effectively been shut for over 100 days, and Houthi attacks on tankers in the Red Sea have added a second front. There’s already been substantial damage to major energy infrastructure, and there’s no end in sight to this conflict. Oil is above $100 a barrel.

The CPI rose 3.4% in August and has been above the 2% rate for 66 consecutive months – more than five years. That’s driving massive increases to Social Security payments, with 2027’s COLA expected to be 3.7%. The program, which has been operating in the red since 2010, currently pays out about $138.4 billion a month, or roughly $1.66 trillion a year, to 71.3 million beneficiaries. A 3.7% COLA adds about $5.1 billion a month to that, or $62 billion more a year. And that’s before counting the roughly 1.5 million new beneficiaries who join the rolls annually.

America’s federal government is a leviathan spiraling toward insolvency with a printing press. You know what it’s going to do. It is going to defraud its creditors.

How? In all kinds of ways. By defaulting on Social Security (yes, that will absolutely, 100% happen). And by resetting the value of our currency much lower, thus making it easier to repay its debts. That’s exactly why long-duration interest rates are going much higher.

That will not be good for equity valuations. It will also not be good for our country. The 1970s were a period of tremendous political violence. And this time will be worse.

If you haven’t yet, now is a very good time to read my book.

It’s available at Amazon.com, both as a paperback and on Kindle. You can also listen to it as an audiobook. It’s only $9.99 (via Kindle). Please read it. And give a copy to someone you love. It’s a thorough guide to protecting your wealth from the coming monetary reset.

P.S. Attentive readers will recall that earlier this year (in March) I suggested that retired investors, or investors who didn’t want to face a lot of volatility this year, should sell the property-and-casualty (P&C) insurance allocation in Porter’s Permanent Portfolio and move those assets to short-term Treasury bills (SHY). Doing so would create a Permanent Portfolio asset allocation that’s ready for higher inflation and higher interest rates: 25% stocks, 25% gold and Bitcoin, and 50% cash. I explained that when the 10-year Treasury yield broke above 5%, I would move our official allocations to match this conservative allocation. I haven’t done that yet, because, so far, the 5% level hasn’t held. When I change our official allocations, I’ll let Complete Investor subscribers know.

Tell me what you think of today’s Daily Journal: porterstansberrydirect@gmail.com

Good investing,

F. Porter Stansberry
Stevenson, Maryland

Presented By: Paradigm Press

Oil Prices Could Send These Three Stocks Soaring

If the turmoil in the Middle East has you rushing to buy oil stocks right now – STOP and read this.

The biggest gains from the last oil crisis didn’t come from oil companies.

The top-performing energy stocks were tiny. Practically unknown. And every major oil company in America was completely dependent on them.

Today, it’s the exact scenario— except the scale is roughly 13,000 times larger.

That’s why I just vetted three of these companies in this exact same position.

But this time it’s not just oil that’s driving them higher…

Trump’s latest initiative could lead this sector to a major surge.

Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Paradigm Press is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.


3 Things To Know Before We Go…

1. Year-ahead inflation expectations jumped to 4.6%… The University of Michigan September survey index is up from 4.0% in August. Roughly 37% of consumers spontaneously named tariffs as a concern, the most since April, while about 30% named prices at the pump. Those are two separate supply shocks landing on the same household budget, and neither is the kind of inflation a central bank can wait out. Markets are pricing in an 81% chance of a rate hike for Wednesday’s Fed meeting.

2. AI leaders push for a pause. Last week, a former researcher for leading AI platform Anthropic made headlines after publicly resigning and warning that the leading frontier labs are racing recklessly toward dangerous “superintelligence.” Over the weekend, AI leaders including OpenAI head Sam Altman, Anthropic CEO Dario Amodei, and X owner Elon Musk called for slowing the pace of AI development. Critics argued that regulations on AI would favor these incumbents at the expense of lower-cost, open-source alternatives that have begun taking market share from OpenAI and Anthropic. The prospect of a slower pace of AI development sparked a sell-off across the data-center supply-chain complex, including the semiconductor sector, which fell by 4% on the news.

3. Trump concedes on crypto ethics, clearing the path for the Clarity Act. Late Sunday, Senate Republicans released what they called the final text of the bill, which would create the first comprehensive federal rulebook for crypto. President Trump reportedly agreed to roughly 80% of a bipartisan ethics proposal from Senators Thom Tillis (R., NC) and Ruben Gallego (D., AZ) that Senate Democrats had demanded for approval. Tomorrow at 2:15 p.m. ET, the Senate votes on cloture, the step that ends debate and lets the bill advance. That takes 60 votes. With at least two of 53 Republicans expected to vote no, about nine Democrats must cross over to support it. Prediction market Kalshi now puts the odds of ultimate passage at close to 50%, up from just 18% before the text came out.


Chart Of The Day… 10-Year U.S. Treasury Yield

The yield on the benchmark 10-year U.S. Treasury Note briefly touched 5.011% this morning, its highest level since July 2007.


Mailbag

On Friday, Porter wrote in the Daily Journal that AI and tech are essential tools for the success of any business – so much so that in a decade we will no longer think of something being a tech stock since any successful company will have tech to thank for their staying power.

“Everyone Should Read This”

Stephen B. writes:

Every student, every job seeker, every investor, and even philosophers should be exposed to this analysis.

This is an excellent example of inductive reasoning about a process that excels at deductive conclusions. I hope it will be discussed in our educational institutions as guidance about how and where AI can assist humanity. AI is not a competitor for “intelligence” – it does not originate inductive discoveries. It reports deductive conclusions based on existing data bases.


Luke S. writes:

Good, solid article!


Porter & Co. Market Snapshot

Price Friday’s Return Year-to-Date Return
S&P 500 Index $7,656.98 0.86% 12.8%
Gold per ounce $4,349.08 0.72% -0.8%
Bitcoin $77,318 0.21% -11.3%
Oil (West Texas Intermediate) per barrel $100.05 -4.09% 80.3%
Berkshire Hathaway (BRK) $766,000.00 0.62% 1.5%
Porter’s Permanent Portfolio – 0.25% 3.2%
The Better Than Berkshire Index – 0.39% 6.7%
Total Return Annual Return
Porter & Co’s Top Ranked* 35.4% 15.6%
Yield Friday’s Change Change
Year-to-Date
U.S Treasury 30-Year Yield 5.35% -1 bps 35 bps
Prices as of 4:00 pm ET September 11, 2026 | bps = basis points (or 0.01%)
*A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


Porter & Co. Top Positions

Publication Ticker Description Total Return
Biotechnology QURE uniQure 237%
Biotechnology SGMT Sagimet Biosciences 202%
Complete Investor BTC/USD Bitcoin 184%
Biotechnology ROIV Roivant Sciences 180%
Complete Investor BWXT BWX Technologies 165%
Biotechnology TGTX TG Therapeutics 152%
Biotechnology NUVB Nuvation Bio 139%
Complete Investor PM Philip Morris 137%
Biotechnology SGMT Sagimet Biosciences 135%
Biotechnology QURE uniQure 131%
Prices as of 4:00 pm ET September 11, 2026


Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

The post Ten-Year Rates Move Over 5%: The First Step Toward A Monetary Reset appeared first on Porter & Co..

  • ✇Porter & Co
  • Weekly Partner Monitor Porter &#38 · Co.
    Welcome to the Partner Monitor… one full week in one short email Recommended stocks, bonds, and funds: NAVI, QQQ… Porter & Co. Distressed Investing: Marty Fridson recommended both the stock and the bond for education loan company Navient (NAVI)… The issue also included a market analysis of distressed debt and a review of current recommendations. We sent this Porter & Co. Distressed Investing report on Saturday, September 12. See a summary below or… Read it here now.The Trading Club: In
     

Weekly Partner Monitor

14 September 2026 at 05:00

Welcome to the Partner Monitor… one full week in one short email

Recommended stocks, bonds, and funds: NAVI, QQQ…

Porter & Co. Distressed Investing: Marty Fridson recommended both the stock and the bond for education loan company Navient (NAVI)… The issue also included a market analysis of distressed debt and a review of current recommendations. We sent this Porter & Co. Distressed Investing report on Saturday, September 12. See a summary below or… Read it here now.

The Trading Club: In response to some macroeconomic risks, Ross Hendricks recommended a new hedging trade: buying to open an Invesco QQQ Trust (QQQ) $680 put, expiring October 16, 2026. Ross alerted members to this trade on Friday, September 11. See a summary below or… Read it here now.

Sunday Screener: This week we dialed in Porter’s 3X Screen and produced a list of 29 companies, plus shared the 52-week highs and 52-week lows in the Sunday Screener. We emailed this Sunday Screener on September 13. See a summary below or… Read it here now.

Daily Journal: Porter kicked off the short week with an analysis of Big Pharma company Novartis (NVS) – both a Biotechnology and High Conviction recommendation that had disappointing results from an FDA Phase III trial. On Wednesday, he detailed the dire shortage in the global fuel supply, namely diesel. On Thursday, Marty Fridson shared his thoughts on prediction markets, gambling, and the stock market. And Porter ended the week on Friday extolling the virtues of AI in particular and tech in general… Read the Daily Journal here now.

Digging Deeper


Porter & Co. Distressed Investing

Porter & Co. Distressed Investing released its recommendation of Navient (Nasdaq: NAVI) – a financial-services company currently pivoting from its legacy of government-guaranteed student loans toward a high-growth private lending business. Its history is rooted in the 1965 Higher Education Act, which established a system of federally guaranteed student aid. Following the 2014 split from Sallie Mae, Navient inherited a large portfolio of these government-backed loans.

Navient’s recent trajectory was significantly impacted by a 2017 CFPB civil complaint regarding servicing practices, which was settled in 2024. As part of this resolution, Navient is permanently barred from originating new federally guaranteed loans, though it continues to manage its existing portfolio.

In response, Navient has shifted its focus to private lending, largely through its acquisition of Earnest. This segment targets high-credit-score, high-income graduates, and growth is being accelerated by the 2026 elimination of the federal “GradPLUS” program. With a combined portfolio of approximately $43 billion, Navient manages both its legacy government-backed loans and its expanding private lending business.

We recommended a “package” of Navient’s 11.5% bonds (maturing March 2031) and its common stock – 25 shares for each bond purchased. The bonds offer a significant yield in a market where similarly rated assets pay less, while the stock trades at a large discount to its net asset value. Despite regulatory history and a declining legacy portfolio, Navient projects strong long-term cash flows, supported by disciplined expense management and the growth of its private loan segment, making it a compelling candidate for income-focused investors… Click here to read the full report from Saturday, September 12.


The Sunday Screener

On Sunday, we revisited a popular stock-filtering tool we call “Porter’s 3x Stock Screen.” Over the last 25 years, buying an equally-weighted basket of stocks generated from the 3x screen has tripled the return over the overall stock market (the S&P 500). In the issue, released Sunday, September 13, we also show the names of significant stocks hitting 52-week highs and 52-week lows – a helpful list that we use to guide our analysis.

The 3x Screen was inspired by Porter himself, who challenged the Complete Investor analyst team to create a filtering tool to find companies with high capital efficiency, steady revenue growth, and that trade at reasonable valuations… and to backtest the results to ensure the screening criteria selected stocks that generated market-beating gains over time… To see the issue, click here.


The Trading Club

On Friday, Ross Hendricks provided an update and trade alert for The Trading Club. Ross emphasized a shift toward a more defensive strategy in the trading service amid escalating market risks. He highlighted a concerning surge in bond yields – with 10-year Treasury yields nearing 5% – and an intensifying energy crisis driven by Middle East conflicts. With U.S. crude prices rising and global refining capacity at historical lows, these energy shocks are increasingly likely to stifle consumer purchasing power, potentially foreshadowing a broader market downturn.

In response to these risks, The Trading Club recommended a new hedging trade: buying to open an Invesco QQQ Trust (QQQ) $680 put, expiring October 16, 2026. The portfolio, which has returned 7% year-to-date, currently lags the S&P 500’s 12% gain, largely because the team has avoided the AI-driven tech rally while maintaining hedges against it. Despite this performance gap, the team reaffirmed their three-part strategy: identifying high-quality stocks, selling options for income, and hedging downside risks. No fundamental changes to this process are planned.

Operationally, due to the upcoming Porter & Co Annual Conference (September 23–24), the next quarterly trade series is delayed until late October. An interim series of trades expiring October 16 will be published on September 21 to bridge this gap. Finally, the update addressed subscriber questions regarding portfolio performance and specific holdings, while hinting at emerging opportunities in the fertilizer supply chain as the team explores new ways to hedge supply risk… To see the full report, click here.


The Week In Porter’s Daily Journal…

On Tuesday, Porter kicked off the short week with an analysis of Big Pharma company Novartis (NVS), which had disappointing results from an FDA Phase III trial for its heart and cholesterol drug pelacarsen… See it here now.

On Wednesday, he detailed the dire shortage resulting from the ongoing war in Iran in the global fuel supply, namely diesel – making the comparison to cotton shortages that emerged during the U.S. Civil War… See it here now.

On Thursday, Marty Fridson shared his thoughts on prediction markets, gambling, and the stock market… See it here now.

On Friday, Porter returned to the Journal to extol the productivity and other great benefits of artificial intelligence to business and society… See it here now.

… Read the Daily Journal here now.


What’s Up Next Week…

The Complete Investor team will be releasing a new stock recommendation on Saturday, September 19.


The post Weekly Partner Monitor appeared first on Porter & Co..

  • ✇Porter & Co
  • The Highs And Lows Of Drug Development Porter &#38 · Co.
    Issue#154, Volume#3Updates On Novartis And Roivant Sciences Inside Today’s Issue Essay: The Highs And Lows Of Drug Development Declining Treasury Returns Insider Buying At Uber Japan’s Yen Support Chart Of The Day… Roivant Sciences (ROIV) Today’s Mailbag We don’t normally update stock recommendations from our various services in the Daily Journal, but from time to time something happens that’s important enough to discuss with the entire audience. On Friday, Porter & Co. Biotechnology r
     

The Highs And Lows Of Drug Development

8 September 2026 at 13:00

Issue#154, Volume#3

Updates On Novartis And Roivant Sciences


We don’t normally update stock recommendations from our various services in the Daily Journal, but from time to time something happens that’s important enough to discuss with the entire audience.

On Friday, Porter & Co. Biotechnology recommendation Novartis (NVS) announced that its heart and cholesterol drug pelacarsen failed in a Food And Drug Administration (“FDA”) Phase III trial to reduce cardiovascular events despite lowering the harmful cholesterol Lp(a).

One of our main themes in Porter & Co Biotechnology is a technology called RNA interference. It can prevent harmful proteins from being produced inside cells, before they cause harm in your body. As this intervention occurs earlier in the pathology of disease and inside cells, it has a good safety profile and can be extremely effective. We believe it’s going to become a dominant new approach to treating chronic disease.

One of the biggest potential market opportunities for RNA interference is preventing the production of certain kinds of cholesterol that are linked to cardiovascular disease (heart attack, stroke). Cardiovascular disease is a leading cause of death, so there are potentially huge markets for these drugs – if they’re safe, and if they can prevent disease.

Novartis has been conducting a six-year-long, huge (8,323 people) clinical trial (“HORIZON”) using an older form of RNA interference (antisense) to target lipoprotein(a). Lp(a) is a cholesterol-carrying particle found in the blood. It resembles an LDL particle, the type commonly called “bad cholesterol,” with an additional protein called apolipoprotein(a) attached to it.

Your genes determine most of your Lp(a) level. Diet, exercise, and statins generally do little to change it. People born with high Lp(a) experience more heart attacks, strokes, and aortic-valve disease over their lifetimes. And currently there’s no FDA-approved treatment to reduce Lp(a), which makes it one of the most valuable potential drug targets in medicine.

Novartis’ Lp(a) drug is called pelacarsen. On Friday afternoon, Novartis announced that pelacarsen did not lower the risk of cardiovascular events in the treatment population of the clinical trial. We don’t have complete data from the trial, so we don’t know exactly how it failed. We do know that Pelacarsen did what an antisense drug is supposed to do: it lowered the protein it was designed to lower. The problem is that patients did not suffer fewer cardiovascular events as a result.

There’s a lot of controversy about cholesterol drugs (statins) already. Many people claim that LDL isn’t the cause of heart attacks. While cardiovascular disease is multi-faceted, there’s no question that lowering LDL, especially before cardiovascular disease has begun, can dramatically reduce the risk of heart attack and stroke. We know this because some people have natural mutations that result in much lower levels of LDL and they have much less (88% less, in one landmark study) incidence of heart disease. Likewise, some people have natural mutations that lead to much higher levels of LDL – they get heart disease when they’re still very young.

Using drugs to replicate lower levels of LDL improves cardiovascular health: The Cholesterol Treatment Trialists combined 26 randomized trials containing 170,000 participants. Each 38.7 milligram-per-deciliter (“mg/dL”) reduction in LDL produced a 22% reduction in major vascular events and a 10% reduction in overall mortality. A meta-analysis of patients beginning at very low LDL levels found a 21% reduction in major vascular events for every 38.7 mg/dL reduction, combining statins and nonstatin drugs.

I’m explaining all of this because I suspect there will be a lot of people (especially on the internet) who point to this clinical-trial failure and then claim that cholesterol isn’t a factor in heart disease. But that isn’t what this trial means. LDL has bidirectional genetic evidence and repeated outcome benefits from several mechanistically different drugs.

Still, if high Lp(a) leads to heart attack, then why didn’t lowering it reduce heart attacks?

Pelacarsen is an antisense oligonucleotide (“ASO”) – a short, manufactured strand of genetic material designed to bind to one specific messenger RNA. When pelacarsen binds to the message for apolipoprotein(a), the cell destroys that message. With fewer instructions available, the liver makes less apolipoprotein(a), and the patient’s Lp(a) level falls.

What The Trial Tested

This clinical trial enrolled 8,323 patients who already had cardiovascular disease and Lp(a) levels of at least 70 mg/dL. Patients received either an 80-milligram pelacarsen injection once a month or a placebo injection containing no active drug. Neither the patients nor their doctors knew which treatment they received (this was a “double-blind” clinical trial).

The trial measured a composite endpoint. A composite endpoint combines several medical outcomes into one score so that the trial can accumulate enough events to reach a conclusion. The Pelacarsen trial, Lp(a)HORIZON, counted the first occurrence of cardiovascular death, a nonfatal heart attack, a nonfatal stroke, or an urgent procedure to restore blood flow to the heart.

Researchers often call this collection of outcomes MACE – major adverse cardiovascular events. Pelacarsen did not significantly reduce these events in the overall trial population, even though it lowered Lp(a).

“Did not significantly reduce” has a precise meaning. The difference between pelacarsen and placebo was not large or consistent enough for the trial to rule out chance under its pre-specified statistical test. Novartis has not disclosed the actual difference, known as the hazard ratio, or the range of plausible values around it, known as the confidence interval.

We therefore do not yet know whether pelacarsen produced no benefit, a small benefit, or a benefit concentrated among patients with the highest Lp(a). Novartis also has not disclosed the separate event counts, the amount of Lp(a) lowering achieved during the study, or the complete results for patients who started at 90 milligrams per deciliter or higher.

Why Pelacarsen May Have Failed

  1. Lp(a) may identify cardiovascular risk without being a useful drug target. A marker can predict disease without causing enough of the disease to make its removal helpful. Medicine has seen this before: raising HDL cholesterol improved a laboratory number but did not reliably prevent heart attacks.
  2. Treatment may have started too late. Genetic studies measure the effects of high Lp(a) across an entire lifetime. Lp(a)HORIZON began treatment after patients already had cardiovascular disease. Lowering one source of damage for several years may not reverse decades of plaque formation and injury.
  3. Pelacarsen may not have lowered Lp(a) far enough. Its earlier trials produced reductions near 80%. Competing siRNA drugs have produced reductions above 90%. If cardiovascular benefit requires crossing a threshold rather than merely lowering the level, the deeper reduction could matter.
  4. The trial may have enrolled too many patients whose remaining risk came from something other than Lp(a). The median starting Lp(a) was 108 milligrams per deciliter, and 21.4% of patients entered below 90 milligrams per deciliter. About 77.5% received high-intensity statins, and roughly 11% received a PCSK9 inhibitor.

PCSK9 inhibitors are powerful LDL-lowering drugs. A 2025 analysis of 273,770 patients with established cardiovascular disease found that the connection between Lp(a) and recurring cardiovascular events weakened as LDL treatment intensified and disappeared statistically among patients receiving PCSK9 inhibitors. If modern treatment had already removed much of the risk attributable to Lp(a), pelacarsen had little left to prevent.

The missing results will distinguish these explanations. We need the actual event rates, the hazard ratio, the confidence interval, the achieved Lp(a) levels, and the results among patients starting at 90 mg / dL or higher. We also need to know whether the event curves moved apart late in the study, which would suggest that benefit requires more time.

What The Result Means For Lp(a)

Lp(a) remains a genetically established risk factor.

Genetic evidence tells us that people exposed to high Lp(a) for decades have more disease. A successful clinical trial must show that lowering Lp(a) with a drug, later in life, improves patient outcomes. Pelacarsen failed that test.

The next decisive Lp(a) study belongs to Amgen (AMGN). Its drug, olpasiran, is being tested in an ongoing large-scale trial called “OCEAN.” This trial required a higher starting Lp(a), uses an siRNA that produces deeper lowering, and excludes stroke from its three-part primary endpoint. Those differences address several possible weaknesses in Lp(a)HORIZON. But they do not guarantee success.

Eli Lilly’s (LLY) lepodisiran also uses siRNA to target Lp(a) and is being tested in a larger population that includes some patients without established cardiovascular disease. Lilly’s muvalaplin is a daily pill that prevents Lp(a) particles from assembling rather than silencing messenger RNA (“mRNA”).

What Does This Setback Cost Novartis…?

Ionis Pharmaceuticals (IONS) discovered pelacarsen. Novartis licensed it and became responsible for worldwide development, manufacturing, and commercialization.

The contract allowed Ionis to receive as much as $900 million. The amount included a $75 million upfront payment, a $150 million license payment, a $25 million development payment, up to $290 million tied to regulatory progress, and up to $360 million tied to sales. Ionis had received more than $275 million through the end of 2025. It would have received another $50 million if the FDA accepted a pelacarsen application.

Novartis has never disclosed the cost of Lp(a)HORIZON. Our reconstruction is $250 million to $700 million, with $450 million as the base estimate. The study operated for more than six years, enrolled 8,323 patients at 902 sites, administered monthly injections, and continued until independent reviewers confirmed 993 cardiovascular events.

Novartis paid Ionis more than $65 million for a separate next-generation Lp(a) ASO program that it terminated in 2025. Including that program, other pelacarsen studies, drug manufacturing, launch preparation, Lp(a) testing campaigns, and the original Ionis equity investment, our total Novartis Lp(a) spending estimate is $850 million to $1.55 billion.

Here’s what matters to shareholders: Novartis expensed the clinical work as it occurred. Pelacarsen has no current sales. Its failure therefore has almost no effect on 2026 earnings.

The pelacarsen call option from our August recommendation should be treated as lost. But Novartis is a broadly diversified, major pharmaceutical company. It does not depend on pelacarsen alone. Its LDL drug, Leqvio, is growing rapidly. It silences PCSK9 rather than apolipoprotein(a), lowers LDL cholesterol rather than Lp(a), and operates in a pathway already validated by successful outcomes trials using PCSK9 antibodies.

Our August valuation was $180 per Novartis share. We don’t believe the failure of this trial impacts that valuation by more than $2 to $4 per share. Our next evaluation will occur when we get the full Lp(a)HORIZON data set.

What’s actually driving the share price of Novartis down today was a different clinical trial failure. And it matters more because this was a major ($12 billion) acquisition, not just a licensing deal.

Earlier this year, Novartis bought Avidity Bioscience, which was a clinical-stage biotech company developing RNA medicines for inherited muscle diseases.

Avidity’s core technology is an antibody that can deliver RNA drugs into muscle cells. The company had three advanced programs, including a Del-desiran for myotonic dystrophy (type 1). This inherited muscle disease causes weakness and myotonia: the inability to relax a muscle normally after using it.

The drug uses small interfering RNA, or siRNA, to destroy the toxic genetic message that causes DM1. An antibody carries Avidity’s siRNA into muscle. Earlier biopsies proved that this delivery system worked: del-desiran reached human muscle and reduced its intended RNA target by 37% to 46%. Its Phase III clinical trial (“HARBOR”) enrolled 159 patients. Its primary test measured how quickly patients could open their hands after squeezing them. Del-desiran did not improve that measurement significantly versus placebo. Novartis said other measures showed some clinical activity, but it has not released the full data.

The failure does not prove that the drug missed its molecular target or that Avidity’s muscle-delivery system is broken. The trial may have used a noisy new measurement, enrolled too few patients for a variable disease, treated them for too little time, or failed because partial correction of the molecular defect cannot restore damaged muscle. The complete strength, walking, daily-activity, and biological results will distinguish those explanations.

But, a lot more money is at stake in these drugs. Novartis assigned $7.5 billion of the purchase price to Avidity’s muscular dystrophy programs. If del-desiran is abandoned, most or all of that accounting asset could be written off. Our base estimate is a $6.2 billion loss of equity value, or about $3.25 per Novartis share.

While failed clinical trials are never good news, these are normal costs. We see no reason to change our outlook on Novartis and continue to expect it to become the market’s leading RNA-interference company.

And… there’s a reason we take a portfolio approach to our biotech investing.

Roivant Sciences (ROIV) is up about 20% today on strong Phase II results for mosliciguat in pulmonary hypertension caused by interstitial lung disease. Mosliciguat is an inhaled medicine designed to relax the blood vessels in damaged lungs, making it easier for the heart to pump blood through them. The drug reduced resistance in the lung’s blood vessels by 56.3% versus placebo. Patients also walked 35.2 meters farther in six minutes, while NT-proBNP, a blood marker of cardiac strain, fell 53.2%. The result is persuasive because the drug improved three different things: blood flow through the lungs, patients’ physical ability, and stress on the heart. Roivant has begun Phase III (“PHrontier”).

Tell me what you think of today’s Journal: porterstansberrydirect@gmail.com

Good investing,

F. Porter Stansberry
Stevenson, Maryland


Presented By: Katusa Research

The Scale Of What Is Coming

Roughly every reactor on earth — built again, by one country.

This administration intends to quadruple America’s nuclear capacity to 400 gigawatts. That is more nuclear power than the United States, France, China, Russia and South Korea operate combined — those five countries being 71% of all capacity on earth.

● One gigawatt powers roughly 700,000 American homes

● Uranium has not been in surplus since 2016

● $80 billion partnership signed with Westinghouse Electric

Read the full analysis

Sponsored content from Katusa Research. Not investment advice. Speculative resource investing involves substantial risk of loss; past performance is not indicative of future results. Katusa Research is located in Vancouver, BC, Canada.

Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Katusa Research is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.


3 Things To Know Before We Go…

1. U.S. Treasury bonds have lost money over the past decade. U.S. government debt maturing in 15 years or more returned roughly -2% a year over the 10 years through August, according to BofA Global Investment Strategy. That is the worst 10-year stretch since 1936, and the only time the figure has dropped below zero. The math is simple: the 30-year Treasury yielded 2.23% in September 2016 and yields 5.25% today. Bond prices fall when yields rise, and the longer the bond’s duration, the further it falls. The iShares 20+ Year Treasury Bond ETF (TLT) has dropped 52% from its July 2020 peak – a deeper decline than the S&P 500 suffered in 2008.

2. A big insider buy at Uber. Uber Technologies (UBER) president and COO Andrew Macdonald bought 70,000 shares on the open market on September 4 at $75.83 – a $5.31 million purchase that boosted his holdings by 20%, to 426,320 shares. Macdonald sees the growth possibilities from the inside every day. After 14 years of equity compensation, he’s buying more with his own cash.

3. Japan sells Treasuries to fund currency intervention. Japan liquidated a record $88 billion of foreign securities in August, which includes U.S. Treasuries. The sales likely funded Japan’s $98.6 billion currency intervention in August, designed to shore up the yen after it fell near 40-year lows in July. As the largest foreign owner of U.S. Treasuries, any further pressure on the Japanese currency risks spilling over into additional weakness in the U.S. bond market.


Chart Of The Day… Roivant Sciences (ROIV) 

As Porter reported above, shares of Porter & Co. Biotechnology recommendation Roivant Sciences (ROIV) jumped 20% today to a new high after its Pulmovant subsidiary reported a record 56.3% reduction in pulmonary vascular resistance in a Phase II trial of mosliciguat – stacking a second catalyst on top of Lisraya’s early commercial launch.


Mailbag

On September 1, Porter & Co. released details of the latest buy signal for our Porter & Co. Systematic Crypto service, available to Partners.

“Very Informative”

Greg R. writes:

The article was very informative. Most especially, news of your Bitcoin (BTC) pricing model. Some time ago I became aware that the value of hard assets is correlated to economic liquidity, as opposed to market swings. Your writing has helped solidify that thesis for Bitcoin as well.

I have been purchasing small amounts for several years, and see no reason to stop, even as the price climbs. (Is there ever a reason not to buy good, quality assets if you have the means?)

I think that in my lifetime people who are late to find their way to BTC will speak of Satoshis as a unit of measure, not whole coins, because the price of a single BTC will be out of their reach. I’d back the truck up to it if I had the present means!


Schuler B. writes:

Fantastic – made Bitcoin so simply understood.


“Bitcoin?”

JM writes:

Bitcoin? I think I’ll stick with investing in insurance companies.


Porter & Co. Market Snapshot

Price Friday’s Return Year-to-Date Return
S&P 500 Index $7,718.60 -0.36% 13.6%
Gold per ounce $4,404.30 -0.51% 1.9%
Bitcoin $79,223 -0.87% -10.5%
Oil (West Texas Intermediate) per barrel $91.48 18.82% 61.8%
Berkshire Hathaway (BRK) $759,350 -0.48% 0.6%
Porter’s Permanent Portfolio – -0.87% 4.4%
The Better Than Berkshire Index – -1.05% 7.5%
Total Return Annual Return
Porter & Co’s Top Ranked* 35.6% 16.2%
Yield Friday’s Change Change
Year-to-Date
U.S Treasury 30-Year Yield 5.24% 0 bps 40 bps
Prices as of 4:00 pm ET September 4, 2026 | bps = basis points (or 0.01%)
*A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


Porter & Co. Top Positions

Publication Ticker Description Total Return
Biotechnology QURE uniQure 237%
Biotechnology SGMT Sagimet Biosciences 203%
Complete Investor BTC/USD Bitcoin 193%
Complete Investor BWXT BWX Technologies 178%
Biotechnology NUVB Nuvation Bio 168%
Biotechnology TGTX TG Therapeutics 158%
Biotechnology ROIV Roivant Sciences 155%
Complete Investor SKWD Skyward Specialty Insurance 133%
Biotechnology QURE uniQure 131%
Complete Investor PM Philip Morris 128%
Prices as of 4:00 pm ET September 4, 2026

Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

The post The Highs And Lows Of Drug Development appeared first on Porter & Co..

  • ✇Porter & Co
  • New Partner Benefit: Weekly Partner Monitor Porter &#38 · Co.
    Welcome to the Partner Monitor… one full week in one short email.  Recommended stocks, bonds, and funds: LLY, HALO, MSBT, ETH, BSOL, BHYP, COIN, GLXY, CRCL, FIGR, ASST, SBET, FWDI, PURR, SGOV… Porter & Co. Biotechnology: Porter recommended Big Pharma company Eli Lilly (LLY), which he calls the Nvidia of biotech… He also touts pharmaceutical royalty collector Halozyme Therapeutics (HALO). We sent this Porter & Co. Biotechnology report on Saturday, September 5. See a summary below or… R
     

New Partner Benefit: Weekly Partner Monitor

7 September 2026 at 05:00


Welcome to the Partner Monitor… one full week in one short email. 

Recommended stocks, bonds, and funds: LLY, HALO, MSBT, ETH, BSOL, BHYP, COIN, GLXY, CRCL, FIGR, ASST, SBET, FWDI, PURR, SGOV…

Porter & Co. Biotechnology: Porter recommended Big Pharma company Eli Lilly (LLY), which he calls the Nvidia of biotech… He also touts pharmaceutical royalty collector Halozyme Therapeutics (HALO). We sent this Porter & Co. Biotechnology report on Saturday, September 5. See a summary below or… Read it here now.

    Porter & Co. Systematic Crypto: Analyst Justin Brill unveiled this new service for Partners on Saturday, August 29, with a first buy alert on Tuesday, September 1. See a summary below or… Read it here now.

    The Trading Club: Ross Hendricks recommended covered-call trades on six positions of The Trading Club. He’s making new trades designed to generate income from several of our existing long positions to bring in upfront cash into the portfolio. Ross alerted members to this trade on Friday, September 4. See a summary below or… Read it here now.

    Sunday Selection: Sunday Selection focused on the high-growth loan and payment platform Affirm (AFRM). Our weekly Sunday Screener includes a biweekly “For Partners Only” Sunday Selection on a company we are watching. We emailed this Sunday Screener on September 6. See a summary below or… Read it here now.

          Daily Journal: Porter had two guest Journal writers this week in between his own fresh essays: the first of Porter’s was a critique of CoreWeave’s (CRWV) business model and the next explored the high cost in the shipping business. His guests this week included Tuttle Management CEO Matt Tuttle, writing about his ETF based on Porter’s Permanent Portfolio, and Marin Katusa sharing the latest news on gold. See a summary below or… Read the Daily Journal here now.

          Digging Deeper


          Porter & Co. Biotechnology

          Porter & Co. Biotechnology recommended Eli Lilly (LLY) and Halozyme Therapeutics (HALO). Porter made the following comparison: In 2010, the oil business turned from exploration to engineering – when drillers found new ways to dig. Output per rig in the Permian Basin went from 130 barrels a day in 2014 to 800 barrels a day by 2019… Nobody found more oil. They engineered more oil.

          Drug discovery is making that same turn right now. Artificial intelligence (“AI”) will play a growing role in testing new drug targets. AI will dramatically reduce the cost of discovery – figuring out more efficient, more effective, and cheaper ways of hitting the best targets.

          Our portfolio will be built around who owns the best engineering.

          Eli Lilly (LLY) is the best in the world at finding the best pharmaceutical companies to buy that have the leading drugs and delivery methods and it is also the best at building the best therapeutics itself.

          There’s no question, Porter writes, that Eli Lilly will be a leader in fields like gene silencing. And even though shares trade for more than $1,000 and the company’s enterprise value is more than $1 trillion, Porter says shares are cheap compared to what the company will earn over the next decade. On top of its smart acquisitions, Lilly is also a leader in innovation – and what it does with its weight-loss pill over the coming years could transform the entire industry.

          Action to Take: Buy Eli Lilly (NYSE: LLY) below $1,500 per share
          Porter recommends using an 80/20 allocation on this position, where you invest 80% of your capital into the equity and 20% of your capital into a long-dated call option with a strike price that is between 5% and 10% “out of the money.”

          He also recommended Halozyme Therapeutics (HALO). Most antibody drugs have to be dripped into a vein, which means the patient sits in an infusion chair for hours and the hospital bills for a nurse, a chair, and a bag. Halozyme owns an enzyme called rHuPH20 that temporarily loosens the mesh of tissue under the skin, so the same drug can be pushed in with a syringe in minutes. It licenses that enzyme to drug companies under the name ENHANZE and collects a royalty.

          Halozyme runs no trials, treats no patients, and files for no approvals. Roche Holding (SIX: ROG), Johnson & Johnson (JNJ), Takeda Pharmaceutical (TAK), Argenx (ARGX), and Bristol- Myers Squibb (BMY) do all of that. Halozyme cashes checks.

          In June royalty revenue rose 50% to $307.7 million, of which $152.2 million came from DARZALEX, the subcutaneous myeloma drug Johnson & Johnson sells.

          Management raised full-year guidance for the second time this year, to $1.84 billion to $1.91 billion of revenue and non-GAAP earnings of $8.65 to $9.00 a share, up from $7.75 to $8.25. And it bought 4.8 million of its own shares in the quarter for $332.8 million, at an average price of $69.30, under a $1 billion authorization that runs through 2028.

          Action to Take: Buy Halozyme Therapeutics (Nasdaq: HALO) up to $110 per share

          To read the full report, click here.


          Porter & Co. Systematic Crypto

          Porter & Co. Systematic Crypto analyst Justin Brill unveiled this new service for Partners on Saturday, August 29, with a first buy alert on Tuesday, September 1.

          Systematic Crypto offers two rules-based crypto portfolio strategies – Core and Frontier – built to beat Bitcoin where it matters: after taxes and across a full market cycle. As a Partner Pass member, you receive this service as part of your membership.

          We are launching Systematic Crypto sooner than we planned. Both strategies follow a single long-term trend measure on Bitcoin, evaluated at each month-end. Bitcoin, which traded near $62,000 in early August, is now over $77,000, and we realized that this measure was on pace to turn positive at Monday’s month-end close (August 31) – which would be the first new buy signal these rules have generated since the 2023 bull market began.

          Then on Tuesday, September 1, we confirmed its first real-time buy signal following the August 31 month-end close. What we explained is that the system is trend-following, not predictive; it identifies confirmations rather than attempting to call market bottoms. Historical backtesting suggests this type of signal, which follows months of bearish price action, often marks the beginning of an extended crypto rally.

          When we sent the alert on Tuesday, September 1, we advised subscribers to choose between two strategies:

          • Core: The flagship strategy, designed for the best risk-adjusted performance. It holds four crypto ETFs and a Treasury-bill reserve (five positions total).
          • Frontier: Builds on the Core foundation but adds exposure to emerging areas, such as businesses built on crypto and companies with tokenized balance sheets (13 positions total). It targets higher absolute returns while accepting greater volatility.

          The firm recommends allocating approximately 5% to 10% of investable assets to these strategies. Investors should use a U.S. brokerage account supporting commission-free trading and fractional shares to execute the target weights.

          Once positions are purchased, the system requires no daily monitoring. The rules operate in the background, with triggers for monthly trend checks, weekly circuit breakers, and quarterly rebalances. While these strategies may underperform the broad crypto market during certain periods to mitigate massive drawdowns, they are designed to outperform over a full market cycle. Here are the suggested investment allocations for each of the two strategies.

          To read the full report, click here.


          The Trading Club

          The Trading Club recommends covered calls on a number of existing positions

          In The Trading Club this week, Ross Hendricks shared new trades designed to generate income from several of existing long positions. These trades will bring in upfront cash into the portfolio while still leaving upside of 6% to 14% in additional capital gains over the next six weeks. Those trades include covered calls on Booz Allen Hamilton (BAH), Hims & Hers Health (HIMS), Figma (FIG), Novo Nordisk (NVO), Triple Flag Precious Metals (TFPM), and Turning Point Brands (TPB).

          The covered-call trades we recommended today are not about expressing a changing view on any of the underlying stocks. Instead, the goal is to reduce overall portfolio risk, but to do so in a way that still leaves significant upside on the table.

          As a reminder, when selling covered calls, we’re making the conscious choice to surrender the upside on the underlying stock at prices above the option strike price. By foregoing that upside to the call-option buyers, we generate a guaranteed return via the immediate cash proceeds collected upon the option sale, regardless of where the stock trades from here. So we’re locking in guaranteed income, while still retaining upside potential – in this case, between 6% and 14% across the various call strikes and the underlying stock prices for these trades. Over the relatively brief six-week time period until expiration, this upside potential works out to an average annualized return in the triple digits – which, of course, is very impressive.

          The value of The Trading Club tracking portfolio settled at $131,698 as of Thursday, September 3 – up 31.7% since the May 30, 2025, inception date. We made no trades this week.

          To read the full issue, click here.


          Sunday Selection

          The Sunday Selection on September 6 reported on loan and payment platform Affirm (AFRM) – a true “Emerging Lindy,” a young company possessing the traits of durable, long-lasting businesses like Visa or American Express. Founded in 2012 by Max Levchin (a co-founder of PayPal), Affirm was built to fix a credit system it views as predatory, replacing revolving debt and hidden fees with transparent, fixed-payment “buy now, pay later” (BNPL) loans.

          Affirm’s business model succeeds by underwriting transactions in real-time, aligning profit with consumer repayment rather than failure. The company overcame the “cold-start” problem of building a new payments network by proving it could increase merchant demand – driving conversion rates and larger carts – which attracted major partners like Amazon and Shopify.

          With the core e-commerce business reaching profitability, Affirm is currently pursuing three strategic “S-curves” for growth:

          • E-commerce: Already largely established with over 60% of U.S. e-commerce running through Affirm-enabled merchants
          • Affirm Card: Extending the BNPL model into the physical world, capturing everyday spending with significant growth potential
          • Banking Integration: Leveraging “Affirm Edge” to embed lending within bank apps and seeking a bank charter (“Affirm Bank”) to fund loans with insured deposits rather than capital markets.

          Ultimately, Affirm aims to build a modern, untouchable consumer finance franchise: a two-sided payments network attached to a deposit-funded bank. With Levchin free to focus on long-term innovation and the business now generating its own cash, we see Affirm as a high-conviction candidate to eventually join the ranks of iconic, multi-generational financial institutions.

          While we are not recommending Affirm yet, we are keeping a close eye on it for a future Complete Investor issue.

          To read the full issue, click here.


          This Week In The Daily Journal…

          In Monday’s Daily Journal, Porter explored the capital-intensive business model of data-center builder CoreWeave (CRWV)… and says “it’s a zero.” Read the Journal here.

          In Tuesday’s Daily Journal, Tuttle Capital’s Matt Tuttle explained the architecture of the Porter & Company Porter Portfolio Index ETF… Read the Journal here.

          On Wednesday, Porter reported on the shipping tanker market, gushing more cash than ever before – and what you can do about it. To see that Journal, click here.

          Porter turned Thursday’s Daily Journal over to his friend Marin Katusa, who shared the latest news and opportunities in the world of gold and precious metals. Read Marin’s Journal essay here.

          In Friday’s Daily Journal, Porter revisits the Journal essay about his Bitcoin pricing model following the news that the leading cryptocurrency rose sharply this week. Read the Journal here.


          What’s Up Next Week…

          Marty Fridson will be releasing a new stock/bond combo recommendation this Saturday, September 12, at 10 am. We will send that full report to your inbox and include a summary in next week’s Weekly Monitor.


          Sponsored by Paradigm Press

          Rickards: “I didn’t think the government would go this far”

          In the last few weeks, the White House has done something I’ve haven’t seen in 50 years of working alongside government institutions.

          This is BIGGER than opening federal land… or eliminating mining regulations.

          This is the “final trigger” to unleash America’s 50X mining boom.

          Three small companies are now at the epicenter of a resource boom that could create more wealth than the San Francisco Gold Rush… and the Texas Oil Boom… COMBINED.

          My research shows they could dominate a $100 billion market within 12 months.

          I want to give you a shot to get in before this accelerates further.

          Watch my urgent briefing here.

          Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Paradigm Press is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.

          The post New Partner Benefit: Weekly Partner Monitor appeared first on Porter & Co..

          • ✇Porter & Co
          • The Age Of Discovery Porter &#38 · Co.
            Understanding Last Month’s Nobel-Worthy Breakthroughs Edit Delete Edit Delete This is Porter & Co. Biotechnology – where Porter Stansberry presents a revamped portfolio to capitalize on the next biotech bull market. The details of the recommendations – and the specific name of the companies and buy prices – are for paid-up subscribers only. To learn more about subscribing to Porter & Co. Biotechnology, click here. We’ve forgotten how hard it was to build modern hea
             

          The Age Of Discovery

          5 September 2026 at 07:00

          Understanding Last Month’s Nobel-Worthy Breakthroughs

          ⚙ Edit 🗑 Delete
          ⚙ Edit 🗑 Delete

          This is Porter & Co. Biotechnology – where Porter Stansberry presents a revamped portfolio to capitalize on the next biotech bull market. The details of the recommendations – and the specific name of the companies and buy prices – are for paid-up subscribers only. To learn more about subscribing to Porter & Co. Biotechnology, click here.


          We’ve forgotten how hard it was to build modern healthcare.

          In 1900, pneumonia, tuberculosis, and diarrheal diseases were the three leading causes of death in America. Staphylococcus aureus in the bloodstream killed 82% of the people who got it and most of them were young and healthy. Even as late as 1935, maternal mortality was still 600 per 10,000 live births.

          Then, penicillin emerged – as an accident. A mold spore drifted onto a culture plate in Alexander Fleming’s London laboratory in 1928. It killed the bacteria growing there. And, unbelievably, it was safe enough to be dosed into humans. Out of all the world’s innovations and technologies, only synthetic nitrogen fertilizer has enabled more human life than the discovery of antibiotics.

          By 1950, maternal mortality had fallen to 100 women per 10,000 live births. Today, it’s between 10 and 20.

          In 1900, 40% of the deaths from pneumonia were children under five. Today, only the very old and the very sick die from pneumonia. And, overall, less than 3% of all deaths in America are attributable to the leading causes of death in 1900.

          But these innovations were not easy.

          Modern drug discovery began at Rutgers University in the late 1930s. Professor Selman Waksman (pictured right, below) set out to discover new antibiotics with a systematic approach. His method was witchcraft crude by today’s standards. He dug up soil samples, cultured whatever was growing in it, and then painstakingly tested every culture against live bacteria, until something worked. It was like a blind man searching for a needle in 10,000 haystacks.

          But it was foolproof. A student streaked a soil microbe in a line down the middle of a plate. Then he streaked a disease bacterium across that line at a right angle. If the microbes in the soil were producing something effective at killing bacteria, it left a clear band through the bacterial streak. About 1,000 of Waksman’s 10,000 soil cultures produced a clear band. But that didn’t mean he discovered 1,000 new antibiotics. This was only the first hurdle.

          Nearly every antibiotic he discovered came out of actinomycetes: the thread-like soil bacteria that produce the smell of fresh-turned dirt. One actinomycete in 10 makes the same compound, streptothricin. Waksman isolated it, tested it, and discovered it was toxic.

          And then there was another problem: many of the compounds he discovered killed the wrong type of bacteria. As you probably know, bacteria come in two forms: gram-positive and gram-negative. Gram-positive bacteria have a thick cell wall that’s “naked.” Gram-negative bacteria have a thin cell wall that’s protected by a membrane.

          Penicillin works by jamming the enzyme that builds the cell wall, which causes the cell to burst as it grows. Against bacteria with a thick bare wall (gram-positive) the drug is devastating. But against a gram-negative bacterium, it never reaches the wall at all: the outer membrane protects it. Plague, cholera, and typhoid are gram-negative – penicillin did nothing to them. What Waksman needed was a compound that could kill what penicillin couldn’t. He needed to find a compound that could destroy gram-negative bacteria.

          And then there was a final problem. Some of the gram-negative killing compounds could not be manufactured. Producing an antibiotic in quantity means growing the microbe in thousands of gallons of liquid inside a steel tank. Plenty of microbes that secrete freely across a solid plate will not secrete anything once they are submerged.

          Out of 10,000 cultures, roughly 100 survived all of these challenges. Then they all had to be isolated. That meant separating the one active molecule out of the soup the microbe grew in, purifying it, and then making enough of it to inject into an animal. That took the sorting from 100 down to only 10.

          Then the animals they were testing these new antibiotics on kept dying. In 1940, actinomycin, the first antibiotic the program found, was the most powerful anyone had ever measured. But just one milligram of it killed a full-grown chicken. Streptothricin passed its early animal tests and then destroyed kidneys weeks after the dose. Clavacin and fumigacin failed the same way.

          Waksman discovered that, relatively speaking, killing bacteria wasn’t that hard. Killing bacteria at a dose the patient can survive was vastly harder. But finally, one of Waksman’s researchers found one.

          Albert Schatz, a 23-year-old graduate student working alone in the basement at Rutgers, isolated streptomycin on the afternoon of October 19, 1943. It cured tuberculosis, a deadly disease that had killed millions. The discovery won Waksman the Nobel Prize in 1952.

          Diminishing Returns On Drug Research

          Over the following decade, researchers in his laboratory worked through more than 100,000 more cultures. But instead of improving with time, his lab discovered fewer new compounds, even as it spent more money on discovery. Economists call the problem Eroom’s Law, which is Moore’s Law spelled backward. Just as Moore’s Law held that computer chip speed doubled every two years, Eroom’s Law holds that the number of new drugs approved per billion dollars of research spending has been cut in half roughly every nine years since 1950. In the early 1950s, an inflation-adjusted billion dollars of research bought 40 to 50 approved medicines. By 2018, that same billion bought 0.7.

          Today, the Tufts Center For The Study Of Drug Development puts the all-in cost of one approved drug at $2.6 billion. Where does all the money go? It goes toward the overwhelming percentage of drugs that fail.

          That’s why the drug business has always been organized around diversifying the risks as much as possible. But that’s finally changing.

          In much the same way that technology converted the oil-and-gas industry from a discovery challenge to an engineering challenge, with enormous horizontal wells, technology is changing the essential challenge of medicine from discovery to manufacturing.

          For a century, the oil business ran on the same odds as when Waksman’s antibiotics were discovered. Until the late 1970s, the industry considered a 10% wildcat success rate attractive: one successful well for every nine dry holes. The American Association of Petroleum Geologists tracked it by decade. New-field wildcat success ran 11.3% from 1946 to 1955, 10.8% from 1956 to 1965, and 11.2% from 1966 to 1975.

          Thirty years, and no improvement at all.

          Then, the industry discovered three-dimensional seismic surveying. This technology bounces sound waves off rock layers and reconstructs the subsurface inside a computer. It first emerged in the 1980s and became standard practice by the 1990s. Amoco measured the difference. Between 1990 and 1996, wells drilled with 3D seismic hit 49% of the time, against 14% for wells drilled without it. Over those same years, the share of Amoco’s prospects covered by 3D rose from 1% to 65%, and its cost of finding a barrel of oil fell dramatically – from $8 to less than $1.

          And what came next made it virtually impossible to drill a dry hole.

          Texas real estate developer George Mitchell spent 17 years and roughly a quarter of a billion dollars drilling the Barnett Shale in North Texas without turning a profit. In 1997, one of his engineers, Nick Steinsberger, replaced the expensive gel in the well’s fracturing fluid with water slickened by a trace of chemicals. The following year that well, S.H. Griffin No. 3, out-produced every well the company had ever drilled.

          Mitchell did not discover where the gas was. Everybody already knew where the shale was: it covered thousands of square miles. What Mitchell proved was, with the right chemistry, gas could be manufactured out of that rock.

          That’s what I mean when I say that drilling stopped being exploration and became engineering. Today the challenge isn’t finding oil and gas. Development wells in proven shale succeed 85% to 95% of the time. Today the challenge is purely engineering: how efficiently can you drill a given area of shale?

          In 2010, the horizontal section of the average new Permian Basin well ran 3,870 feet. By 2025, it ran 10,867 feet and 15% of new wells now stretch past three miles. Occidental Petroleum (OXY) cut its drilling time in the Wolfcamp shale (within the Permian in West Texas) from 43 days per well in 2014 to 26 days in 2015, and the best operators now drill these wells in 13 days. Output per Permian rig went from 130 barrels a day in 2014 to 800 barrels a day by 2019.

          Nobody found more oil. They engineered more oil.

          Drug discovery is making that same turn right now. Artificial intelligence (“AI”) will play a growing role in testing new drug targets. Much like 3D seismic, AI will dramatically reduce the cost of discovery. The key to success in the drug business will be engineering – figuring out more efficient, more effective, and cheaper ways of hitting the best targets.

          Our portfolio will be built around who owns the best engineering.

          Chronicling The Remarkable Breakthroughs

          As you know, our strategy in Porter & Co. Biotechnology is always to follow the science.

          In the month of August, there were two Nobel Prize-worthy technological breakthroughs that I’d like to share with you.

          ⚙ Edit 🗑 Delete

          Porter further expands on the portfolio that he developed last month – with two of his newest recommendations up more than 30%. To see the remainder of this issue, new recommendations, and full access to the Porter & Co. Biotechnology portfolio, click here.

          The most important breakthrough was on August 19. Merck (MRK) and Moderna (MRNA) announced a seminal breakthrough in the treatment of solid cancer tumors, the first successful Phase III trial of an individualized mRNA cancer vaccine. This new class of medicine holds the promise of stopping solid tumors from metastasizing following surgical removal.

          Six days earlier, the New England Journal of Medicine published the details of a successful application of gene editing, in which a single infusion permanently rewrote the genetic code of human liver cells. The result dropped patient LDL levels by 62%, permanently.

          The point made by highlighting these discoveries – which you’ll see me driving home in Biotechnology – is that we are living through a period of profound medical innovation. We’re getting closer to delivering cures at the cellular level by simply rewriting DNA – stopping disease before it can even begin.

          And today, no one in the world understands the engineering behind drug discovery and optimization better than Eli Lilly (NYSE: LLY).

          Yes, I know that’s a major pharmaceutical company. But we follow the science. Here’s what I mean.

          The successful gene-editing program that I described above, the one that permanently reduced LDL in patients, is owned by Verve Therapeutics. Harvard cardiologist and human geneticist Skar Kathiresan founded Verve because his brother died of a heart attack at 42. Kathiresan founded the company to stop treating heart disease as a chronic condition by installing the natural protective mutations that nature already gives some people. In other words, rewrite the code of life inside your cells to give you nature’s best protection from heart disease. Obviously, the potential value of this technology is enormous, and it could have many applications beyond cardiology.

          Verve’s initial funding came from Alphabet (GOOG) in May 2019. It went public in June 2021, during the massive post-COVID tech stock boom. On its first day, it gained 68%.

          The company has three main programs. The breakthrough program that just published its results is VERVE-102, which is targeting PCSK9 for LDL cholesterol. It has Food And Drug Administration (“FDA”) Fast Track designation and is very promising.

          The company’s next program is called VERVE-201. It’s targeting another gene in the liver (ANGPTL3) that makes a protein whose job is to put the brakes on fat clearance. It inhibits two enzymes (lipoprotein lipase and endothelial lipase) that pull triglycerides and cholesterol out of the bloodstream. Silence that gene, the brakes come off, and blood fats clear faster. It is unusual in that it moves all three lipid measures (LDL, triglycerides, and HDL).

          Again, the company knew to target this particular gene because people who naturally have one broken copy of ANGPTL3 have 17% lower triglycerides, 12% lower LDL, and 34% lower odds of coronary artery disease. People with two broken copies of this gene have a recessive condition called familial combined hypolipidemia – very low triglycerides, LDL, and HDL – and they are healthy. Losing this gene entirely costs you nothing but gives you much better cardio health.

          And then there’s VERVE-301, which targets lipoprotein(a) – Lp(a) – which I wrote about last month. This is the largest potential target in all of cardiology.

          So what does this have to do with Eli Lilly? Lilly is the best in the world at finding the best targets and building the best therapeutics. In June 2023, Lilly signed a global research collaboration with Verve on its pre-clinical Lp(a) gene-editing program, paying $60 million upfront. After the results of VERVE-102 (targeting PCSK9) were first published last spring, Lilly bought Verve Therapeutics for $1 billion. That was $10.50 per share, which was less than the initial public offering (“IPO”) price and about 86% below the stock’s all-time closing high of $73.99 (set September 10, 2021).

          Ruth Gimeno, Lilly’s group vice president for diabetes and metabolic research and development, described the deal as a chance to “shift the treatment paradigm for cardiovascular disease from chronic care to one-and-done treatment.”

          This is more than just another modality. This is the difference between a treatment and a cure, and it could profoundly reshape the entire drug industry. I’ve told you that I believe gene silencing will be the best-performing modality over the next 20 years. But what if there aren’t any genes to silence because they’ve all been edited away?

          Here are three points about that…

          1. Gene silencing will be used for a long time because changing your DNA permanently carries a lot of unknowns, and it may be irreversible. An edited genome has no off switch and no antidote. There will be a lot of people who are more comfortable taking a therapy once or twice a year – knowing that if something changes, they can always change therapies.
          2. Dosing has value too. A physician titrates silencing: more drug suppresses more protein, less drug suppresses less, and the dose can be adjusted as the patient changes. An edit delivers whatever suppression the editing efficiency achieved, forever. Where the safe range is narrow, or where medicine wants to reduce a protein rather than eliminate it, the adjustable drug wins.
          3. And then there’s the financial question. Insurers know how to pay for a twice-yearly injection, because they pay for thousands of chronic drugs that way. A one-time cure demands a single enormous payment with no established mechanism for spreading that cost across the decades of benefit it delivers. That is precisely why gene therapy has been such a commercial disappointment so far. BioMarin Pharmaceutical (BMRN) pulled a hemophilia gene therapy off the market entirely, despite the drug working because nobody would pay for it.

          And regulators discriminate too. An irreversible intervention requires longer follow-up, mandatory patient registries, and restrictions confining early use to the sickest patients. For a 45-year-old managing a chronic condition, the reversible drug clears approval faster and reaches the prescription pad sooner.

          Cholesterol treatment already works exactly this way. Statins come as daily pills. Antibodies against PCSK9 are injected twice monthly. Alnylam Pharmaceuticals (Nasdaq: ALNY) and Novartis’ (NYSE: NVS) Inclisiran (Leqvio) silences PCSK9 twice a year. And Verve’s gene-editing technology can rewrite it away once. Four technologies, one disease, and the market will determine who gets these drugs by how sick the patient is, how old, how reliably they take medication, and who is paying.

          In other words, I don’t think gene editing is as big a risk to gene silencing as gene silencing is a risk to other modalities. I believe, going forward, more disease is going to be treated at the cellular level by silencing genes or editing them.

          There’s no question that Lilly will be a leader in this field. And yes, I know its shares trade for more than $1,000 and the company’s enterprise value is more than $1 trillion. But that’s cheap compared to what the company will earn over the next decade.

          Specifically, today you’re paying 25.5x what analysts expect Lilly to earn next year. Consensus estimates put earnings at $36.39 per share this year and $46.62 next year, on revenue climbing from $88.3 billion to $101.8 billion. And I believe revenue growth will far surpass these estimates.

          The reason isn’t gene editing. Or even the company’s weight loss shots. The reason is a pill that’s going to transform human health.

          Eli Lilly Is Medicine’s Nvidia

          Novo Nordisk’s (NVO) Ozempic and Wegovy and Lilly’s Mounjaro and Zepbound are the current best-selling weight-loss shots. These therapies are peptides: a short chain of amino acids. Chemists build them the way a jeweler strings a necklace together. They anchor the first amino acid to a plastic bead, couple the second amino acid onto it, chemically unmask the new end so a third can attach, wash the bead in solvent, and repeat.

          Tirzepatide, the molecule inside Mounjaro and Zepbound, runs 39 amino acids long. Every link demands its own coupling, unmasking, and washing cycle. Then there’s a purification process, which pushes dilute liquid through columns the size of oil drums for days. It’s a chemical engineering marvel. It is also expensive.

          But orforglipron, Eli Lilly’s weight-loss pill, isn’t a peptide. It’s a small molecule.

          Chemists make this drug the way they make aspirin or the cholesterol drug Lipitor: a handful of reactions, solid crystals you can filter and weigh at each stage, and purification by crystallization instead of chromatography. Thus, small molecule drugs are vastly cheaper to make than peptide chains.

          The industry measures what a process costs to run using process mass intensity (“PMI”). Weigh everything you feed into the manufacturing line, the reagents, solvents, water, all of it, and divide by the weight of finished drug that comes out the other end. PMI captures manufacturing cost better than any other single number because solvent purchase and solvent disposal, not raw ingredients, dominate the bill. The American Chemical Society’s Green Chemistry Institute collected real production data from 14 pharmaceutical companies across 40 peptide manufacturing processes. Peptides consume 13,063 kilograms of input for every kilogram of drug delivered. Small molecules consume roughly 200.

          Solvent accounts for roughly 44% of that mass. It’s expensive and frequently toxic. One solvent, dimethylformamide, generates 39% of all the waste. European regulators classified dimethylformamide as a Substance of Very High Concern and restricted it in December 2021 over reproductive toxicity. Piperidine, the reagent that unmasks each link on a peptide chain, sits on the Drug Enforcement Administration’s controlled-chemical list. Peptide plants have enormous compliance costs.

          Over time, chemical engineers can drive costs out of small-molecule production. That’s why generic pills cost pennies. But peptide manufacturing shows no such expense-curve improvement between early development and commercial scale. It doesn’t get easier to make at scale.

          The weight-loss market won’t be won by finding a better target. Incretins (GLP-1s) are incredibly safe and effective. The weight-loss market will be won by producing and marketing enormous quantities of these drugs at vastly lower costs. Much like a shale field, this market is not about discovery. It is an engineering battle. And Lilly has won.

          I predict that Eli Lilly’s pill won’t just garner a lot of the market. I expect it will garner virtually all the market, better than 90% share over the next decade, for one simple reason: it’s vastly cheaper to produce and to distribute.

          But wait a minute, Porter, wasn’t Novo Nordisk first to market with a GLP-1 pill?

          Yes, Novo got there first. But it did it by manufacturing its peptide into a pill. That isn’t easy to do. It’s also very expensive because, in pill form, it requires vastly more of the GLP-1 peptide, semaglutide. And that’s an important point.

          Bioavailability measures the fraction of a swallowed dose that survives the stomach and intestine and arrives in the bloodstream intact. Stomach acid and digestive enzymes exist specifically to dismantle proteins into their component amino acids, and a peptide is a small protein. Thus, your stomach treats oral semaglutide as lunch.

          The FDA measured oral semaglutide’s bioavailability two separate ways during its review and got 0.471% and 0.795%. Swallow 1,000 units of oral semaglutide, and only five to eight of them reach your bloodstream, while the gut destroys or expels the other 992. In other words, Novo’s pill is an extremely inefficient delivery vehicle.

          Novo tried to engineer a solution. Every tablet of Rybelsus, Novo’s original semaglutide pill, carries 300 milligrams of an absorption enhancer called salcaprozate sodium, which raises the pH immediately around the tablet so the peptide slips across the stomach lining before enzymes reach it. But there’s a problem: absorption still collapses under ordinary conditions. In the food-effect study Novo filed with the FDA, 14 of 26 subjects who swallowed the tablet after a meal showed no measurable semaglutide in their blood at all. None. The label therefore instructs patients to dose on an empty stomach, with no more than 120 milliliters of plain water, and to eat, drink, or take nothing else for at least 30 minutes.

          Good luck in the real world.

          Injected Wegovy delivers 2.4 milligrams once weekly, which is about 10.3 milligrams of semaglutide per patient per month. The approved Wegovy pill delivers 25 milligrams every day. Call it 750 milligrams a month. Switch a patient from the Wegovy injection to the Wegovy pill, and that patient consumes 73x more semaglutide than they did on the shot, whether any of it reaches their bloodstream or not. Every additional milligram must come out of the same peptide plants that took Novo five years and $10 billion a year to build. Now think about trying to serve a billion people that pill every day. That’s not going to scale.

          Researchers priced generic semaglutide across formulations using 33 active ingredients. A year of the injection can be produced for well under $150, and most of that isn’t the drug at all: it’s the disposable injector pen. A year of the 14-milligram pill costs about $360 to produce. And Novo’s weight-loss pill isn’t 14 milligrams. It’s 25 milligrams. Our estimate is that Novo’s pill costs the company 4x to 5x as much as its injection costs to make.

          Now, perhaps some people would pay more for a pill – but not many. And especially not when there’s a pill that’s cheaper and vastly more effective in real-world dosing.

          Lilly’s orforglipron, approved April 1 and sold as Foundayo, is a small molecule that delivers 30% to 40% of a swallowed dose into the bloodstream. It needs no absorption enhancer and imposes no food restriction. It absorbs 40x to 100x more efficiently than oral semaglutide, and it belongs to a chemical family that costs one-50th as much to produce.

          The cost of making enough semaglutide to enable pill production shows up in Novo’s financial statements. Novo’s gross profit margin fell from 84.9% in Q2 of 2024 to 78.2% in Q2 of 2026. Its capital spending has climbed from 6 billion kroner in 2021 to 60 billion kroner in 2025 (or US$935 million rising to US$9.4 billion), a 10-fold increase in four years. Novo also paid $16.5 billion in cash to buy the contract manufacturer Catalent (formerly CTLT) outright, purely to get its hands on more pen-filling capacity.

          You can see how Novo is dealing with the threat from Lilly’s superior chemistry by watching Novo’s mergers-and-acquisitions activity. In May 2025, Novo Nordisk agreed to pay Septerna (SEPN) more than $200 million up front as part of a $2.2 billion deal for access to a platform that discovers small molecules acting on the same receptors Novo’s drugs target. Novo funds all the research. In February, it committed up to $2.1 billion to Vivtex, an MIT spinout, for a robotic screening system that tests thousands of formulations a day looking for ones that let a peptide survive the gut.

          The battle isn’t about discovery anymore. The battle is engineering. When Lilly begins to compete on price, how will Novo recoup the cost of these massive investments? My bet: it won’t.

          Lilly told investors a year ago that it expected to launch Foundayo worldwide without supply constraints. No peptide manufacturer can make that promise. Novo spent 2022 through 2024 rationing semaglutide, restricting starter doses and warning patients of shortages, because it could not make the peptide fast enough. Lilly, meanwhile, manufactured its pill before the FDA had even approved it. Its 2025 annual report disclosed $1.5 billion of pre-launch inventory sitting on the balance sheet as of December 31. Billions of tablets, ready to be sold.

          Foundayo launched on April 1 at $149 a month for the starting dose through Lilly’s own pharmacy, rising to $349 per month at the maintenance dose. Patients with commercial insurance pay as little as $25 a month. Eligible Medicare patients pay $50 a month beginning July 1. Novo is competing with a list price near $1,349 for its semaglutide pill. Who is going to buy it?

          Lilly launched Foundayo in Britain on August 23. Private providers there sell it at £100 to £120 a month ($136 to $163). Mounjaro, Lilly’s own injection, lists at £133 a month for the starting dose and £330 for the highest. So Lilly priced its pill below the cheapest injection it sells.

          Lilly has filed orforglipron for approval in more than 40 countries. It filed with China’s National Medical Products Administration at the end of 2025, for both obesity and type 2 diabetes. In March, it committed another $3 billion over 10 years, adding tablet production in Beijing and expanding injection capacity at the plant it has run in Suzhou since 1996. That takes Lilly’s total investment in China to nearly $6 billion.

          In total, Lilly has committed more than $50 billion to manufacturing since 2020. It’s building a $6.5 billion chemical plant in Houston to keep ramping Foundayo. It’s building a $3.5 billion injectables factory in Lehigh Valley, Pennsylvania, for its forthcoming new peptide, retatrutide. The plant won’t open until 2031 – so clearly Lilly believes there’s a vast amount of future demand for metabolic health products. And I believe they’re right.

          Apple (AAPL) has shipped 2.64 billion iPhones as of March 31, 2026. Cumulative iPhone revenue since 2007 runs well past $2 trillion. The iPhone is, by far, the best-selling consumer product of all time. But I believe Lilly’s portfolio of metabolic health products will surpass Apple’s iPhone revenue. Do other analysts see this kind of potential? Morgan Stanley puts the combined diabetes and obesity market at $190 billion a year by 2035.

          And with its next drug (retatrutide), Lilly will show the world what’s truly possible with this class of drugs.

          Lilly’s current GLP-1 product, tirzepatide, activates two gut-hormone receptors. GLP-1 tells the pancreas to release insulin after a meal, slows how quickly the stomach empties, and signals the brain that eating can stop.

          GIP is the second receptor, and it is the reason Lilly’s shot outperforms Novo’s. GIP stands for glucose-dependent insulinotropic polypeptide. Like GLP-1, it is a hormone your gut releases within minutes of food arriving, and like GLP-1, it tells the pancreas to make insulin. But GIP is different from GLP-1 in two critical ways. First, it acts directly on fat tissue, improving how efficiently fat cells absorb and store energy instead of leaving that energy to circulate in the blood. Second, and commercially more important, GIP appears to raise the threshold at which the brain triggers nausea. That means a drug hitting both receptors can be pushed to a higher dose before patients quit. Most of tirzepatide’s advantage over semaglutide comes from that headroom.

          Hitting both receptors produced $9.9 billion of Mounjaro sales and $4.9 billion of Zepbound sales in Q2 of this year alone. The molecule’s composition-of-matter patent, the patent covering the substance itself and the hardest kind to work around, runs in the United States until January 5, 2036. But long before this patent expires, Lilly will have innovated much better drugs. And sold billions of pills.

          The next innovation is retatrutide, which is a GLP-1 peptide that adds a third receptor. Glucagon is insulin’s mirror image. When your blood sugar falls, the pancreas releases glucagon, and the liver answers by breaking down stored glycogen and pushing glucose back into the blood. Adding a glucagon receptor to a weight-loss drug sounds backwards, since you are deliberately stimulating the hormone that raises blood sugar. What you buy is energy expenditure. Glucagon signaling raises the rate at which the liver burns fat and lifts resting metabolic rate.

          So tirzepatide works the intake side of the equation: it reduces how much a patient eats and improves how well the body handles what does get eaten. Retatrutide adds the output side. The patient eats less and burns more. Lilly expects to file for approval in Q1 2027. Retatrutide gives Lilly an edge that many customers will pay up to receive.

          Meanwhile, today Eli Lilly trades at 28x next year’s consensus earnings, which is only a small premium to the market.

          Action to Take: Buy Eli Lilly (NYSE: LLY) below $1,500 per share

          As with our other major pharma recommendation – Novartis (NYSE: NVS) – we recommend using an 80/20 allocation on this position, where you invest 80% of your capital into the equity and 20% of your capital into a long-dated call option with a strike price that is between 5% and 10% “out of the money.”

          Moderna’s New Personalized Cancer Vaccine

          In 1891, a New York surgeon named William Coley began injecting live streptococcal bacteria directly into tumors he could not cut out. He had noticed that patients who developed raging post-surgical infections sometimes watched their cancers shrink. He treated more than 1,000 patients and documented cures above 10% in cancers that otherwise killed everyone. Parke-Davis, later absorbed into Pfizer (PFE), sold a version of his toxin from 1899 until 1951.

          The logic never changed: the immune system can kill cancer, and it will do so if you show it the right target.

          Researchers identified the first usable molecular target on tumor cells in 1991. Dozens of companies then spent 20 years and billions of dollars building vaccines against targets like it. Nearly all of them failed for the same reason. Those targets were the patient’s own proteins, present at low levels in healthy tissue and merely overproduced by the tumor. Your immune system spends enormous effort learning not to attack your own proteins, because attacking them causes autoimmune disease. Training it to break that rule means overriding a safety system, and the safety system usually wins.

          Subscribers who followed my work in the mid-2000s will remember Antigenics, which trades today as Agenus (AGEN). Antigenics manufactured a vaccine called Oncophage individually from each patient’s own surgically removed tumor. Genuine personalized medicine, 20 years too early. Its Phase III trial in kidney cancer randomized 818 patients. The hazard ratio for recurrence came in at 0.923, with a confidence interval running from 0.729 to 1.169 and a p-value of 0.506.

          (Editor’s note: There are three critical numbers to know from any clinical trial. First, the hazard ratio compares how fast bad events happen in the treated group against how fast they happen in the control group. Read it like this: 1.0 means both groups suffered at identical rates and the drug did nothing at all. A 0.51 hazard ratio means the treated patients relapsed at roughly half the rate. Lower is better. A confidence interval brackets the range the true answer probably falls inside, given how few events the trial actually observed. If that range crosses 1.0, the drug might have done nothing, and the headline number could be noise. The p-value estimates the odds of seeing a result that large by pure chance if the drug were inert. Regulators generally want it below 0.05.)


          The point estimate suggested 8% fewer recurrences. The confidence interval crossed 1.0 in both directions, meaning the vaccine might have helped by 27% or harmed by 17%. The p-value said a coin flip explains the whole result. Antigenics collapsed, renamed itself Agenus in January 2011, and built a business around the adjuvant Antigenics used to provoke an immune response (QS-21).

          Dendreon (formerly DNDN) came next. Its personalized cancer vaccine, Provenge, was grown from each patient’s own immune cells. It won its Phase III trial, extending survival in prostate cancer by 4.1 months at a hazard ratio of 0.78. The FDA approved it in 2010. It showed no effect whatsoever on how fast the cancer progressed.

          Then Dendreon priced it at $93,000 a course and… no one bought it. The company filed for bankruptcy in November 2014, and on May 6, 2015, the European Commission withdrew Provenge’s marketing authorization across the entire European Union. Not for safety. Not for efficacy. Dendreon requested the withdrawal itself, because it could not get European payers to reimburse for the drug.

          In 2007, Genitope ran 287 patients through a lymphoma vaccine trial and delivered 19 months of progression-free survival versus 23 months on control. Worse than nothing. The stock halved the day the results came out. It delisted it nine months later.

          After all these failures, most people assumed that personalized cancer vaccines would never work. But then three things changed.

          First, the targets changed. Instead of vaccinating against the patient’s own normal proteins, laboratories now sequence the tumor’s DNA alongside the patient’s healthy DNA, subtract one from the other, and isolate the mutations that exist only inside the cancer. Those mutated proteins are genuinely foreign. These proteins are called neoantigens.

          Second, checkpoint inhibitors arrived. Tumors survive by displaying molecular signals that switch off immune cells as they approach. Checkpoint inhibitors like Merck’s Keytruda block those signals. The old vaccines were pushing immune responses into a system the tumor could turn off at will, which is precisely why they generated beautiful laboratory data but didn’t save patients. Now that switch gets disabled.

          Third, as we’ll be discussing for years, the engineering has gotten much better. mRNA (messenger RNA) solved the delivery problem: it carries the instructions directly into a cell, so the patient can make precisely the right antibodies. Encode dozens of neoantigens and the patient’s own body will manufacture all of them. Moderna’s product encodes up to 34 antigens, matched to that individual’s specific cancer. Production time fell from 50 or 60 days to about six weeks.

          The individualized product cut recurrence at a hazard ratio of 0.51, with a confidence interval of 0.294 to 0.887 and a p-value of 0.0075.

          In other words, the vaccine reduced cancer’s recurrence by about 50% – an outcome that was almost impossible by chance alone.

          While the intellectual property around these vaccines and their delivery systems is, of course, complicated (like all IP in biotechnology) Moderna’s durable advantage rests on two assets that offer a moat beyond patents.

          The first is the algorithm that picks which mutations go into the vaccine. In the largest published benchmark, ranking candidate neoantigens by how tightly they stick to the immune system’s display molecules identified genuinely useful targets less than 20% of the time. Filtering instead for whether the fragment actually appears on the cell surface, and whether a T-cell can recognize it, lifted accuracy above 70%. The clinical numbers are harsher still. Only 2% of computationally predicted neoantigens provoke a response in the laboratory. And in a pancreatic trial run by BioNTech SE (BNTX), only 11% of the selected targets produced a detectable immune response in patients.

          Moderna’s vaccine holds 34 slots. At an 11% hit rate, four of them are doing something; at 70%, 24 are. Moderna’s algorithm is producing a better vaccine. And that advantage widens with every patient Moderna treats and learns from.

          The second asset is Moderna’s factory. Every manufacturing batch treats exactly one patient. Moderna’s annual report states that the process scales out in parallel rather than up: you cannot build a bigger vessel and serve more people; you have to replicate the entire line. Moderna’s total dedicated capacity consists of one building: 140,000 square feet in Marlborough, Massachusetts. It cost around $400 million to build. Across the 10 solid tumors where this approach could work, American surgeons treat roughly 815,000 operable cases every year. Virtually every patient would want a personalized cancer vaccine, if having one meant a 50% better chance of extending cancer-free remission over a meaningful period (years). So, for now, it’s Moderna’s one building, against 815,000 American patients a year.

          Currently, Moderna has no close competitor at all. BioNTech runs the only comparable program at scale and expects no pancreatic results before 2031. Genentech, the Roche Holding AG (SWX: ROG) subsidiary, abandoned its cancer vaccine partnership with the Norwegian developer Nykode Therapeutics.

          Over the trailing 12 months through June 30, Moderna revenue was $2.23 billion and gross profit was $521 million, a gross margin of 23.4%. Research spending consumed $2.88 billion, 5.5x gross profit. The operating loss was $3.32 billion, or $7.99 a share. Moderna holds $6.91 billion of cash and investments with no reported debt, and it burns $1.24 billion a year, leaving 5.6 years of runway.

          Analysts expect Moderna to lose $4.93 a share next year on $2.40 billion of revenue. Consensus is modeling almost no cancer-vaccine revenue at all through the end of 2027. Strip out the cash, and the market is valuing this business at $51 billion.

          Moderna’s partner in this pivotal trial was Merck, which is seeking ways to extend the patent life of its best-selling checkpoint inhibitor, Keytruda. Merck books the sales and the two companies split the profits equally. Sell-side analysts put peak melanoma sales at $5.4 billion per year. Our base case assumes the vaccine reaches melanoma and lung cancer, which gets us to $11.4 billion in peak franchise revenue per year. Assuming 38% operating margin, that throws off $4.3 billion of profit per year. Moderna keeps half. As an estimate (we don’t know how long it will be before competitors emerge), we’ll use a 13-multiple on these earnings. That gets us to a future total value of $28 billion. But this market could easily grow much larger. Broad adoption across solid tumors at costs below $45,000 gets us to $92 billion.

          Discounting those future values back to today yields a potential present value of $11 billion to $36 billion. On a Moderna per-share basis, that’s $27.56 or $90.42. That’s a very wide range of potential value for an investor to estimate today – welcome to biotech investing! And it’s even more difficult in this case because this entire approach is new, is extremely expensive, and doesn’t scale easily.

          Manufacturing costs more than $100,000 per patient today. And this drug gets given to people whose cancer has already been cut out, who show no detectable disease anywhere in their bodies, and who feel completely fine. That’s a lot of money for an insurance company to approve… to someone who is currently healthy.

          Provenge worked. It won its trial, and the FDA approved it. Then it was pulled out of Europe entirely, because payers would not shell out $93,000 for a drug given to patients who were not visibly, terminally ill. Moderna and Merck are proposing a six-figure therapy for patients who, while at great risk for further disease, are not currently sick. Who will pay that much?

          One more thing. After Merck and Moderna announced that the trial met both of its endpoints, the market added $36 billion to Moderna’s value. That’s the present value of my most aggressive forecast for this product. I estimate that fair value on Moderna’s other business lines (an approved COVID vaccine, an approved RSV vaccine, a late-stage flu program) and its associated intellectual property is worth something around $15 per share. Add this to my estimates on the present value of the cancer vaccine, and you get something between $45 and $110. But the stock is trading above that – at $140 per share! Too expensive to recommend right now.

          I suspect we will see a major pullback in Moderna’s shares at some point as the difficult economic reality of a $100,000 cancer vaccine plays out.

          But what about Merck? Merck collects the other half of the vaccine profits; it sells the Keytruda that the vaccine must be given alongside, and it trades at only 16.1x what analysts expect it to earn in 2027. Keytruda generated 48.7% of Merck’s 2025 revenue. And Keytruda loses United States exclusivity in 2028. The stock has been trading very cheaply because of the risks Merck faces with the Keytruda patent cliff. I bought it personally earlier this year primarily because of its dividend and because it’s a very high-quality, low-volatility stock that fits with my “Honeycomb Strategy.” I didn’t buy it because of the cancer vaccine – in fact, before I took up this work in July, I didn’t know anything about Moderna’s cancer vaccine. But the shares jumped on that news and are now up 40% year-to-date. No, it’s not an expensive stock. But it’s not cheap anymore. I’m going to pass for now. If there’s a big drawdown, I’ll do a complete review of it.

          Portfolio Review And Actions

          Present value is our estimate of what a share is worth today on the evidence in hand. It’s not a price target, as we believe in letting our winners run. We don’t want to sell a great business when we have a good entry price. Buy below is the highest price at which we would put new money to work.

          Eli Lilly enters at our 14% cap for integrated and tollbooth businesses, sized by inverse volatility alongside Novartis (NVS). Moderna would enter under our 10% cap for companies with marketed products, once it trades below $110.

          Big Month Of News For uniQure

          uniQure (Nasdaq: QURE) is a Hold.

          Its AMT-130 is a gene therapy for Huntington’s disease. Huntington’s is caused by a single inherited defect that makes a mutant protein which slowly kills neurons in a part of the brain called the striatum. Patients lose motor control, then cognition, then everything, over 15 to 20 years. There is no treatment that changes the course of the disease.

          AMT-130 is delivered by a neurosurgeon, through the skull, guided by MRI, directly into the striatum, in a single procedure. A viral vector carries instructions that make neurons produce a small RNA that silences the mutant gene.

          Two things will happen this month. uniQure will present four-year data with a June 30 cutoff, covering 12 high-dose and 12 low-dose patients. The three-year data (previously published) is why the stock has tripled. On the primary measure – a composite score built from motor, cognitive, and functional tests – treated patients declined 0.38 points against 1.52 for an external control group, a 75% slowing, at p equal to 0.003. Functional capacity slowed 60% at p equal to 0.033. That is the most convincing result anyone has produced in Huntington’s disease.

          September’s presentation is evidence about durability, and we suspect it will report data that’s stronger than the three-year data. We also believe this drug will receive approval this year, despite the very small number of patients and the lack of a real control group.

          There’s a lot of history here. On November 3, 2025, FDA’s pre-submission feedback said it no longer agreed the Phase I/II data were adequate as primary evidence and the data were “currently unlikely” to support a filing. The shares fell from $67.49 to roughly $26. In June 2026, after a follow-up meeting, the agency reversed and agreed that the three-year analysis is acceptable as the primary basis for accelerated approval.

          Here’s the real problem: uniQure has no placebo arm. These trials compared treated patients against a matched set drawn from Enroll-HD, an observational registry, selected by a statistical technique that pairs patients on baseline characteristics.

          In February 2026, the FDA rejected a gene therapy for Hunter syndrome under similar circumstances: uncertainty in the eligibility criteria, comparability of the natural-history control, and the appropriateness of the biomarker. The agency noted that the control group was mismatched on age and baseline cognition.

          uniQure’s filing rests on the same architecture: a small, treated cohort against a matched external control.

          In addition, this division of the FDA has spent 2026 tightening the screws on gene therapy delivered to the brain. In January, it halted two REGENXBIO trials after a tumor appeared in an asymptomatic five-year-old dosed four years earlier, and the resected tumor showed viral genetic material integrated next to a cancer-causing gene called PLAG1. Causality was never established, and no other patient in either trial had a tumor. In August, the agency halted the same program again after spine imaging in five patients turned up small nodules, all judged benign. And in November 2025 the FDA put a boxed warning on Sarepta’s Duchenne gene therapy for fatal liver injury and pulled the indication for non-ambulatory patients.

          The FDA is very worried about using viral vectors for gene therapy… and it’s easy to understand why.

          But we think it’s likely that uniQure will get approval because there’s no other possible therapy and these results look strong. In 2023, the FDA granted accelerated approval to Qalsody for a form of ALS on the strength of a reduction in neurofilament light, a protein that leaks out of dying nerve cells, in 108 randomized patients. uniQure’s neurofilament data was 8.2% below baseline at three years on the high dose. We think there’s enough proof that the therapy is slowing the disease to warrant approval.

          And so, we’ll hold.

          Silence Therapeutics Closer To Divesiran Approval

          Silence Therapeutics (Nasdaq: SLN) remains a Speculative Buy with a raised buy price.

          Polycythemia vera is a blood cancer in which the bone marrow makes too many red cells, the blood thickens, and thick blood clots. The standard treatment has not fundamentally changed in a century: a nurse drains blood out of the patient, therapeutic phlebotomy. The body already has an off switch for making red blood cells. It’s a hormone called hepcidin that controls how much iron is available to the marrow. Iron is the raw material for red cells, so turning hepcidin up starves the marrow of what it needs and fewer red cells get made.

          There are two ways to raise hepcidin. You can inject synthetic hepcidin, or you can help the patient produce more of his own. Protagonist Therapeutics (PTGX) and Takeda Pharmaceutical (TAK) took the first route with a peptide called rusfertide, and on August 28 the FDA approved it as Mimrylo.

          Silence is taking the second approach. Divesiran is a small interfering RNA that silences a gene called TMPRSS6, whose protein is the brake on the body’s own hepcidin production. Release the brake, and the patient makes more of their own hepcidin.

          Until August 28, the case for divesiran rested on a theory: that raising hepcidin controls polycythemia vera. The FDA has now approved a drug that does exactly that, on the strength of a randomized Phase III trial in 293 patients. The mechanism is no longer a hypothesis but a labeled indication. Mimrylo won approval on a single endpoint: the share of patients who did not become eligible for phlebotomy between weeks 20 and 32. Eligibility was defined precisely, as a confirmed hematocrit at or above 45% that also ran at least three points above the patient’s own baseline, or a hematocrit at or above 48%. Silence now knows the endpoint, its exact definition, and the trial size it will require to gain approval.

          This new drug also begins to build the market for this kind of therapy. Somebody has to persuade hematologists to stop draining blood and start writing a prescription, and somebody has to get insurers to pay for it. Takeda has both the sales force and every incentive to do that work. Silence arrives after the category exists… but it will be second to market. What does that mean? Mimrylo is a once-weekly injection. Divesiran is one injection every twelve weeks. That’s fifty-two injections a year against four.

          Regarding efficacy, Silence’s Phase II produced 88% clinical responders against 19% on placebo, at p below 0.0001, in 48 phlebotomy-dependent patients. Mimrylo produced 76.9% responders against 32.9% on placebo.

          Silence sold $175 million of stock at $13.50 (right above our buy-up-to price) on the strength of the divesiran data.

          We are raising our buy-below price from $13 to $16 and our present value estimate to $22.

          Keeping A Watch On Arrowhead Pharmaceuticals

          Arrowhead Pharmaceuticals (Nasdaq: ARWR) remains on the watchlist..

          Plozasiran is a small interfering RNA (siRNA) that silences APOC3, a gene whose protein blocks the body from clearing fat out of the blood. Silence it, and triglycerides fall. It is injected under the skin once every three months. The FDA approved it on November 18, 2025, as REDEMPLO, for familial chylomicronemia syndrome, a genetic disorder affecting roughly 6,500 Americans. Arrowhead’s management has set the wholesale price at $45,000 per patient per year. In the June quarter, REDEMPLO produced about $2.4 million of revenue across more than 400 prescribers, roughly double the prior quarter.

          Expanding the label is the company’s strategy. Roughly 2.3 million American adults carry triglycerides above 500 milligrams/deciliter (“mg/dL”), based on two decades of federal health survey data. Arrowhead will file for that population before the end of this year. And, on August 30, at the European Society of Cardiology congress in Munich, the company presented the trial data to support the filing. SHASTA-3 and SHASTA-4 randomized 757 adults to four quarterly doses or placebo. Triglycerides fell 79% and 81% at 12 months, both at p below 0.0001, and 85% in patients who started above 880 mg/dL.

          Very high triglycerides cause acute pancreatitis, a sudden inflammation of the pancreas that hospitalizes patients and sometimes kills them. Pooled across both trials, pancreatitis events fell 78%, In patients who had already survived one attack, events fell 91%. Safety was clean: serious adverse events were 8.3% on drug against 10% on placebo, and 1.4% of patients discontinued against 0.8% on placebo.

          Arrowhead isn’t the first to market here. On June 24, the FDA approved Ionis Pharma’s olezarsen as Tryngolza for the same population. Arrowhead’s competitive answer is dosing and depth: olezarsen is a monthly autoinjector, and plozasiran is quarterly. Olezarsen cites a 66% triglyceride reduction against Arrowhead’s 79% to 81%, and an 85% pancreatitis reduction against Arrowhead’s 78%.

          Arrowhead carries roughly $1.22 billion of debt against $1.57 billion of cash and investments. The largest piece is a $400 million senior secured loan from Sixth Street. Interest runs at 15%, payable in kind rather than in cash, secured by a first lien on substantially all assets including the intellectual property itself. The company also has $700 million of zero-coupon convertible notes due January 2032 with a conversion price near $87.07.

          Our $85 present value is built in four steps. We start with Morgan Stanley’s $3.2 billion peak plozasiran estimate, which that firm doubled from $1.7 billion in April, and value it at three times peak sales. We add $2 billion for the partnered royalty streams on olpasiran with Amgen and fazirsiran with Takeda, plus the obesity programs. Then we add the cash and subtract the debt. At $81.38, you are paying 3.5x Morgan Stanley’s peak-sales estimate for the whole enterprise, on a drug that is second to market with an interest bill that compounds at 15%.

          We are keeping a watch on Arrowhead Pharmaceuticals until we see a price decline. We hope there’s a pullback in biotech this fall that allows us a good entry price.

          Halozyme: Adding Another Tollbooth

          Halozyme Therapeutics (Nasdaq: HALO) joins the recommended list with a Buy Below of $110, with a present value of $124.

          Most antibody drugs have to be dripped into a vein, which means the patient sits in an infusion chair for hours and the hospital bills for a nurse, a chair, and a bag. Halozyme owns an enzyme called rHuPH20 that temporarily loosens the mesh of tissue under the skin, so the same drug can be pushed in with a syringe in minutes. It licenses that enzyme to drug companies under the name ENHANZE and collects a royalty.

          Halozyme runs no trials, treats no patients, and files for no approvals. Roche Holding (SIX: ROG), Johnson & Johnson (JNJ), Takeda Pharmaceutical (TAK), Argenx (ARGX), and Bristol-Myers Squibb (BMY) do all of that. Halozyme cashes checks.

          In June, royalty revenue rose 50% to $307.7 million, of which $152.2 million came from DARZALEX, the subcutaneous myeloma drug Johnson & Johnson sells.

          Management raised full-year guidance for the second time this year, to $1.835 billion to $1.910 billion of revenue and non-GAAP earnings of $8.65 to $9.00 a share, up from $7.75 to $8.25. And it bought 4.8 million of its own shares in the quarter for $332.8 million, at an average price of $69.30, under a $1 billion authorization that runs through 2028.

          One U.S. patent covers the composition of rHuPH20, which is licensed in every ENHANZE agreement. And it expires on September 23, 2027. That’s why Goldman Sachs rates the stock a Sell with a $58 target. But the royalty steps down, it does not stop. Halozyme’s filings reveal that when the rHuPH20 patent expires in a country, the royalty rate is reduced rather than terminated, and the company says the reduction never exceeds 50%. Apply the worst case to the exposed share of the royalty base, and we get a hit of roughly $1.85 a share against consensus 2027 earnings of $10.31. Halozyme guides DARZALEX royalties as secure through 2032.

          And there is a second platform that is not in any existing license. MDASE is a separate family of modified hyaluronidases with 99 patents and applications, exclusive through 2032 outside the United States and 2034 inside it. Every new agreement Halozyme signs can be written on MDASE rather than ENHANZE. The company has signed five new agreements this year against a goal of three, including a global oncology collaboration with GSK (GSK) in May.

          And there’s a potential kicker – a big one. Halozyme sued Merck in April 2025, claiming that subcutaneous Keytruda infringes 15 MDASE patents. A German court granted a preliminary injunction against subcutaneous Keytruda in December 2025.

          If you’ve watched Veeva Systems (NYSE: VEEV) over the last month – up more than 40% – you’ll understand why I prefer to own biotech’s tollbooths.

          Action to Take: Buy Halozyme Therapeutics (Nasdaq: HALO) up to $110 per share

          BioNTech’s Failure

          On August 28, BioNTech SE (BNTX) terminated the Phase II trial of autogene cevumeran, its individualized mRNA cancer vaccine partnered with Genentech, the Roche Holding subsidiary. The shares fell 8%. We do not own BioNTech, but what happened in this failed trial is important.

          The independent Data Safety Monitoring Board found a numerical imbalance in overall survival between the two arms and concluded that continuing would not change the efficacy result. Reuters reported that analysts read that imbalance as more deaths in the vaccine group than in the control group.

          BioNTech enrolled patients with high-risk stage II or stage III colorectal cancer who had already had surgery, then three months of chemotherapy, and who still had circulating tumor DNA in the blood afterward. Circulating tumor DNA is what it sounds like: fragments of cancer genome floating in the bloodstream. Finding it after surgery means the surgeon did not get everything.

          But the vaccine was given as monotherapy, without a checkpoint inhibitor. Moderna’s product is given with Keytruda, Merck’s checkpoint inhibitor.

          Bicycle: You Are Being Paid To Own The Pipeline

          Bicycle Therapeutics (Nasdaq: BCYC) is our most uncomfortable Buy.

          Bicycle holds $510.1 million of cash against $96.3 million of total liabilities and no debt at all, leaving $413.7 million of net cash, or $5.96 a share. So you are paying $4.14 for $5.96 of cash, which puts the enterprise value at negative $127 million. The market is paying you $1.83 a share to buy the stock.

          Bicycle makes bicyclic peptides: short chains of amino acids chemically stapled into two rigid loops, which lets a very small molecule bind a target with the precision of an antibody and then clear the body in hours rather than weeks. Attach a chemotherapy payload, and you get a tumor-seeking missile that does not linger in healthy tissue. The lead drug, zelenectide pevedotin, targets a protein called Nectin-4 that sits on the surface of bladder-cancer cells.

          There is already a Nectin-4 drug, and it is a good one. Padcev, from Pfizer (PFE) and Astellas, produced a confirmed response rate of 67.7% with pembrolizumab in first-line advanced bladder cancer and did more than $1.9 billion of sales in 2025. Zelenectide’s confirmed response rate in the equivalent setting was 58% to 62% in 26 patients.

          Padcev’s label carries a boxed warning for severe and fatal skin reactions. Skin reactions occurred in 70% of patients on the combination, 17% at grade 3 or 4, with fatal bullous dermatitis in 0.2%. Peripheral nerve damage occurred in 67%, and 87% of those patients still had it at last evaluation. Zelenectide, at its selected dose, produced skin reactions in 17% and neuropathy in 33%, with no severe skin reactions at any grade.

          On March 17, regulators told Bicycle that its pivotal trial design would not support accelerated approval in metastatic bladder cancer. The company converted the trial to a randomized Phase II, cut 30% of its staff, and set out to reduce operating expenses by half.

          Its partners left. Genentech gave notice in July 2025, and Novartis followed later that year. Bayer terminated one target program in November 2025 and the entire agreement in July 2026, effective this month. Those three deals carried $45 million to $50 million of upfront money each and up to $1.7 billion of milestones apiece. Bicycle had collected $240.2 million of partner cash across its history and now has only one active collaboration, with Ionis.

          In short, the outlook looks dark. But that’s why the stock is cheap. And we believe the underlying technology holds a lot of promise. The drug is not dead, and neither is the differentiation. Bicycle is still running the randomized Phase II and expects data in the second half of this year. In the Phase I first-line study, in patients too sick for cisplatin, zelenectide plus pembrolizumab produced a 59% response rate and median progression-free survival of 13.0 months. In late-line monotherapy, 38% responded with a median duration of response of 10.0 months. Those are not failing numbers.

          Meanwhile, Bicycle is moving its resources to radioconjugates: the same targeting peptide carrying a radioactive isotope instead of a chemotherapy payload. It has locked up the hard part of that business, which is not the chemistry but the fuel. Bicycle signed a 15-year contract with the UK Nuclear Decommissioning Authority for access to up to 400 tonnes of reprocessed uranium, and it is working with the UK National Nuclear Laboratory to extract thorium-228 from it. It has exclusive lead-212 generators from SpectronRx and a supply agreement with Eckert & Ziegler. Novartis built a $2 billion drug in Pluvicto and an $816 million drug in Lutathera on this idea, and the constraint on the whole field is isotope supply. Bicycle’s first company-sponsored radioligand trial starts in 2027.

          Bicycle Therapeutics is a Speculative Buy, below $5.00, with a present value of $7.50.

          Good investing,

          F. Porter Stansberry
          Stevenson, Maryland

          For important disclosures and disclaimers, please visit our Legal Disclosures page.

          The post The Age Of Discovery appeared first on Porter & Co..

          • ✇Porter & Co
          • You Probably Don’t Own Bitcoin And That’s A HUGE Mistake Porter &#38 · Co.
            Issue#153, Volume#3Most Investors Still Don’t Understand Bitcoin – Here’s What They’re Missing Inside Today’s Issue Essay: You Probably Don’t Own Bitcoin And That’s A Huge Mistake Strong GDP Growth Job Growth = Rate Hike Diesel Rises Again Chart Of The Day… Morgan Stanley Bitcoin Trust (MSBT) Today’s Mailbag Editor’s note: The Porter & Co. editorial and Customer Care teams will be off on Monday because of Labor Day. We will all be back on Tuesday. Nobody invented money. It was not des
             

          You Probably Don’t Own Bitcoin And That’s A HUGE Mistake

          4 September 2026 at 14:00

          Issue#153, Volume#3

          Most Investors Still Don’t Understand Bitcoin – Here’s What They’re Missing


          Editor’s note: The Porter & Co. editorial and Customer Care teams will be off on Monday because of Labor Day. We will all be back on Tuesday.


          Nobody invented money.

          It was not designed, chartered, decreed, or granted. It was discovered, slowly, in trade. A man takes salt in exchange for his labor because he knows he can exchange it for other goods. Cattle, hides, shells, iron bars, bricks of tea, cakes of salt, strings of beads: each of these served as money at different times in history.

          Carl Menger, one of the founders of the Austrian School of economics, first theorized how money evolved through trade. Men were led, he wrote,

          each by his own economic interests, without convention, without legal compulsion, nay, even without any regard to the common interest, to exchange goods destined for exchange (their ‘wares’) for other goods equally destined for exchange, but more saleable.

          The most important takeaway is that money predates all government. Governments don’t create money – in fact, as you’ll see, governments constantly corrupt money.

          The second most important takeaway is that the market – through the choices of millions of individuals each pursuing their own economic interests – will always trend toward the best and most reliable form of money. That’s why, over time, more people favored metals, particularly gold and silver. And it’s why more and more people are choosing Bitcoin (BTC), today.

          And what did governments add to money? Fraud, of course.

          The denarius, the benchmark coin of the Roman Empire, was 90% silver (3.9 grams) under Julius Caesar. By AD 200, the coin was less than 60% pure, and by AD 300, it contained 5% silver. The Empire disintegrated alongside its money – something Americans would be wise to remember.

          The same thing has happened to every empire.

          Between 1544 and 1551, in a program historians call the Great Debasement, England’s silver coinage went from the old sterling standard of 92.5% fine to 75%, then 50%, then 33.33%, and finally to 25% in April 1551. Measured in metal, a pound sterling fell from 153.4 grams of pure silver to 25.9. Roughly 83% of the silver content was removed in only eight years.

          It happens, over and over again. As sure as the sun rises in the East, every government, if it gains enough power, will attempt to control money by creating a currency. And they will devalue that currency to steal. That’s exactly what’s been happening in America since 2010. It’s why people under the age of 40 can’t afford to buy a house, get married, or have a family. It is what’s driving the collapse of our culture and our society. It’s what’s leading more and more people into lives of desperation: gambling, prostitution, and substance abuse. It’s leading people to become politically radicalized. And, if it continues, it will lead America to socialism, a financial collapse, and even a civil war.

          But this doesn’t have to happen to you. You are still free to choose what you save. And you should save money, not the government’s currency. What is money? Money is what people voluntarily save. It is discovered, in markets, over long periods, by people making their own self-interested choices. Currency is what a government issues and debases and requires you to use as legal tender for debts and taxes. Money doesn’t require any coercion. It’s chosen freely, in the market.

          Unless you understand this background, Bitcoin will never make sense to you.

          Beyond this basic distinction between money and currency, the other misunderstanding that’s common even among people like financial commentators Peter Schiff and Jim Grant, who have an Austrian orientation, is that because Bitcoin is inert – it’s just code – it doesn’t have any intrinsic value.

          As the Austrians proved, value is relative. And, in the modern world, code can have enormous value. Look at Microsoft (MSFT). What is it, other than code?

          Every technology that Bitcoin has combined into its code has tremendous real-world value. Public-key cryptography verifies bank wires, military traffic, software distribution, and every other encrypted commercial transaction. Cryptographic hash functions compress huge files into a short fingerprint, which is how password databases and software integrity have been protected for decades. Distributed consensus protocols (blockchains) keep databases organized for mission-critical infrastructure around the world.

          Saying that these things have no value because they are only code is profoundly ignorant.

          Bitcoin combined these technologies to create something extraordinary: a way to send a fixed amount of value (a proof of work) to anyone around the world using only the public internet. Bitcoin allows two strangers, who do not trust each other, to exchange a form of money, with final settlement, without asking a bank, a clearinghouse, a corporation, or a government for permission. It also allows individuals to save an unlimited amount of money using only their minds: a seed phrase.

          Gold’s weakness is its physical presence. It requires custody. To use gold, people ultimately must hand it to someone: a bank, a treasury, a depository institution. Or else… they risk having it seized (see 1933) or stolen. Bitcoin removes this risk. And that is a revolutionary monetary characteristic. Over time, I believe this will transform the relationship between people and governments. It creates a defense against debasement and coercion.

          How To Value Bitcoin

          Like gold, Bitcoin is inert. It has no earnings. It pays no coupons. And, like gold, its supply only grows slowly, and the costs to mine Bitcoin continue to increase. To value Bitcoin, you must understand the other side of the scale: the currency you’re measuring it against. Bitcoin’s price, like gold’s, is driven by monetary aggregates.

          The Porter & Co. Bitcoin Liquidity Model uses least squares regression analysis, which is a statistical method for understanding the historical relationship between global currencies and Bitcoin, using about 500 weekly observations beginning in January 2015.

          The monetary aggregates we use include:

          • Federal Reserve net liquidity, which is the Fed’s balance sheet minus the Treasury’s cash account minus money parked in the reverse repo facility. It is what the Fed is actually leaving in the banking system.
          • Global M2 in dollars. M2 is broad money: currency, checking accounts, savings deposits and close equivalents. We sum the United States, the euro area, Japan, China and the United Kingdom, converted to dollars.
          • Total circulating supply of the two large dollar stablecoins, USDT (Tether) and USDC (Circle Internet).

          Statistics show our model explains 89% of the variation in Bitcoin’s price. Most Bitcoin enthusiasts claim Bitcoin’s price is driven by its halving cycle. But it isn’t. Once global liquidity is measured properly, the four-year halving cycle adds nothing to Bitcoin’s price. Bitcoin’s code was designed to keep the price of Bitcoin stable against the growth in compute. It’s working. What’s driving its price higher is debasement by governments.

          On May 21, I posted this on X.com (@porterstansb):

          I expect Bitcoin will continue to be highly correlated with liquidity in the global financial system. My model says each 1% rise in Global M2 YOY adds ~4.5% to fair-value BTC. Model fair value is $136,050.

          On May 26, on Anthony Pompliano’s podcast, I said,

          The mispricing today in Bitcoin is as large as I’ve ever seen before in the model.” And I explained why: “I think that’s because the tech stocks have been so strong that all of the risk capital has fled into tech stocks, and it had to come out of somewhere.

          My conclusion:

          I think we’re seeing a great opportunity today in Bitcoin, certainly the best opportunity I’ve seen in Bitcoin in a decade.

          On June 20, we published an entire issue of my newsletter, Complete Investor, about Bitcoin:

          In this issue, we’re re-recommending Bitcoin (BTC). And we believe buying it now, before the next halving, will prove to be the single best financial decision of the next decade.

          By June 30, Bitcoin had fallen to $58,524. It recovered through August, and today is trading above $79,000. But… despite the rebound… Bitcoin is still trading below the lower 1-sigma band of around $94,000 of our pricing model.

          Nero shaved the denarius. And every empire since then has destroyed itself and most of its people through debasement. But nobody can shave a Bitcoin.

          If you use their money, you’ll be their slave. Free yourself with Bitcoin.

          Tell me what you think of today’s Daily Journal: porterstansberrydirect@gmail.com

          Good investing,

          F. Porter Stansberry
          Stevenson, Maryland


          Presented By: TradeSmith

          cbttninethtradingfour.png

          What Happens on the 9th Trading Day?

          Coming up on the 9th trading day of this month, you buy five specific blue-chip stocks. Then you could potentially watch your money grow like clockwork — all without using leverage or options. Click here to see why just five stocks, and why this one day each month is the only day that really matters.

          Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. TradeSmith is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.


          3 Things To Know Before We Go…

          1. The Atlanta Fed says the economy is growing at a 4.7% annual rate this quarter. That September 3 reading from GDPNow is a “real” figure, meaning it has already subtracted inflation. Add prices back, and nominal growth is running near 8%. The gap with Wall Street is wide: when GDPNow touched 6.2% in early August, economists’ consensus was just 2.2%. At this pace, the October 29 GDP release could show real growth of 6.5% to 7%, five days before the midterms.

          2. August hiring puts a September rate hike back in play. U.S. employers added 162,000 workers to payrolls, roughly three times the 53,000 economists had forecast, and the Labor Department revised June and July up by a combined 55,000, turning a reported July job loss into a gain. Unemployment held at 4.1%. With inflation still above the Fed’s 2% target, Chair Kevin Warsh might push to raise rates. Futures pricing for a quarter-point hike on September 16 moved to 59% from 52% before the release. The two-year Treasury yield, the maturity most sensitive to Fed policy, hit its highest level since January 2025.

          3. Diesel shortage sends prices to new high. The U.S. national average price of diesel fuel has reached a record $5.62 per gallon, surpassing the prior high of June 2022. The market is grappling with an unprecedented shortage driven by the supply-chain disruptions from the war with Iran, with inventories at the lowest seasonal levels on record. Given diesel’s role as a critical transportation fuel, this will likely push prices higher throughout the economy, leading to sticky inflation in the months ahead.


          Chart Of The Day… Morgan Stanley Bitcoin Trust (MSBT)

          The Morgan Stanley Bitcoin Trust (MSBT) has rallied nearly 27% since we re-recommended Bitcoin in the June 20 issue of Complete Investor.


          Mailbag

          “Impossible To Lose Money”

          Bill C. writes:

          Reading through your original product description of Porter’s Permanent Portfolio, it states: “The portfolio is structured in a way that makes it difficult – essentially impossible – to lose money, no matter what happens to the economy, or to individual stocks.

          Well, apparently I have achieved the impossible! My portfolio is DOWN 2.4% YTD. The one-year at 3.8% is positive but lower than target. When I first built the portfolio in late December 2024 I followed the recommendations exactly as well as investment % of each asset.

          Earlier this year, I followed your recommendation and sold all of the P&C assets. That 25% now is a cash from 12.5% recommended to 4%. And moved most of that into FNV and GLD. Gold and Bitcoin are 22% of the portfolio.

          I would appreciate any comment you have as the portfolio is clearly not meeting any of it’s performance expectations.

          Porter Comment: I appreciate you reaching out.

          But I’ve got bad news for you: you’re not following Porter’s Permanent Portfolio.

          It did not sell property-and-casualty (P&C) stock. As I made very clear, the recommended allocation for the Permanent Portfolio would not change until the 10-year yield went to 5% or higher. It has not yet reached that level, and I have not changed any of the allocations on the recommended portfolio.

          Please see the website for the actual current allocations.

          Now, what you’re going to say is, yeah, but you said, x,y, and z.

          And yes, I did. I said if you couldn’t tolerate a drawdown, then you could go to a bigger cash allocation and reduce your volatility.

          If you did that, you’re doing fine.

          But I said, repeatedly, that Porter’s Permanent Portfolio is a “permanent” allocation strategy. It only rebalances once a year. And that strategy hasn’t – and won’t – change unless there is a dramatic change to the market’s fundamentals, like the 10-year moving over 5% yield.

          Here’s the good news: there’s now an ETF that invests exactly in Porter’s Permanent Portfolio – called the Porter & Company Porter Portfolio Index (PCPP).

          Regards,
          Porter


          “Numbers R Us”

          William C. writes:

          Years ago, when we were on the way to do something on Saturday (Daddy day), my youngest (probably eight or nine) exclaimed, “Daddy, look, Toys R Us.”

          I said, “Daddy is Numbers R Us.”

          She is now 31, but her daddy still pays attention to numbers.

          I bought Complete Investor a few years ago, and just watched and kept track of your recommendations for most of a year. I groan every time I see the growth of BWX Technologies (BWXT), which I thought might be good, but it was still early in my watching stage.

          I’ve taken positions in monthly Best Buys.

          Although many won’t put money into investments outside the U.S., when your team presents a case for investing outside our borders, I’ll give it strong consideration. Simply because you and your team provide strong cases with detailed analysis (with lots of numbers) of every recommendation.

          And, they work. I took the leap to become a Partner and have made enough to pay for that in the past year.

          So whether the recommendation is in Arizona, Hell, or thousands or miles outside our border, making money is always good.

          Sincerely

          Porter Comment: Brilliant note – thank you!


          Porter & Co. Market Snapshot

          Price Yesterday’s Return Year-to-Date Return
          S&P 500 Index $7,747.71 1.07% 14%
          Gold per ounce $4,472.92 2.08% 1.3%
          Bitcoin $81,271.74 5.27% -9.2%
          Oil (West Texas Intermediate) per barrel $91.30 0.66% 57.1%
          Berkshire Hathaway (BRK) $763,022.00 0.60% 1.1%
          Porter’s Permanent Portfolio – 1.66% 5.3%
          The Better Than Berkshire Index – 0.73% 8.6%
          Total Return Annual Return
          Porter & Co’s Top Ranked* 36.8% 16.8%
          Yield Yesterday’s Change Change
          Year-to-Date
          U.S Treasury 30-Year Yield 5.25% -1 bps 40 bps
          Prices as of 4:00 pm ET September 3, 2026 | bps = basis points (or 0.01%)
          *A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


          Porter & Co. Top Positions

          Publication Ticker Description Total Return
          Biotechnology QURE uniQure 237%
          Biotechnology SGMT Sagimet Biosciences 203%
          Complete Investor BTC/USD Bitcoin 201%
          Complete Investor BWXT BWX Technologies 182%
          Biotechnology NUVB Nuvation Bio 167%
          Biotechnology TGTX TG Therapeutics 159%
          Biotechnology ROIV Roivant Sciences 152%
          Complete Investor SKWD Skyward Specialty Insurance 136%
          Complete Investor PM Philip Morris 132%
          Biotechnology QURE uniQure 131%
          Prices as of 4:00 pm ET September 3, 2026

          Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

          The post You Probably Don’t Own Bitcoin And That’s A HUGE Mistake appeared first on Porter & Co..

          • ✇Porter & Co
          • Trade Alert And Update – Week Of August 31, 2026 Porter &#38 · Co.
            Before getting into this week’s update, we are recommending the following new covered-call trades: Sell to open one Booz Allen Hamilton (NYSE: BAH) $80 call, expiring October 16, 2026, down to $0.75 per share – the recent price was $1.25 per share Sell to open one Hims & Hers Health (NYSE: HIMS) $33 call, expiring October 16, 2026, down to $0.75 per share – the recent price was $1.15 per share Sell to open one Figma (NYSE: FIG) $25 call, expiring October 16, 2026, down to $1.50 per share –
             

          Trade Alert And Update – Week Of August 31, 2026

          4 September 2026 at 09:00

          Before getting into this week’s update, we are recommending the following new covered-call trades:

          1. Sell to open one Booz Allen Hamilton (NYSE: BAH) $80 call, expiring October 16, 2026, down to $0.75 per share – the recent price was $1.25 per share
          2. Sell to open one Hims & Hers Health (NYSE: HIMS) $33 call, expiring October 16, 2026, down to $0.75 per share – the recent price was $1.15 per share
          3. Sell to open one Figma (NYSE: FIG) $25 call, expiring October 16, 2026, down to $1.50 per share – the recent price was $2.00 per share
          4. Sell to open one Novo Nordisk (NYSE: NVO) $47.50 call, expiring October 16, 2026, down to $1.00 per share – the recent price was $1.65 per share
          5. Sell to open two Triple Flag Precious Metals (NYSE: TFPM) $35 calls, expiring October 16, 2026, down to $1.00 per share – the recent price was $1.55 per share
          6. Sell to open one Turning Point Brands (NYSE: TPB) $85 call, expiring October 16, 2026, down to $1.00 per share – the recent price was $2.10 per share

          The value of The Trading Club tracking portfolio settled at $131,698 as of Thursday, September 3 – up 31.7% since the May 30, 2025, inception date (see the detailed portfolio snapshot below). We made no trades this week.

          In this issue, we explain the rationale behind the covered-call sale recommendations.

          Reducing Risk As AI Financing Risk Looms

          The covered-call trades we’re recommending today are not about expressing a changing view on any of the underlying stocks. Instead, the goal is to reduce overall portfolio risk, but to do so in a way that still leaves significant upside on the table.

          As a reminder, when selling covered calls, we’re making the conscious choice to surrender the upside on the underlying stock at prices above the option strike price. By foregoing that upside to the call-option buyers, we generate a guaranteed return via the immediate cash proceeds collected upon the option sale, regardless of where the stock trades from here. So we’re locking in guaranteed income, while still retaining upside potential – in this case, between 6% and 14% across the various call strikes and the underlying stock prices. Over the relatively brief six-week time period until expiration, this works out to an average annualized return in the triple digits – which, of course, is significant upside.

          The advantage of this strategy is it lets us take a more defensive stance in the portfolio, without making an outright bearish bet on the market, which to avoid losing money generally requires impeccable timing.

          And that brings us to the current dichotomy in today’s stock market. On the one hand, we’re in the midst of one of the greatest earnings booms in the history of the U.S. stock market, which is fueling upward momentum in stock prices that makes it difficult to become too bearish in the short-term. But the problem is, this earnings growth is almost entirely fueled by a capex boom focused on one single area of the economy: data-center construction for the artificial intelligence (“AI”) revolution. Capital spending on every other area of the economy aside from data centers – housing, commercial and industrial, office buildings, etc. – has fallen $120 billion since 2024.

          Every prior capex boom throughout history has ended the same way: when the money runs out. And we’re officially reaching that point, as the companies behind this capex mania are exhausting their access to cheap capital.

          Alphabet (GOOG) just posted negative free cash flow for the first time since going public in 2004. One of the most profitable ad businesses ever built, plus YouTube, Android, and a growing cloud arm – all of which used to produce mountains of cash. But now with capex doubling to nearly $45 billion in a single quarter, the company burned through $6 billion in cash for the quarter. And this trend shows no sign of reversing, with management guiding to $200 billion in capex this year, more than doubling from $91 billion last year.

          Likewise, Amazon (AMZN) burned through $8 billion in Q2 2026, a stunning reversal from the $18 billion in positive free cash flow for the same quarter last year. This trend will only accelerate as the company plans to spend $220 billion on capex this year, up from $132 billion last year.

          It’s the same story across the entire hyperscaler complex, with the group’s free cash flow flipping from hundreds of billions annually into negative territory:

          With free cash flow evaporating, America’s tech giants have become some of the world’s largest issuers of debt.

          In 2025, the group raised a record $200 billion in debt, including the off-balance sheet obligations issued through special purpose vehicles (“SPV”). That’s 4x more than any previous year in history. And in the first eight months of 2026, they’ve already blown this number out of the water with more than $300 billion in debt issuance so far:

          This flood of bond issuance is so large that it’s beginning to crowd out demand for U.S. Treasuries. The 30-year Treasury yield jumped above 5.3% to its highest level in 20 years last month, before a bond-buying intervention from U.S. Treasury Secretary Scott Bessent caused a brief respite. Still, with the volume of tech debt now reaching 70% of U.S. Treasury bond issuance, there’s every reason to expect more upward pressure on borrowing costs across both corporate and government bonds.

          The market is showing signs of stress across multiple indicators. Order books covering hyperscaler bond offerings have dropped from nearly 5x oversubscribed in early 2026 to below 2x.

          A recent report from Goldman Sachs bond trader Jeffrey Papai noted that the $75 billion of AI-related bond issuance in a single month had left the market “struggling to absorb” the supply, sending the credit spread on Goldman Sachs’ AI bond basket higher by 22 basis points in a single week. Papai also described how the market’s absorption capacity is rapidly deteriorating. It previously required over $75 billion in new issuance to feel pressure, but that number has now dropped to $25 billion as the threshold for putting the market “on the defensive.”

          Hyperscalers are now scouring the globe in search of cheaper financing. Alphabet has gone shopping across every major foreign bond market, seeking new offerings denominated in the euro, sterling, Swiss franc, yen, and Canadian dollars. Its recent $8.5 billion Canadian bond issuance was the largest Canadian bond offering in history… that was, until Amazon set a new record weeks later with a $14 billion Canadian bond sale.

          With the world’s largest, strongest balance sheets exhausting their borrowing capacity from all corners of the globe, this is a giant warning sign that capital is becoming increasingly scarce. And that’s a big problem for an economy and stock market reliant on raising endless amounts of capital to keep a capex boom humming.

          For now, the bulls have momentum on their side. And they point toward the rising backlogs and earnings outlooks from the major suppliers of today’s capex boom – like Nvidia (NVDA) and the hyperscalers – as evidence that this capex cycle is just getting started. But in reality, it’s a financial time bomb just waiting to go off. And all signs indicate that 2027 is when the detonation event occurs.

          The Catalyst: OpenAI’s Liability Wall Hits In 2027

          The stress point in the AI capex boom lies specifically with OpenAI – owner of ChatGPT – which makes up the largest source of compute commitments supporting the data center buildout.

          At this time last year, OpenAI reigned supreme over the AI revolution, with over 70% market share and growing at triple digit rates. On the back of that momentum, between June and December of 2025, OpenAI engaged in the most aggressive debt origination spree in the history of capitalism. The climax occurred over a three-week frenzy in October 2025, when OpenAI signed over half a trillion of future purchase agreements with Oracle (ORCL), Nvidia (NVDA), Advanced Micro Devices (AMD), and Broadcom (AVGO).

          In total, this single company has accumulated $750 billion in purchase agreements for data-center capacity and chip sales through 2030. And next year, it begins climbing the steepest part of this contract obligation wall, with $132 billion in bills coming due.

          Now here’s the thing: OpenAI’s financials are already a trainwreck before this mountain of additional liabilities hits. In 2025, the company generated $21 billion in losses on $13 billion in revenue, meaning the business lost $2 for every $1 in revenue. And these losses have only accelerated in 2026.

          From Q1 to Q2 of this year, OpenAI’s revenue increased by $1 billion from $5.7 billion to $6.7 billion. Over the same period, its losses grew by $3 billion from $9.3 billion to $12.3 billion. The company generated an incremental $3 in losses for every $1 of revenue growth.

          In other words, OpenAI loses money on every sale and is trying to make it up in volume. Its own internal financial projections don’t even show the company reaching positive free cash flow until 2030.

          But as bad as the Q2 financial results were, this was before the biggest blow yet: a flood of competition from lower-cost, open-source Chinese AI models hit the market.

          Early on in the AI revolution, OpenAI’s ChatGPT and Anthropic’s Claude enjoyed a wide gap in performance against all other AI models. But more recently, open-source AI models from China have closed the performance gap with their U.S. counterparts:

          Here’s the kicker: these Chinese models have closed this intelligence gap while consuming much less computing power than their U.S. counterparts. As a result, they now offer the same basic AI functionality at a small fraction of the cost, which has crushed pricing across the industry.

          The key metric for monitoring the pricing power among the sellers of AI services is the price per million tokens, where a token is the basic unit of text that a language model processes, generates, and is measured by. After reaching a peak of just over $2 per million tokens in June, prices have collapsed to below $1 per million tokens given the rise of fierce competition from low-cost Chinese AI models:

          OpenAI has responded by slashing prices in order to stoke demand, including an 80% price reduction for one of its latest models, GPT-5.6 Luna.

          History is littered with the ashes of western companies that entered into price wars with China on commoditized products. Steel, rare earth metals, solar panels, electric-vehicle batteries… and now, the same is happening with AI.

          This presents an existential risk for OpenAI, and by extension, America’s AI infrastructure boom.

          OpenAI needs to raise $750 billion by 2030 just to avoid defaulting on its signed-compute and chip-purchase agreements, not to mention hundreds of billions more to cover overhead.

          Our bet is simple: that won’t happen. OpenAI will need a financial miracle just to survive through 2027.

          Here again, the fundamental problem is that the cheap capital fueling the AI bubble is running out. And OpenAI is among the most vulnerable companies in this new era of scarce capital.

          The biggest tell that OpenAI’s funding window is closing came from the company’s latest capital raise in Q1 of this year. On the surface, it looked like a smashing success: the company pulled off the single largest private capital raise of all time – bringing in $122 billion at an $852 billion valuation. But the real story was in who actually wrote the checks.

          Traditional venture capital investors provided only $12 billion, or about 10% of the $122 billion raise. The remaining $110 billion came from the following entities:

          1. $50 billion from Amazon
          2. $30 billion from Nvidia
          3. $30 billion from SoftBank

          In other words, the anchor money – two-thirds of the total – came from OpenAI’s cloud-compute provider and chip supplier. This is the same style of vendor-financing that helped inflate demand during the late stages of the dot-com bubble, and also provided the catalyst that led to the bust.

          Back then, when venture capital began drying up, companies like Lucent and Nortel juiced demand by lending to dozens of privately held startups. It only delayed the day of reckoning. When those private companies began going bust, it led to massive asset impairments and an evaporation of demand that ultimately ended with Lucent and Nortel disappearing into the dustbin of financial history.

          This time, the vendor-financing is concentrated on a single, large entity: OpenAI. But the fundamental mechanics are the same: the lack of demand from venture capital investors for OpenAI shares is currently being propped up by its own suppliers. Companies like Amazon and Nvidia funnel investment capital into OpenAI, which returns that money right back into cloud computing and chip sales to the very same companies.

          But now, with hyperscalers like Amazon looking at negative free cash flow and tapping out the debt market, we see no world where these companies can continue sinking hundreds of billions of dollars into an unprofitable startup company. Even Nvidia – previously having pristine credit – is reaching the limits of using its balance sheet to prop up demand from its own customers. Nvidia now has over $500 billion of off-balance-sheet liabilities across its various backstops, investments, and purchase agreements across the AI ecosystem:

          We can see growing signs of investor concern about Nvidia’s balance sheet through the company’s credit default swaps (“CDS”) – derivative instruments that protect against debt default – which have recently spiked to record highs following a wave of new circular financing deals:

          NVIDIA's five-year CDS soars to record highs—has concern over AI-driven circular financing fully erupted?

          Given this backdrop, we see limited future availability for OpenAI to tap into circular, vendor-financed capital from Nvidia and the hyperscalers.

          But the real weak point in OpenAI’s funding spigot lies with SoftBank (SFTBY), the Japanese holding company that has become a giant, leveraged bet on the AI start up.

          In order to fund its latest $30 billion investment into OpenAI, SoftBank took out one of the world’s largest bridge loans – a $40 billion line of credit that matures in March 2027. This at a time when OpenAI was gearing up for a 2026 IPO. According to various media reports, OpenAI CEO Sam Altman was adamant that the company needed to secure at least a $1 trillion valuation for the IPO to proceed.

          But after bankers and financial advisors poured over OpenAI’s financials, they balked at the $1 trillion valuation target. Instead, they offered Altman two choices: accept a lower valuation to get the IPO out the door, or delay until 2027 and hope the business improves enough to fulfill a $1 trillion valuation. Altman chose to “hope and wait”… but hope, as they say, is not a strategy.

          And it’s already presenting problems for SoftBank, which desperately needed an IPO in order to liquidate its OpenAI stake and repay the $40 billion bridge loan maturing in March. After the IPO progress stalled, in May SoftBank sought out a $10 billion margin loan secured by its OpenAI stake. Something that would have been a routine funding arrangement in the easy-money days was suddenly met with resistance from bankers. Even after scaling down the loan size by 40% to $6 billion, the effort failed. That’s another tell that the financing window for OpenAI is closing: lenders wouldn’t extend a $6 billion margin loan against SoftBank’s stake, valued at $110 billion on the last funding round.

          Ultimately, SoftBank was only able to secure the loan by adding a sweetener: guaranteeing repayment itself so lenders would have recourse to SoftBank directly if the pledged OpenAI shares lost value. Still, the conglomerate faces a liquidity crunch without an ability to monetize its OpenAI stake.

          SoftBank’s stretched balance sheet made it a junk-rated credit even before this borrowing binge. And absent an IPO that allows it to monetize its OpenAI stake, the company could ultimately become a forced seller of OpenAI shares in the private market. This could crush OpenAI’s private market valuation, and make it all the more difficult to continue raising capital.

          Meanwhile, just as SoftBank’s bridge loan comes due in Q1 of next year, OpenAI will be running on fumes. The chart below from Bridgewater Associates projects that OpenAI will run out of cash by Q1 2027, a remarkably short timeline considering the company raised $122 billion just six months ago. And it will need to come up with over $100 billion in new funding next year just to keep the lights on:

          Thus, it’s easy to see how the entire system of leverage begins breaking down, absent an OpenAI IPO in the immediate future. But if the executive behavior inside the company is any indicator, the odds of this happening look increasingly remote. Over the past several months, OpenAI has suffered from a continuous raft of departures from key executives, including:

          • Brad Lightcap (Chief Operating Officer)
          • Denise Dresser (Chief Revenue Officer)
          • Fidji Simo (CEO of Applications)
          • Kaylin Voss (VP of Sales, Americas)
          • Kate Rouch (Chief Marketing Officer)
          • Chris Malone (Head of Data Centers)
          • Caitlin Kalinowski (Head of Robotics & Hardware)
          • Srinivas Narayanan (VP & CTO for Business Applications)
          • Kevin Weil (VP of OpenAI for Science / Former Chief Product Officer)
          • Bill Peebles (Head of Sora Video Generation Team)
          • Barret Zoph (Senior AI Researcher)
          • Johannes Heidecke (Head of Safety Systems)
          • Chloé Bakalar (Head of Ethics)
          • Joshua Achiam (Chief Futurist)

          If OpenAI had any reasonable chance of going public, these executives would be forfeiting the opportunity for generational wealth from their stock grants. The fact that we’re seeing a mass exodus is perhaps the clearest indicator that something has gone horribly wrong inside the business, and that this company will never go public.

          The bottom line: we see OpenAI as the weak link that could cause today’s AI capex boom to break apart as soon as Q1 2027. Of course, the market hasn’t come close to pricing in this scenario. Maybe the market is seeing something we’re not, or it’s simply caught up in a speculative mania that still has legs left before reality sets in.

          In either case, we’re not willing to fight the tide and become outright bearish just yet. But we are shifting to an increasingly defensive stance, and willing to forego upside at this point in the cycle given the risks we see ahead. In the future, we may begin taking outright bearish positions. And we wanted to lay out the rationale now so that we’ll be prepared to act quickly when the time comes.

          Next, we’ll show each position in the portfolio broken down by trade type.

          Portfolio Review

          The table below shows all current holdings as of the close of trading on Thursday, September 3:

          A few notes on how to read and interpret this portfolio table.

          Please pay special attention to the “Action” column, where we specify whether each trade is a “buy” or “sell to open” transaction.

          Next, the position size for each trade is equal to the current value of the position, with the exception of the cash-secured puts. In the case of the cash-secured puts, we define the position size as the total value of our future commitment to purchase 100 shares for each contract. This number is calculated as follows:

          Position size = number of contracts x 100 x put strike price

          We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade.

          For example, in the case of the Celsius Holdings (Nasdaq: CELH) $30 puts, the position size equals 2 x 100 x $30 = $6,000. We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade.

          To see the current profit/loss across each open position and other details, please see the live snapshot of our tracking portfolio at the end of this update.

          We have compiled a summary overview of the latest quarterly trades released on June 22, which you can find here. Since then, we have recommended the additional trades listed below:

          1. On July 17, we recommended purchasing shares of Novo Nordisk (NYSE: NVO), which you can find here
          2. On July 21, we recommended purchasing shares of Hims & Hers Health (NYSE: HIMS), and we provided the analysis for the company on July 24, which you can find here

          If you have any questions or feedback, The Trading Club Forum is the best chance to get a quick response from our team.

          Alternatively, you can always email us at mailbag@porterandcompanyresearch.com.

          Good investing,

          Ross Hendricks
          Porter & Co.


          The post Trade Alert And Update – Week Of August 31, 2026 appeared first on Porter & Co..

          • ✇Porter & Co
          • The Most Famous Gold Chart This Year Porter &#38 · Co.
            Issue#152, Volume#3Follow The Cash – It’s Called Checkbook QE Inside Today’s Issue Essay: The Most Famous Gold Chart This Year The Crowd-Out Of Data-Center Spending Another Nvidia Circular Funding Deal AI Has Not Yet Reduced Inflation Chart Of The Day… Gold Today’s Mailbag Editor’s note: Today, Porter turns the Journal over to his friend Marin Katusa, of Katusa’s Resource Opportunities – who shares the latest opportunities related to gold. The Fed didn’t print a dollar, and gold had its be
             

          The Most Famous Gold Chart This Year

          3 September 2026 at 13:01

          Issue#152, Volume#3

          Follow The Cash – It’s Called Checkbook QE

          Editor’s note: Today, Porter turns the Journal over to his friend Marin Katusa, of Katusa’s Resource Opportunities – who shares the latest opportunities related to gold.


          The Fed didn’t print a dollar, and gold had its best month in 27 years.

          The Federal Reserve’s balance sheet didn’t move an inch this month, and gold still had its best month since 1999.

          If that sounds backwards, you’ve been watching the wrong building.

          On August 19, the U.S. Treasury announced it would double its buybacks of long-dated government debt, from $2 billion an operation to at least $4 billion. Treasury Secretary Scott Bessent calls it a “Treasury Twist.”

          Then on Monday, August 24, two senior Treasury officials told CNBC where the money could come from: the government’s own checking account at the Fed. Bessent has built it to roughly $950 billion. The last Treasury ran it at $550 billion to $600 billion.

          Follow the cash…

          The Treasury buys long bonds from the banks, its balance at the Fed goes down, and the banks’ reserves go up by the same amount. Money that sat frozen in a government account starts moving, and the Fed’s balance sheet never does.

          Nobody has to call it quantitative easing (“QE”), so I’ll call it what it is: Checkbook QE.

          It’s the same liquidity, in a different building, with no press conference.

          Why The Treasury Is Doing The Fed’s Job

          Because the Fed won’t do it. Federal Reserve Chair Kevin Warsh took the helm wanting a smaller central bank, and futures give better than one-in-three odds his Fed hikes this month.

          Meanwhile, the 30-year yield hit its highest since 2007 this month and federal debt crossed $40 trillion. Somebody has to be the buyer of last resort for the long bond. The Fed declined. The Treasury volunteered, and told you where it keeps the money.

          Gold answered inside a week.

          Bullion started August near $4,000 an ounce and traded above $4,700 to end the month, up about 14% on the month. The last time it moved that fast was September 1999, when 15 European central banks agreed to sell less gold. This time a government showed you its checkbook.

          The Most Famous Chart In The Gold Market

          Gold is a great way to be right about Checkbook QE. It’s a slow way to get paid for it.

          M2 hit a record $23.2 trillion this summer. Hold gold at the ratio to the money supply it reached in 1980, and the price lands near $10,000 an ounce.

          Now run the same arithmetic on a miner. The big producers pull an ounce out of the ground for roughly $1,600 all-in, so at $4,000-an-ounce gold, they clear $2,400 an ounce, and at $4,700 they clear $3,100. The metal moved 17%. The margin moved 29%.

          At $10,000, the number is on the chart below, because if I say it out loud you’ll think I’m selling something.

          I am. Just not that.

          Ten Years Of Doing This

          My flagship service, Katusa’s Resource Opportunities, turns 10 this year.

          I started it to show readers the names I own, the price I paid, and why, and to bring them into the private financings I write my own check into first, at the same price and terms.

          • That’s how a $0.90 unit in Artemis Gold’s 2019 financing became a $45 stock.

          The losers are in the letter next to the winners, with what I got wrong.

          The correction left a list of gold producers priced at margins I haven’t seen in my career.

          Some have repriced. Most haven’t.

          The three I’d own first are in a report every new member gets on day one.

          For the anniversary, for 10 days, I’ve reopened the price our charter members paid the day we launched: $1,499 instead of $3,500, with a full refund inside 30 days if it isn’t for you.

          I’ve never reopened that price in 10 years and I won’t again.

          Claim the charter price: $1,499 instead of $3,500.

          The Treasury has $950 billion and just told the market it’s willing to use it. Gold had its best month since 1999 on the announcement alone. The spending hasn’t started.

          Join Katusa’s Resource Opportunities at the 10-year charter price

          Marin Katusa

          Keep in mind, we at Porter & Co. only publish guest essays from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Katusa’s Resource Opportunities is one such partner. We do not, however, under any circumstances, make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.

          Tell us what you think of today’s Daily Journal: porterstansberrydirect@gmail.com

          Presented By: Katusa Research 

          An Important Personal Invitation From Marin Something I’ve Never Done in 10 Years — And Will Never Do Again…

          Marin Katusa is different from the people who just send you stock tips.

          He doesn’t only talk about mines and projects.

          He finances them.

          He’s in the room when the deal is struck, often with millions of his own dollars committed, at the very same price his readers get.

          When he tells you to buy something, his money is already in it.

          And right now, you can join his research service for the lowest price in a decade.

          Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Katusa Research is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.

          3 Things To Know Before We Go…

          1. The AI economy is eating the real economy’s lunch. New Commerce Department data shows that spending on data-center construction dwarfs that on all other private construction. Since December 2023, data-center construction spending is up roughly $45 billion, while everything else – housing, retail, warehouses, manufacturing plants – is down $120 billion and declining. The private economy is being crowded out of capital, labor, and power by one single sector.

          2. The latest circular financing deal. Nvidia (NVDA) and Anthropic have signed a $35 billion cloud-compute deal with Nvidia-backed cloud provider Lambda. In this deal, Lambda will buy the much-in-demand GPU processing chips from Nvidia and then rent them to AI platform Anthropic through a data center site that Nvidia holds the lease on. Yes, that’s right, Nvidia performs three roles in this deal: underwriting the data center, providing equity-backing for the cloud tenant, and supplying the silicon that generates the rental revenue flowing back through the chain. It’s the latest example of the vendor-financing boost Nvidia is providing to stoke demand throughout the AI ecosystem.

          3. Erasing six years of falling software prices. The PCE Price Index for computer software and accessories – a measure inside the Fed’s preferred inflation gauge – has risen at a 39% annualized rate year to date, wiping out roughly six years of decline in just eight months. The broader information processing category – which covers computers, tablets, accessories, and software – rose 15.5% over the past year, and 1.4% in July alone. We’ve been told that AI will push prices down, but we aren’t seeing it yet.


          Chart Of The Day… Gold

          The declining dollar and a turbulent U.S. Treasury market have sent global investors and central banks back to where they feel safe… gold is up 12% over the last month.


          Mailbag

          In yesterday’s Journal, Porter explained the history of oil-tanker pricing to provide insight into the recent surge in shipping costs.

          “Better Reader Than Investor”

          Mike J. writes:

          Really enjoyed your story today, thank you. I owned 2,000 shares of Frontline (FRO) from 2000 to 2009 (approx.). When Jon Frederickson publicly stated the tanker market was going to collapse, soon, around 2009, I didn’t act. My 2,000 shares quickly became 200 with a 10-1 split. I had accumulated just enough dividends over that nine-year period so I was even. I never sold.

          I also remember you pounding your fist during that same period that Microsoft (MSFT) had over $1 billion in cash, and the stock was a steal at $21 per share. I didn’t act on that, either.

          I’m a better reader than I am an investor, so I’ve got that going for me. You’re an excellent writer.

          Thanks again.


          “I’m Older Than You”

          Dom B. writes:

          Porter, A good wake-up call and some perspective. I’m older than you and recall these events well. A word to the wise. Thanks.


          “And One More”

          Jim H. writes:

          You left out NAT, Nordic American Tankers, with the largest fleet of suezmax tankers. They too will post huge profits this quarter.


          Porter & Co. Market Snapshot

          Price Yesterday’s Return Year-to-Date Return
          S&P 500 Index $7,666.60 0.46% 12.8%
          Gold per ounce $4,381.68 1.22% 3.7%
          Bitcoin $77,394 -0.03% -10.4%
          Oil (West Texas Intermediate) per barrel $91.01 0.40% 59.7%
          Berkshire Hathaway (BRK) $758,500.00 0.85% 0.5%
          Porter’s Permanent Portfolio – 0.33% 3.6%
          The Better Than Berkshire Index – 0.09% 7.8%
          Total Return Annual Return
          Porter & Co’s Top Ranked* 35.9% 16.5%
          Yield Yesterday’s Change Change
          Year-to-Date
          U.S Treasury 30-Year Yield 5.26% -2 bps 41 bps
          Prices as of 4:00 pm ET September 2, 2026 | bps = basis points (or 0.01%)
          *A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


          Porter & Co. Top Positions

          Publication Ticker Description Total Return
          Biotechnology QURE uniQure 237%
          Biotechnology SGMT Sagimet Biosciences 204%
          Complete Investor BTC/USD Bitcoin 186%
          Complete Investor BWXT BWX Technologies 175%
          Biotechnology NUVB Nuvation Bio 173%
          Biotechnology TGTX TG Therapeutics 160%
          Biotechnology ROIV Roivant Sciences 151%
          Complete Investor PM Philip Morris 134%
          Biotechnology QURE uniQure 131%
          Complete Investor SKWD Skyward Specialty Insurance 128%
          Prices as of 4:00 pm ET September 2, 2026

          Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

          The post The Most Famous Gold Chart This Year appeared first on Porter & Co..

          • ✇Porter & Co
          • How’s A 30% Annual Dividend Sound? Porter &#38 · Co.
            Issue#151, Volume#3There’s Big Money In Boats Right Now – But Careful, It Won’t Last Inside Today’s Issue Essay: How’s A 30% Annual Dividend Sound? Tax Money Keeps Rolling In… And Out Money Supply Grows Bigger And Bigger Tech Goes From Cap-Light To Cap-Heavy Chart Of The Day… Deere & Co. Today’s Mailbag It’s like trying to drive a car at night without any lights… Many years ago, one of my mentors was explaining the real purpose of prices. Prices convey information across a complex ec
             

          How’s A 30% Annual Dividend Sound?

          2 September 2026 at 13:05

          Issue#151, Volume#3

          There’s Big Money In Boats Right Now – But Careful, It Won’t Last


          It’s like trying to drive a car at night without any lights…

          Many years ago, one of my mentors was explaining the real purpose of prices. Prices convey information across a complex economy. But when the money is “broken” – when it’s constantly inflated by the Federal Reserve – that information in those price signals is corrupted. The feedback mechanism breaks down. As a result, it’s like trying to drive a car at night without any lights – accidents are bound to happen.

          We’re about to see an enormous accident in global tankers. But you’d never know it…

          The shipping tanker market is gushing more cash than I’ve ever seen before. By the time the 3Q dividends land, the six largest tanker companies will have paid out over $3 billion in cash to shareholders this year. The indicated annual yields on some of these stocks is over 30%.

          Should you grab some of this historical cash windfall…? Maybe – but only if you know when the music is going to stop.

          How To Bet On The Boats

          Tankers are the most cyclical, mega-capital industry in the world. Tankers’ depreciation schedules make data centers look like a safe long-term investment! A supertanker costs well over $100 million, takes two to three years to build, starts rusting the day it launches, and always dies young – it’s typically scrapped after two decades.

          Why would anyone want to be in this business? Because the world cannot function without these ships. Roughly a third of the oil consumed on Earth reaches its refinery by ship.

          The cost of the shipping is a tiny fraction of the value of the cargo. So when shipping gets disrupted or when demand for imported oil grows suddenly, there will be enormous increases to shipping rates because demand doesn’t change. A refinery that cannot get crude stocks has to shut down. Shut-in costs more than any freight bill, so refiners bid against each other for the last available vessel. The daily rate to hire very large crude carriers (“VLCC”) does not rise 20% or 40% in a tight market. It increases 500% or 1,000% – usually within days.

          Prices can remain elevated for years because it takes a lot of time to build more ships and because ships are rusting out of the fleet all the time. The gap between when a shortage emerges and the delivery of a new fleet is “the window” – it comes along once every decade or so. And truly immense amounts of money can be made. But you must know when it’s time to leave the party.

          I’ve written previously that the current market cycle reminds me of the 1973-1974 bear market. Energy prices spiked because of a war in the Middle East. U.S. politics were coming unraveled because of Watergate. And stocks were coming off huge highs in 1972, as the Nifty-Fifty – a group of high-quality stocks – were trading at higher multiples than anyone had ever seen before.

          That market also featured a huge tanker cycle – almost exactly like the one we see today.

          Leasing rates on the largest tankers quadrupled between May and September of 1973. Egypt and Syria attacked Israel on October 6 of that year. The Arab oil producers cut supply and embargoed shipments to the United States. The rush to find crude anywhere in the world and to ship it to America was on. The freight market went vertical.

          Then it broke.

          On October 24, spot rates for large tankers fell 75% in only three days. By November they were down 90%. Why did rates collapse so fast and so completely? The embargo cut the volume of oil so completely that there was nothing left to carry.

          But the oil supply crash wasn’t the real disaster. The disaster was what happened next.

          By January 1, 1974, the world’s shipyards had orders for 193 million tons of new tanker capacity – 90% of the entire existing fleet. In other words, the fleet owners ordered themselves an entire second fleet. The new ships came. And kept coming. World tanker capacity – the supply – went from 440 million tons in 1973 to 494 million in 1974, 544 million in 1975, and 633 million by 1978, while the demand didn’t grow at all.

          By Q2 1976, almost 20% of the entire world tanker fleet was moored and out of service. But idling a ship is not free: keeping a supertanker anchored costs as much as $75,000 a month. Plus, it costs roughly $700,000 to prepare it and secure a berth.

          By February 1979, the rate index for the largest tankers had fallen to a level roughly 95% below the 1973 peak. In April 1983, a full 10 years after the peak, the world had 310 million tons of tanker capacity available but it still only needed 137 million. There was a surplus of 173 million tons, meaning more idle oil-carrying capacity than the entire industry could employ!

          It Happened Again In 2008

          I wasn’t in the markets during the 1970s, but I watched the same cycle happen again in the mid-2000s.

          As China’s economy boomed following its entry into the World Trade Organization (“WTO”), demand for crude carriers surged amidst a broad commodities mania. Oil surged from $30 to $147.50 a barrel by July 11, 2008. Demand for tankers followed crude higher. Rates for the largest tankers averaged $53,000 a day in January of 2008 and peaked above $169,000 a day by July.

          What happened next? Global tanker building contracts, which had been running $30 billion a year, jumped to $91 billion in 2004, $104 billion in 2005, and $135 billion in 2006. The price of a new supertanker went from $63.5 million in 2002 to $129 million by the end of 2006. But owners kept ordering. By January 2007, Clarkson’s (the world’s largest shipbroker) put the global orderbook at 300 million tons – roughly 31% of the existing fleet.

          The bust took five years to work through. And not everyone survived. Overseas Shipholding Group, then the largest American tanker operator, filed for bankruptcy in November 2012 with $4.15 billion of assets against $2.67 billion of debt.

          Today, we’re sitting in “the window” – supplies for tankers are super tight. Leasing rates have soared. And a whole new fleet is on order. The clock is ticking… but how long will “the window” stay open?

          With the war in Iran this spring, the Strait of Hormuz was effectively closed. That left a huge number of tankers stranded in the Persian Gulf. Rates for the largest tankers touched $436,000 a day. Traffic has been resuming gradually, though ships are still sitting idle around the strait waiting to move. Every ship stuck at anchor is a ship not competing for cargo. Veson Nautical (whose software handles booking and payment for the fleet) does not expect full normalization before the end of this year.

          The other factor pushing leasing rates higher isn’t transitory. Oil production keeps rising in the United States, Guyana, Brazil, and Argentina while consumption growth is highest in Asia. A barrel shipped from Guyana to China occupies a vessel far longer than a barrel shipped from the Persian Gulf to Japan. The industry counts demand in ton-miles. The longer the voyage, the higher the transportation cost, and the more demand for ships grows.

          Finally, there is the age of the fleet. Nearly half the world’s tanker capacity is more than 15 years old. Roughly 130 supertankers aged 20 or more are still trading today against fewer than 20 of them five years ago. Old ships sail slower, sit longer in port, and carry less.

          But… the new ships are coming. Through the end of July, fleet owners contracted 96.4 million tons of new tankers, against a previous annual record of 81.3 million tons set in 2006. This year’s new ship contracting will surpass 100 million tons. So far, shipping companies have ordered 197 supertankers and 103 Suezmaxes (the largest ships that can transit the Suez Canal), records in both classes.

          But they aren’t on the market – yet. In a “normal” year, something around 40 supertankers are delivered. But only one supertanker was delivered in 2024. And only five in 2025. Owners only scrapped 2.16 million tons in 2026. The order book delivers in 2027 and 2028.

          Until the new boats come online, there’s a lot of money to be made in shipping.

          Frontline (FRO) earned $659.2 million in Q2, $2.96 a share, on revenue of $943.3 million. Its supertankers earned $152,700 a day against the $23,800 a day Frontline needs to cover cash costs. It declared a $2.61 a share dividend, which is 100% of adjusted profit, and an annualized yield of 23.6%.

          International Seaways (INSW) earned $294.9 million in adjusted profit, $5.91 a share, and generated $261 million of free cash flow, a company record by roughly $100 million. Its fleet averaged $79,000 a day against $27,500 a year earlier, its supertankers cleared $150,000. The board declared $5.05 a share on August 7. That’s 20.2% annualized.

          DHT Holdings (DHT) earned $198.3 million, $1.23 a share, with its spot vessels earning $162,600 a day against cash costs of $22,600. DHT made more money in the first half of 2026, $362.9 million, than in any full year in its history. It declared a quarterly of $1.22, which is 100% of ordinary profit and annualizes to 24.8%.

          Okeanis Eco Tankers (ECO) earned $230.3 million against $26.9 million a year earlier. It paid $5.25 a share on August 21, which annualizes to 30.9%.

          So… the question is… how long will “the window” remain open?

          We can see the next two quarters clearly, because the ships are already booked.

          • Frontline has 86% of its Q3 supertanker days fixed at $156,900 a day, above the $152,700 it just earned, and 79% of Suezmax days at $117,400 against $111,500
          • DHT has 1,020 days chartered out at $75,900 and 58% of its spot days booked at $152,700
          • International Seaways has 48% of its days at $61,000 blended across crude and refined product against cash costs running between $14,500 and $25,700, those bookings pay the dividends through the end of the year

          How much longer can it run after that…? Maybe another one or two quarters, with risk growing substantially after June of next year.

          What will the crash look like?

          The tanker orderbook today stands just over 31% of the fleet, where in January 1974 it stood above 90%. Owners cannot flood this market the way their grandfathers did. And the fleet is old. There are a lot of boats that need to be replaced.

          But investors should remember: After the last boom in 2008, Frontline’s dividend went from $3.00 to $0.02 in 11 quarters.

          Tell me what you think of today’s Daily Journal: porterstansberrydirect@gmail.com

          Good investing,

          Porter Stansberry
          Stevenson, Maryland

          Presented By: TradeSmith

          cbttninethtradingfour.png

          What Happens on the 9th Trading Day?

          Coming up on the 9th trading day of this month, you buy five specific blue-chip stocks. Then you could potentially watch your money grow like clockwork — all without using leverage or options. Click here to see why just five stocks, and why this one day each month is the only day that really matters.

          Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. TradeSmith is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.


          3 Things To Know Before We Go…

          1. Federal tax revenue keeps rising, but spending is rising faster. The U.S. Treasury collected a record $5.23 trillion in fiscal 2025, up 6.4% from the prior year. Yet it spent $7.01 trillion, leaving a $1.78 trillion deficit. Through the first 10 months of fiscal 2026, revenue is up $139 billion, or 3%, while outlays are up $309 billion, or 5%. Taxes aren’t the problem… spending is.

          2. Money supply keeps climbing. Global money supply reached a new high of $150 trillion in June, up $10.7 trillion (8%) over the past year. Since the COVID-19 outbreak in 2020, global money supply has expanded by $50 trillion, driving consumer prices and interest rates higher with it. With no end in sight to the monetary expansion from global central banks, inflation and interest rates will likely remain stuck in a “higher for longer” regime for the foreseeable future.

          3. Big Tech is now more capital-intensive than mining. Alphabet’s (GOOG) capital spending reached $44.9 billion last quarter versus $39.1 billion of cash generated by operations – 115% – producing its first negative free cash flow since its 2004 IPO. Meta (META) spent 98% of its operating cash. Amazon (AMZN) also spent more than it generated in cash over the past year. Meanwhile, the largest gold and silver miners spend less than 50% of operating cash on capex. The AI buildout has turned the most capital efficient businesses in history into mining companies with worse assets. At least a gold deposit produces for decades. A rack of AI chips is written off in five years.


          Chart Of The Day… Deere & Co. (DE)

          Strong demand for its agricultural and manufacturing equipment has sent shares of Deere & Co. considerably higher over the last month – up 18% in August and 71% since we recommended them to Complete Investor subscribers.


          Mailbag

          Yesterday, Tuttle Capital CEO Matt Tuttle explained to Journal readers the logic behind the Porter & Company Porter Portfolio Index ETF (PCPP), based on Porter’s Permanent Portfolio.

          “Don’t Play FOMO”

          Linda T. writes:

          I totally agree with Porter and Tuttle. Playing FOMO does not work for investors with a longer-term view. CNBC’s Jim Cramer is just a “quacker” quack, quack, for audience clicks. Thanks for the good information.


          “How Long Can It Be Maintained?”

          Tony G. writes:

          I think PCPP is an awesome concept and hope that it gets the traction it deserves. The risk is identified within the article itself though – being early, and even right, is not necessarily a recipe for success. The anti-Cramer fund shut down after a year…How long is something maintained if it’s not making money?

          Best wishes for all your endeavours!


          Porter & Co. Market Snapshot

          Price Yesterday’s Return Year-to-Date Return
          S&P 500 Index $7,631.47 -0.71% 12.3%
          Gold per ounce $4,328.82 -2.41% 0.3%
          Bitcoin $77,414 -1.83% -12.4%
          Oil (West Texas Intermediate) per barrel $90.22 4.53% 55.7%
          Berkshire Hathaway (BRK) $752,091 -0.60% -0.4%
          Porter’s Permanent Portfolio – -0.73% 3.2%
          The Better Than Berkshire Index – -0.76% 7.7%
          Total Return Annual Return
          Porter & Co’s Top Ranked* 35.3% 16.2%
          Yield Yesterday’s Change Change
          Year-to-Date
          U.S Treasury 30-Year Yield 5.27% 3 bps 43 bps
          Prices as of 4:00 pm ET September 1, 2026 | bps = basis points (or 0.01%)
          *A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


          Porter & Co. Top Positions

          Publication Ticker Description Total Return
          Biotechnology QURE uniQure 237%
          Biotechnology SGMT Sagimet Biosciences 195%
          Complete Investor BTC/USD Bitcoin 187%
          Complete Investor BWXT BWX Technologies 185%
          Biotechnology NUVB Nuvation Bio 161%
          Biotechnology TGTX TG Therapeutics 158%
          Biotechnology ROIV Roivant Sciences 153%
          Complete Investor PM Philip Morris 133%
          Complete Investor SKWD Skyward Specialty Insurance 133%
          Biotechnology QURE uniQure 131%
          Prices as of 4:00 pm ET September 1, 2026

          Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

          The post How’s A 30% Annual Dividend Sound? appeared first on Porter & Co..

          • ✇Porter & Co
          • The Long-Legged Leader Of Biotech Porter &#38 · Co.
            This Is Why We Love Big Pharma Porter & Co. High Conviction does not follow a regular schedule. We only publish it when we believe the recommendation is so certain to be a long-term winner that we’d be prepared to invest 100% of our capital into it. To be clear, a high-conviction opportunity isn’t necessarily about how much a share price might appreciate – but rather, the probability that a share price will rise steadily over time. Sometimes, these situations may only result in a modest aver
             

          The Long-Legged Leader Of Biotech

          2 September 2026 at 07:03

          This Is Why We Love Big Pharma

          Porter & Co. High Conviction does not follow a regular schedule. We only publish it when we believe the recommendation is so certain to be a long-term winner that we’d be prepared to invest 100% of our capital into it.

          To be clear, a high-conviction opportunity isn’t necessarily about how much a share price might appreciate – but rather, the probability that a share price will rise steadily over time. Sometimes, these situations may only result in a modest average annual gain… but it comes with far less risk than your average investment.

          That’s the opportunity we’re presenting in this issue, with one of the pharmaceutical world’s most well-known and established brands. The company was founded in 1758. But over the last few years, the company has emerged as a Big Pharma leader while at the same time becoming an exciting growth story in the biotech world.


          Talk about a Lindy business – which Porter describes as a company with excellent economics and long track records in the marketplace, of at least 20 years… This biotech firm has been at it for 268 years. And it continues to crush it.

          Novartis (NYSE: NVS) traces its roots to a Basel, Switzerland, dye-works founded in 1758. The $300 billion market-cap company now sells medicines in around 80 countries, earned a 41.2% operating margin on $14.4 billion of sales in the most recent quarter, and converted $5.6 billion of that quarter’s revenue into cash. It paid shareholders a remarkable $7.8 billion in dividends last year.

          Novartis has produced a first-in-class medicine in nearly every modern modality.

          • Approved in 2001, Gleevec was the first drug designed to jam the single enzyme that drives chronic myeloid leukemia
          • Approved in 2017, Kymriah was the first approved therapy that reprograms a patient’s own immune cells to hunt cancer
          • Approved in 2017, Zolgensma delivers a working gene inside a virus to infants born without it
          • Approved in 2018, Lutathera (and later Pluvicto) attach radiation to molecules that seek out tumors
          • Approved in 2026, Fabhalta slows kidney function decline in IgA nephropathy, blocks part of the immune system’s complement cascade with a twice-daily capsule

          The management still guides to 5% to 6% sales growth a year through 2030 because innovation in the pharma industry continues to produce new, higher-quality, patent-protected medicines. Novartis has re-stocked its patent portfolio with gene-silencing drugs. It is currently ramping sales of Leqvio – developed by Alnylam Pharmaceuticals (ALNY) – a twice-yearly cholesterol injection, which sold $1.2 billion in 2025 and $480 million in the June quarter alone, both up 59% year-over-year.

          Plus – and this is the big one – we believe Novartis is going to win the race to the first Lipoprotein(a) target. Lp(a) is a cholesterol-carrying particle set almost entirely by the genes a person is born with. Diet does not move it. Exercise does not move it. Statins barely touch it. It causes heart attacks, strokes, and a narrowing of the aortic valve, and no approved drug lowers it.

          Novartis enrolled 8,323 patients with established heart disease in Lp(a)HORIZON, the first trial ever run to prove that lowering Lp(a) prevents cardiovascular events rather than merely moving a laboratory number. Results arrive in the second half of this year. Novartis intends to file with the Food And Drug Administration (“FDA”) this year.

          Novartis licensed its Lp(a) gene-silencing drug, called pelacarsen, from Ionis Pharmaceuticals (IONS) in February 2019, took worldwide responsibility for developing, manufacturing, and selling it, and has funded the 8,323-patient trial since.

          An estimated 18.7 million American adults have established cardiovascular disease, and roughly 21% of them carry Lp(a) above the level Novartis used to enroll its trial – 3.9 million people in the U.S. alone. Only 2% of American cardiovascular patients have ever been tested for it.

          In March 2026, the American College of Cardiology and the American Heart Association began recommending that every adult have Lp(a) measured at least once, and that the relatives of anyone with a high reading be tested too.

          The three lead Lp(a) drugs are estimated to generate $5.6 billion combined by 2032. One estimate models pelacarsen above $3 billion at its peak. Our own model, built from the diagnosed population upward, produces $4 billion in 2032 annually and $13 billion annually by 2036.

          Why Novartis Is High Conviction

          If pelacarsen sells on the low side, $3 billion a year, Novartis collects about $2.4 billion of it. Ionis gets roughly $450 million. Royalty Pharma (RPRX) takes the remaining $150 million. Novartis keeps $4 out of every $5. The company that discovered this molecule, that spent three decades learning how to build it, will keep about 15 cents of every dollar it earns. That’s the power of Big Pharma.

          And it gets better… Novartis trades at 18x trailing earnings and pays a 3% dividend. The huge opportunity in Lp(a) isn’t priced into the stock.

          That’s why Porter will continue to recommend Big Pharma in our Porter & Co Biotechnology portfolio – and that’s why we are making Novartis part of High Conviction now. Novartis is likely to be one of the single biggest growth companies in the world over the next 20 years, despite its current (large) size.

          Action to Take: Buy Novartis (NYSE: NVS) up to $165 per share

          Porter & Co. Stevenson, Maryland

          The post The Long-Legged Leader Of Biotech appeared first on Porter & Co..

          • ✇Porter & Co
          • Why Good Investment Ideas Might Start Out Unpopular Porter &#38 · Co.
            Issue#150, Volume#3And Quite Often Don’t Get You Invited To Appear On CNBC Inside Today’s Issue Essay: Why Good Investment Ideas Might Start Out Unpopular El Niño And Commodity Prices More On Bessent And Bonds A September To Remember… Or Not Chart Of The Day… Veeva Systems (VEEV) Today’s Mailbag Editor’s note: Today, Porter turns the Journal over to Matt Tuttle, CEO of Tuttle Capital Management and portfolio manager of the Porter & Company Porter Portfolio Index ETF (PCPP). In late 20
             

          Why Good Investment Ideas Might Start Out Unpopular

          1 September 2026 at 13:00

          Issue#150, Volume#3

          And Quite Often Don’t Get You Invited To Appear On CNBC


          Editor’s note: Today, Porter turns the Journal over to Matt Tuttle, CEO of Tuttle Capital Management and portfolio manager of the Porter & Company Porter Portfolio Index ETF (PCPP).


          In late 2021, betting against Cathie Wood felt about as smart as betting on rain in San Diego.

          Wood’s ARK Innovation ETF (ARKK) had returned 153% in 2020, against roughly 18% for the S&P 500, and the press had decided that she was the next Warren Buffett.

          But the returns were the story, not the holdings. In my view, ARKK held the opposite of what I look for in an investment: the fund was full of richly valued companies with limited cash generation, and its shareholder base had mostly bought after the sharp runup in prices.

          So I built a fund, the Tuttle Capital Short Innovation ETF (SARK), which sought the inverse of ARKK’s daily return through a swap agreement. That is – as ARKK fell (which I was pretty sure would happen before long), SARK would rise.

          My fund found an audience quickly. Wood had a loyal following that took the fund personally – and I heard from a lot of them. Their catcalls, though, didn’t change what was in her portfolio.

          In a similar vein… Porter Stansberry had spent years making an unpopular argument of his own: that the dollar was being eroded, that the deficit arithmetic didn’t work, and that the “safe” asset sitting in every retirement account had quietly become one of the riskiest things a person could own.

          He’d built a portfolio around it. What he needed was someone who could turn that into an index and then leave it alone, even if it might look foolish in any given quarter.

          And that’s how our fund, the Porter & Company Porter Portfolio Index ETF (ticker symbol PCPP), came about.

          The index holds not one, but four generally unfashionable positions:

          1. Cash-generating businesses, instead of the hot story
          2. Insurance companies, instead of government bonds
          3. Gold and Bitcoin, and
          4. Short-dated bonds, instead of reaching for yield

          I’ll come back to how those fit together. First, though… why I think being unpopular is worth something.

          The Receipts

          About 16 months after building SARK, I built a fund that took the other side of the on-air stock picks of CNBC shouting-head Jim Cramer.

          I loved the idea, but the fund didn’t work. I shut it down inside a year, at a loss.

          The point, though, was never the return.

          My aim was to highlight how – and ask why – a man can go on television every weekday for two decades, tell a national television audience what stocks to buy, be wrong repeatedly and at scale, and face no formal accountability. He said Bear Stearns was just fine – days before it went under. He called Silicon Valley Bank a “buy” on air one month before regulators closed the bank. He compared Sam Bankman-Fried to J.P. Morgan.

          The fund closed, but the point remains. And, incidentally, I haven’t been back on CNBC since.

          My firm’s tagline is “The antidote to Wall Street.” We mean it, and it has cost us.

          Why Being Early Might Look Like Being Wrong

          Here’s what I learned building those funds in public.

          Financial TV isn’t lying to you. From my point of view, it’s doing something more subtle. I see the real problem is that it needs characters – not analysts.

          The easiest way to stay on the guest list is to be a “perma-something.” Always bullish, always bearish, it doesn’t much matter which. Repeat the same forecast for long enough, and the market eventually obliges.

          Then you’re the person who called it. The dozen wrong calls before that disappear.

          What doesn’t get you booked is being right early – and downright inconvenient in the meantime.

          Years ago, I made a simple observation to a reporter about a large brokerage and one of its analysts. He told me he couldn’t print it. His editor would kill him.

          Let me guess, I said. It’s a major advertiser for the paper?

          He nodded. Yep. And that, I’d argue, is how the system works. Who loses? I think it’s the guy who takes what the talking heads are saying at face value.

          Porter Got The Same Treatment

          Porter spent years saying the U.S. dollar wouldn’t stay dominant forever, that the deficit arithmetic didn’t add up, and that long-term government bonds, the very thing investors are told is safe, had quietly become one of the riskiest assets you could own.

          For most of those years, that made him sound like a crank to the institutions selling the old playbook. Then 2022 happened. Then April 2025 happened. Some of the same institutions now make a version of the same argument.

          Which brings me to the thing I actually believe: Being unpopular with the crowd isn’t by itself a flaw in an investment thesis. Plenty of unpopular ideas are simply wrong. But an idea that everyone already holds has no advantage left in it.

          Four Positions, Not One

          So here is how those four positions inside PCPP actually work. It’s worth stating plainly up front that the fund is passively managed, and these four positions reflect the methodology of the underlying rules-based index rather than a manager’s view.

          The stock sleeve screens on historical cash conversion and shareholder distributions. Consensus says buy the index and own everything in it. This owns a screened subset rather than the whole index.

          The “bond” sleeve isn’t bonds. It’s property and casualty insurers – the companies that write home, auto, and business policies, chosen for underwriting quality. They stand in for the government debt that did not hedge equity losses in 2022 or in April 2025.

          The hard-assets sleeve pairs gold and Bitcoin. Gold is the 5,000-year store of value everyone knows. Bitcoin is the newer digital asset built to be scarce and is maintained by network consensus rather than a central issuer.

          The fixed-income sleeve is short-dated bonds and Treasury funds that mature in a few years rather than a few decades. Consensus calls that a drag on returns. The intent is to hold assets that can be sold without a large loss of principal, so the annual rebuild has something to draw on.

          And none of it runs on judgment. Fixed targets, a published methodology, an annual rebuild.

          Four uncomfortable positions in one ticker. Porter & Co. creates the index. As the adviser, I can’t override it. Which is the point.

          Why The Rules Matter

          Most investors can hold one contrarian view. That’s uncomfortable but survivable. Almost nobody can hold four of those views – at once.

          Experience tells me there tends to be one you talk yourself out of, usually not long before it turns. Sometimes it never does.

          And while a rules-based structure doesn’t make that discipline easier, it removes the discretion. It does not remove the risk that the rules produce poor results.

          Early Isn’t Always Wrong

          Early can just feel wrong for an uncomfortable length of time.

          I’ve been shouted down for the Cathie Wood ARK Innovation trade and mocked for the Cramer one. I’d take both again.

          Porter spent his career researching how to hold a portfolio through different market environments.

          The index attempts to express that view in a single set of rules.

          You can see the whole thing at porterandcofunds.com.

          Matt Tuttle, CEO/CIO
          Tuttle Capital Management

          P.S. Every morning before the open, I publish The Daily H.E.A.T., my framework applied to whatever the market is doing that day. It’s free. Sign up here.

          Tell us what you think of today’s Daily Journal: porterstansberrydirect@gmail.com


          Presented By: Tuttle Capital Management


          3 Things To Know Before We Go…

          1. Barclays expects a record El Niño to push commodity prices sharply higher. The National Oceanic and Atmospheric Administration (“NOAA”), the U.S. government’s weather and ocean agency, puts the odds of the strongest El Niño ocean-warming event on record since 1950 at 69% for October through December. Analyst Craig Rye sees commodities including coal, coconut oil, copper, rice, and rubber rising up to 50% over 24 months. Prices are already moving: the S&P GSCI commodity index has gained roughly 50% this year, and copper already trades near a record.

          2. The bond market has stopped listening to the Treasury. Thirteen days ago, Treasury Secretary Scott Bessent announced he would at least double the government’s bond buybacks – purchases of older long-term debt meant to push yields down – to at least $4 billion per operation. Long yields dropped for a few hours, then gave it all back. The 30-year sits at 5.25% today versus 5.26% just before the announcement. The 10-year touched 4.79%, its highest since January 2025, after Fed Chair Kevin Warsh’s hawkish Jackson Hole remarks on Friday pushed the odds of a September rate hike above 65%. The composition of that move matters more than the level: of the 76-basis-point rise in the 10-year yield since the Iran War began on February 28, 70 basis points came from real yields – the return investors demand above expected inflation – and just six from inflation expectations. A rate hike will not fix that. Investors are simply demanding more yield to hold $40 trillion of federal debt.

          3. September has the weakest S&P 500 average return of any month going back 75 years. But averages hide the distribution – a handful of ugly Septembers (2001, 2008, 2022) drag the number down, while plenty were positive. More relevant for 2026 is the election cycle. In midterm years, September has historically been breakeven, and the two months after it have been among the strongest stretches of the entire four-year cycle. We’ll see if this year is any different.


          Chart Of The Day… Veeva Systems (VEEV)

          Veeva Systems (VEEV) is a software platform that supports the biotech industry – one of Porter’s tollbooth section of Biotechnology. Veeva shares are up 41% since the August 1 recommendation.

          ⚙ Edit 🗑 Delete

          The next Porter & Co. Biotechnology issue – with new recommendations from Porter – reaches paid-up subscribers on Saturday, September 5. Click here to learn how to get on that list.


          Mailbag

          Yesterday, Porter reported that Amazon founder Jeff Bezos once described to shareholders a hypothetical future business that developed teleportation machines. And just like CoreWeave’s incredible data centers of today, Porter explains, these machines were revolutionary, consumer demand was endless – and the business was unsustainable.

          “A Bezos Teleportation Machine”

          Randy M writes:

          Where can I get one of Jeff Bezos’ teleportation machines and teleport back in time and purchase more Amazon? ….and a Partner Pass?


          “Refreshing To Read”

          Guy S. writes:

          Your contrast between CoreWeave and Amazon is an analysis of rare quality – far superior to the typical financial newsletter drivel. Debt-to-revenue is among the many metrics, along with debt growth-to-revenue growth, I have employed in my stock analysis (profitably) for many years.

          Refreshing to read – thank you.


          “Too Long”

          Mario R. writes:

          You had a very good point and detailed explanation on why CoreWeave will go out of business.

          My only comment is that you had made the point loud and clear in the first half of your article – the rest, you went on and on, which was overkill and a waste of reader’s time.

          It’s best to just go right to the point and then stop.

          Porter & Co. Comment: Ok.


          Porter & Co. Market Snapshot

          Price Yesterday’s Return Year-to-Date Return
          S&P 500 Index $7,686.14 -0.33% 13.1%
          Gold per ounce $4,431.10 0.00% 0.8%
          Bitcoin $78,548.63 0.34% -11.5%
          Oil (West Texas Intermediate) per barrel $85.76 1.26% 53.3%
          Berkshire Hathaway (BRK) $756,650.01 -0.18% 0.2%
          Porter’s Permanent Portfolio – -0.56% 4.0%
          The Better Than Berkshire Index – -0.90% 8.6%
          Total Return Annual Return
          Porter & Co’s Top Ranked* 35.4% 16.3%
          Yield Yesterday’s Change Change
          Year-to-Date
          U.S Treasury 30-Year Yield 5.24% 4 bps 40 bps
          Prices as of 4:00 pm ET August 31, 2026 | bps = basis points (or 0.01%)
          *A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


          Porter & Co. Top Positions

          Publication Ticker Description Total Return
          Biotechnology QURE uniQure 237%
          Complete Investor BTC/USD Bitcoin 191%
          Biotechnology SGMT Sagimet Biosciences 191%
          Complete Investor BWXT BWX Technologies 169%
          Biotechnology NUVB Nuvation Bio 162%
          Biotechnology ROIV Roivant Sciences 153%
          Biotechnology TGTX TG Therapeutics 153%
          Complete Investor PM Philip Morris 133%
          Complete Investor SKWD Skyward Specialty Insurance 133%
          Biotechnology QURE uniQure 131%
          Prices as of 4:00 pm ET August 31, 2026


          Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

          The post Why Good Investment Ideas Might Start Out Unpopular appeared first on Porter & Co..

          • ✇Porter & Co
          • Leopold’s Software Glitch Porter &#38 · Co.
            Issue#147, Volume#3He Thought AI Would Eat These Application – But He Had It Backwards Inside Today’s Issue Essay: Leopold’s Software Glitch Leopold Tops This List All Presidents Run Up Debt All-In On Tech Stocks Chart Of The Day… uniQure (QURE) Editor’s note: Today, Porter delivers part two of a three-part series on the implosion of Leopold Aschenbrenner’s Situational Awareness fund – and the key reason behind its failure that everyone seems to be missing… The final installment of this th
             

          Leopold’s Software Glitch

          26 August 2026 at 13:00

          Issue#147, Volume#3

          He Thought AI Would Eat These Application – But He Had It Backwards

          Inside Today’s Issue

          • Essay: Leopold’s Software Glitch
          • Leopold Tops This List
          • All Presidents Run Up Debt
          • All-In On Tech Stocks
          • Chart Of The Day… uniQure (QURE)


          Editor’s note: Today, Porter delivers part two of a three-part series on the implosion of Leopold Aschenbrenner’s Situational Awareness fund – and the key reason behind its failure that everyone seems to be missing… The final installment of this three-part series will appear in the next Journal, on Friday.

          Also note this brief update to Monday’s essay, when we reported that Intuit (INTU) was a stock that Leopold Aschenbrenner’s Situational Awareness fund had shorted. Yesterday, Intuit reported fiscal Q4 results and guided fiscal 2027 non-GAAP earnings to $22.88–$23.12 per share against a Wall Street consensus of $27.31. Some people on Wall Street believe (like Leopold) that this is more evidence of the “death of software.” We disagree.

          What actually happened is far more banal: effective August 1, Intuit stopped stripping out share-based compensation from these adjusted numbers. CFO Sandeep Aujla said the 2027 guidance carries a $5.81 impact from stock-based compensation expenses. Ergo, when you add $5.81 back, the guidance midpoint is $28.81 per share, 5% above the $27.31 estimate.

          Here’s another way to look at it. Intuit’s GAAP accounting requires no reconstruction. Aujla guided fiscal 2027 GAAP earnings per share to $20.12-$20.36, (growth of 22%-24%) against a $19.94 consensus. Those are not the numbers of a dying business.

          Fiscal 2026 revenue grew 14% to $21.4 billion. Non-GAAP operating margin expanded 1.5 points to 41.7%. Q4 adjusted earnings came in at $4.03 per share against a $3.58 estimate. Mid-market revenue grew 39% with customers up 28%, and Intuit Enterprise Suite – the accounting and payroll package sold to companies too large for QuickBooks Online – passed $145 million in annualized revenue, 4x the prior year.


          Microsoft (MSFT) passed 30 million paid Copilot seats in the June quarter, up from 15 million in January. Tech wizards like Leo Aschenbrenner hate Copilot – Microsoft’s artificial intelligence (“AI”) assistant. Just like they hated Windows ’97. And everything else Microsoft has ever built.

          So what?

          Accenture alone bought 740,000 Copilot seats. Bayer, Johnson & Johnson, Mercedes-Benz, and Roche have each deployed more than 90,000. Microsoft’s commercial remaining performance obligation – contracted revenue not yet recognized, which is the closest thing software has to a railroad’s signed freight contracts – stands at $678 billion, up 84% year over year!

          Annual recurring revenue for Adobe’s (ADBE) AI-first passed $500 million in the quarter ended May 2026 and tripled year over year. Salesforce’s (CRM) Agentforce went from $800 million of annual recurring revenue in the January quarter to $1.2 billion by April, up 205%. Veeva Systems (VEEV) is giving its AI agents away free inside Vault CRM through 2030, which is the single most revealing data point in the set: Veeva does not need to monetize AI, because Veeva’s moat is the validated record, not the intelligence applied to it.

          Aschenbrenner thought AI would eat the applications. Instead, the applications are selling AI as an upsell on top of a subscription the customer cannot afford to cancel – because it costs nothing compared to the value it delivers.

          These software companies are computing tollbooths: they’re what enterprises pay to implement compute. And as compute gets cheaper, they will generate vastly more revenue, not less. The proof is sitting there in their earnings and cash flow: they’re riding on lower and lower cost of compute, which makes their business more and more efficient.

          • Adobe: 36.6% operating margin, 35.6% return on invested capital (“ROIC”), capital expenditure of $179 million on $23.8 billion of revenue – 0.75% – and $9.85 billion of free cash flow (“FCF”)
          • Veeva: 28.7% operating margin, 68.5% ROIC, a 44.3% FCF margin, and effectively no capex at all
          • Salesforce: $41.5 billion of revenue, roughly $14.4 billion of FCF, capex of about 1.4% of revenue, and $72.4 billion of contracted backlog
          • Intuit (INTU): $18.8 billion of revenue, roughly $6.1 billion of FCF, $124 million of capex

          Veeva earns 68 cents a year on the dollar. And invests nothing in growing its business.

          Adobe currently trades at about 11x trailing earnings. Salesforce at about 13x. Intuit at about 14x. These are the multiples of a dying industry applied to businesses converting a third to nearly half of every revenue dollar into free cash.

          This enormous mispricing was manufactured by people who, like Aschenbrenner, believed these businesses were doomed. But they aren’t.

          And that’s not all.

          Aschenbrenner assumed that because a technology is transformative, the capital that builds it will earn its cost.

          There is no relationship between those two things. In fact, it’s more likely not to be true.

          Leo’s own essay contains the tell:

          Over the past year, the talk of the town has shifted from $10 billion compute clusters to $100 billion clusters to trillion-dollar clusters. Every six months another zero is added to the boardroom plans.

          He wrote that as a bull case. But it isn’t. That is a recipe for a financial disaster.

          • Amazon (AMZN) spent $131.8 billion of capex in 2025 against $139.5 billion of operating cash flow. That is 94.5% of everything the business generated poured back into the ground, in a single year. Its 2026 capex guidance is $220 billion.
          • Alphabet (GOOGL) spent $91.4 billion in 2025, 55.5% of operating cash flow, and guides to $195 billion to $205 billion this year
          • Meta Platforms (META) spent $72.2 billion, 62.4% of operating cash flow, and guides to $125 billion to $145 billion
          • Microsoft spent $115.9 billion in the fiscal year that just ended, against $182.9 billion of operating cash flow. Capex was 34.9% of revenue, up from 18.1% two years earlier. FCF fell to $67.0 billion from $74.1 billion in fiscal 2024, on revenue that grew by more than a third over the same span. Microsoft is running harder and generating less cash. That is what a huge capital cycle does even to the best business in the world.
          • Moody’s (MCO) projects hyperscaler capex of $785 billion in 2026 and close to $1 trillion in 2027, funded in part by roughly $175 billion of debt issuance this year. Where will the money come from?
          • Oracle (ORCL) had fiscal 2026 capex of $55.7 billion, FCF of negative $23.7 billion, capex at 82.6% of revenue, long-term debt up from $76.3 billion to $124.7 billion, and $248 billion of future data-center lease obligations not yet on the balance sheet
          • CoreWeave (CRWV) had $5.13 billion of 2025 revenue, $14.9 billion of capex, negative $7.25 billion of FCF, net debt at 8.1x EBITDA, term loans at 11% to 15%, a weighted-average short-term borrowing rate of 12.3%, and a $1 billion private placement in April 2026 at 9.75%.

          Meta’s Hyperion campus in Louisiana is financed through a special purpose vehicle in which Blue Owl Capital (OWL) holds 80% and Meta holds 20%, funded by $27.294 billion of senior secured notes at a 6.581% coupon maturing in 2049. The noteholders have no pledge on the physical data center. Their credit is Meta’s promise to pay rent starting in 2029, plus a residual value guarantee – that’s $27 billion of debt, secured by a lease, sitting off the balance sheet.

          And like the EU’s finance minister explained two decades ago…

          When it gets serious, you have to lie.

          Microsoft extended server useful lives from three years to four, then to six, adding about $3.7 billion to fiscal 2023 operating income. Alphabet did the same, adding about $3.0 billion. Amazon added about $2.5 billion in 2024. Meta added $2.59 billion in 2025. Oracle added $573 million. Every one of those is a non-cash increase in reported profit produced by an assumption about how long a chip stays useful.

          It’s a lie.

          But not everyone is lying. Effective January 1, 2025, Amazon shortened the useful life of a subset of its servers and networking equipment from six years back to five, citing, in its own 10-K, “the increased pace of technology development, particularly in the area of artificial intelligence and machine learning.” That cost it $1.4 billion of additional depreciation and $1.0 billion of net income.

          Amazon is the operator with the longest and hardest-won experience running data centers at scale, and Amazon is the one telling you the hardware wears out faster than the schedules assume.

          Tell me what you think of today’s Daily Journal: porterstansberrydirect@gmail.com

          Good investing,

          F. Porter Stansberry
          Stevenson, Maryland

          Presented By: The Golden Portfolio


          3 Things To Know Before We Go…

          1. Leopold Aschenbrenner now sits atop the all-time list of trading losses. The Financial Times ranked the 25 largest trading losses in history. Situational Awareness – the AI-focused hedge fund featured above – takes first place with a $35 billion loss in July, roughly 2.5x the next name on the list, Morgan Stanley’s 2007 subprime mortgage blowup. Archegos, Long-Term Capital Management, and JPMorgan’s “London Whale” all rank further down. The fund held $45 billion at the start of July and about $10 billion by the end, after margin calls – lenders demanding more collateral against borrowed money – forced it to sell its entire public stock portfolio to Ken Griffin’s Citadel at below-market prices.

          2. Different presidents, same printing press. M2 money supply has grown from $1.6 trillion at the end of President Jimmy Carter’s term to $23.2 trillion today – a 14x increase across nine administrations of both parties. National debt tells the same story: $1.2 trillion to $39.9 trillion, with $3.7 trillion added in just the first 19 months of the current term. Hard assets like gold, energy, and irreplaceable infrastructure are insurance against the one trend Washington has never broken.

          3. A record year for technology stocks. Rampant enthusiasm for the AI revolution has sparked a record year of fund inflows into technology stocks. So far this year, investors are on track to pour a record $216 billion into technology funds, blowing away all previous records by over $100 billion. This has now become one of Wall Street’s most crowded trades.


          Chart Of The Day… uniQure (QURE)

          Shares of biotech firm uniQure (QURE) have risen more than 100% since being recommended in Porter & Co. Biotechnology for a second time in January – Porter will release his second report since revamping the newsletter on September 5.


          Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

          The post Leopold’s Software Glitch appeared first on Porter & Co..

          • ✇Porter & Co
          • Leopold Was Wrong Porter &#38 · Co.
            Issue#146, Volume#3 His 4-To-1 Leverage Just Made His Convictions Worse Inside Today’s Issue Essay: Leopold Was Wrong GenZ “Invests” In Sports Consumers Tap Out Uncle Sam Keeps Spending Chart Of The Day… BWX Technologies (BWXT) Editor’s note: Today, Porter begins part one of a three-part series on the implosion of Leopold Aschenbrenner’s Situational Awareness fund – and the key reason behind its failure that everyone seems to be missing… We will publish the next Journal this week on Wedne
             

          Leopold Was Wrong

          24 August 2026 at 13:00

          Issue#146, Volume#3

          His 4-To-1 Leverage Just Made His Convictions Worse


          Editor’s note: Today, Porter begins part one of a three-part series on the implosion of Leopold Aschenbrenner’s Situational Awareness fund – and the key reason behind its failure that everyone seems to be missing… We will publish the next Journal this week on Wednesday.


          Leopold Aschenbrenner lost $30 billion (67%) in a month.

          The consensus post-mortem – from The Wall Street Journal to comments on X – is that the young man who ran the Situational Awareness fund used 4-to-1 leverage on concentrated positions and got carried out. While that is true, it does not convey any useful information. Leverage is certainly the reason Leopold lost so much, so quickly. But it is not the reason he lost. Leverage is merely a magnifying glass. It doesn’t pass judgment.

          The reason his fund was doomed was because he’s wrong. And no one, anywhere, has explained why Leopold Aschenbrenner was wrong.

          On the morning of Thursday, July 30, before the opening bell, Aschenbrenner’s Situational Awareness sold its entire public stock portfolio – the long side and the short side together, roughly $16 billion of it – to Ken Griffin’s Citadel in a single block trade.

          That night, Aschenbrenner wrote to his limited partners. Net performance for the month, unaudited: down 67%. Net performance for the year: still up 80%.

          We let you down this month. We came closer to permanent capital impairment than is acceptable to us.

          Six days earlier, on July 24, he had written a different letter. That one reported a 439% net return for the first half of 2026, described the selloff in artificial intelligence (“AI”) stocks as one of the best buying opportunities since early 2025, and invited his investors to wire more money starting August 1. It closed with a postscript:

          At times we call out opportunities that seem like a particularly good time to add funds, if you have been waiting for one.

          Assets that stood near $45 billion at the start of July finished the month around $10 billion, and roughly half of what remains is a single illiquid private stake in Anthropic.

          Leopold is 25 years old. He graduated from Columbia University at 19, as valedictorian. He worked at the FTX Future Fund from February to November of 2022, then joined OpenAI’s Superalignment team, then was fired in April 2024. Two months after the firing, he published a 165-page essay called “Situational Awareness: The Decade Ahead,” raised $225 million from Patrick and John Collison, Nat Friedman and Daniel Gross, and started a hedge fund. He had never managed money before.

          Situational Awareness was constructed to express exactly two convictions.

          1. The physical build-out of AI – the chips, the memory, the power, the data centers, the neoclouds – was the trade of the decade. The fund’s disclosed long positions read like an inventory of the second derivative of the AI boom. Bloom Energy (BE), fuel cells for data centers. Sandisk (SNDK) and Micron Technology (MU), memory. CoreWeave (CRWV) and Nebius Group (NBIS), rented compute. IREN (IREN), Core Scientific, Applied Digital, Riot Platforms, CleanSpark, Bitfarms, Bitdeer – Bitcoin miners converting their substations into AI compute.

          2. Application software was going to be destroyed by AI. Not disrupted. Obliterated.

          Leo explained why on Dwarkesh Patel’s podcast, in June 2024:

          I’m so bearish on the wrapper companies because they’re betting on stagnation. They’re betting that you have these intermediate models and it takes so much schlep to integrate them. I’m really bearish because we’re just going to sonic boom you. We’re going to get the unhobblings. We’re going to get the drop-in remote worker. Your stuff is not going to matter.

          That was the whole thesis. Buy the compute. Short the stuff that runs on the compute.

          By CNBC’s reporting, the short leg included Adobe (ADBE). A 13F does not disclose short stock. It does not disclose swaps. We only know about Adobe because reporters were told… but you can look at the tape and, when you do, it’s clear that Leo was short software in a major way.

          Between the June 30 close and the July 29 close – the last session before the block trade cleared his shorts – the two sides of his portfolio did this.

          The longs:

          • Sandisk: down 55.32%
          • Nebius: down 46.33%
          • Bloom Energy: down 45.90%
          • CoreWeave: down 38.90%
          • Micron: down 35.98%
          • IREN: down 35.91%

          The shorts, over the same 20 sessions:

          • Workday (WDAY): up 37.24%
          • Adobe (ADBE): up 28.49%
          • Intuit (INTU): up 27.64%
          • Salesforce (CRM): up 20.25%
          • Veeva Systems (VEEV): up 17.15%

          Over that same window, the Invesco QQQ Trust fell 10.14% and the SPDR S&P 500 ETF Trust fell 2.32%. Nvidia – the supposed epicenter of the AI trade – fell 5.04%, and finished the full month of July up 0.33%.

          This was not an AI crash.

          The S&P 500 stayed near its record throughout. This was a violent rotation out of the leveraged, capital-hungry, second-derivative end of the AI complex and into the profitable, cash-generating, asset-light end of it. Which is to say: the market rotated out of exactly what he owned and into exactly what he was short.

          Then there is Microsoft (MSFT).

          Microsoft closed at $390.54 on Wednesday, July 29. It closed at $451.10 on Thursday, July 30 – that is a gain of 15.51% in a single session on 110.2 million shares, against a July average of 37.1 million. Yes, Microsoft reported its fiscal Q4 after the close on July 29. But the results were nothing out of the ordinary. Revenue came in at $90.00 billion against an $87.62 billion consensus – a small 2.7% beat. Earnings were $4.74 per share against $4.21. It was a good quarter. Not a historic one. A 2.7% revenue beat does not add roughly $450 billion of market value to the most widely owned company on Earth in six and a half hours.

          The reason Microsoft was up 15% is extremely important. Leo blew up quickly because of leverage. But he failed because he is simply wrong.

          Aschenbrenner’s software thesis rests on a single premise: that a company selling enterprise software is selling the work the software performs. If a model can perform that work, the company is worth nothing.

          That premise is what a very smart 25-year-old engineer believes. It is not what anyone who has ever run a business believes.

          Nobody buys Microsoft because Microsoft writes the best code. They buy Microsoft because Microsoft is the rail everything else runs on. Active Directory is where your employee identities live. Excel is where your board deck’s numbers come from. Teams is where the compliance-recorded conversation happens. Azure holds a FedRAMP High authorization and Department of Defense Impact Level 5 clearance, which means a defense contractor cannot casually swap it out for something cheaper without re-clearing the entire stack with the government.

          Veeva Systems runs the customer relationship management and regulatory document systems of the pharmaceutical industry. Nineteen of the top 20 biopharmaceutical companies use Veeva’s regulatory information management platform. Those systems are validated under GxP – the good-practice quality regulations that govern anything touching a drug – and 21 CFR Part 11, the Food And Drug Administration’s (“FDA”) rule for electronic records and signatures. Every major release is formally qualified. When an FDA inspector arrives, the audit trail in that system is the company’s defense.

          You cannot replace that with a model that is very good at writing code. You would have to re-validate a decade of regulated records, in front of a regulator, on a system with no track record, to save a fee that rounds to nothing compared with the cost of building a new drug.

          How small a fee? Veeva’s licensing runs somewhere between roughly $1,800 and $6,600 per sales representative per year. A fully loaded pharmaceutical sales rep costs the employer between $134,000 and $219,000 a year. The software is 1% to 5% of the cost of the person using it.

          Microsoft raised the price of a Microsoft 365 E3 seat from $36 to $39 per user per month on July 1 of this year, and E5 from $57 to $60. Add Copilot at $30 and a fully loaded E5 seat costs $1,080 a year. Against a knowledge worker costing $120,000 all-in, that is roughly 1% of the employee.

          This is the part the compute maximalists cannot see. These companies are not selling labor. They are selling the rails on which labor runs, at a price so far below the value created that the buyer never bothers to negotiate hard, and with switching costs so high that the buyer could not leave even if he wanted to.

          Do people try to leave? Constantly. And they almost always fail. (Ask me how I know!)

          Panorama Consulting Group tracked studies of enterprise resource planning replacements and found average cost overruns at 189% across industries. Gartner projects that by 2027, more than 70% of recently implemented ERP (enterprise resource planning) initiatives will fail to fully meet their original business goals. Ripping out a core enterprise system is one of the most reliably disastrous things a large company can attempt, and it was true before anyone had heard of a transformer model.

          The incumbents are not being disintermediated by artificial intelligence. They are selling it!

          Next, I’ll explain how Aschenbrenner went terribly wrong. He thought AI would eat the applications. Instead, the applications are selling AI as an upsell on top of a subscription the customer cannot afford to cancel.

          Tell me what you think of today’s Daily Journal: porterstansberrydirect@gmail.com

          Good investing,

          F. Porter Stansberry
          Stevenson, Maryland

          Presented By: Tuttle Capital Management


          3 Things To Know Before We Go…

          1. More than half of young investors have pulled money out of their portfolios to bet on sports. Betterment, an automated investing platform, surveyed 1,000 American retail investors in the spring. Among Gen Z respondents – born between 1997 and 2007 – 52% said they redirected money originally earmarked for investing into sports wagers over the past year, and 26% called sports betting a deliberate part of their long-term financial plan. What could go wrong?

          2. American consumers are tapping the brakes. July retail sales fell 0.6% – the steepest monthly drop since May 2025 and well below the +0.1% consensus. The weakness was broad across non-store retailers, including Amazon (AMZN) where sales fell 2.2%, the second-largest decline since July 2021, while auto and parts sales dropped 1.8%. Most telling, control-group sales – the cleanest read on underlying demand that feeds directly into GDP – plunged 0.4%, the worst since January 2025. A stretched consumer is starting to show up in the data.

          3. The federal government just posted its largest July deficit on record. The U.S. Treasury reported a $432 billion shortfall for the month – $334 billion of revenue versus $766 billion of spending. Interest on the debt cost $118 billion in July alone, $26 billion more than a year earlier, bringing the fiscal-year total to $1.17 trillion. That is more than the government spends on the entire military, and it is now running even with Medicare. Ten months into fiscal 2026, the deficit stands at $1.8 trillion. Every quarter-point move higher in Treasury yields adds tens of billions to that interest bill as old low-rate debt matures and gets refinanced. Washington cannot afford higher rates.


          Chart Of The Day… BWX Technologies (BWXT)

          Nuclear-parts provider BWX Technologies (BWXT) has tripled from our 2022 recommendation in Complete Investor – providing the power that powers the AI buildout.


          The post Leopold Was Wrong appeared first on Porter & Co..

          • ✇Porter & Co
          • Trade Alert: Adding To Cellebrite Position Porter &#38 · Co.
            Today we’re recommending buying additional shares of digital-forensics software platform Cellebrite (Nasdaq: CLBT) via the following trade recommendation: Action To Take: Buy 200 shares of Cellebrite (Nasdaq: CLBT) up to $13 per share – the recent price was $11.26 Note that this recommendation comes on top of the existing 400 shares of Cellebrite we’ve previously recommended buying, bringing our total recommended position size to 600 shares. As mentioned in last week’s update, we believe Ce
             

          Trade Alert: Adding To Cellebrite Position

          24 August 2026 at 10:12

          Today we’re recommending buying additional shares of digital-forensics software platform Cellebrite (Nasdaq: CLBT) via the following trade recommendation:

          Action To Take: Buy 200 shares of Cellebrite (Nasdaq: CLBT) up to $13 per share – the recent price was $11.26

          Note that this recommendation comes on top of the existing 400 shares of Cellebrite we’ve previously recommended buying, bringing our total recommended position size to 600 shares.

          As mentioned in last week’s update, we believe Cellebrite shares are deeply undervalued. We view the 30% drop following its Q2 earnings report as an extreme overreaction to a minor hiccup in its sales growth rate. And after last week’s expiration of our covered-call position on shares of LandBridge (NYSE: LB), which resulted in an additional $7,500 in available cash, we’re recommending reinvesting a portion of this freed-up cash into today’s new trade.

          Good investing,

          Ross Hendricks
          Porter & Co.

          The post Trade Alert: Adding To Cellebrite Position appeared first on Porter & Co..

          ❌