High interest rates, rising energy costs, and a more expensive AI buildout are creating new risks for stocks. Here's how these headwinds reinforce one another—and what investors can do to protect their portfolios.
It was January 2000. AOL had just announced it was buying Time Warner in what was then the biggest merger in history. Fourteen dot-com companies had bought Super Bowl ads, one of them starring a sock puppet that sold dog food.
The US economy was growing at one of its fastest paces ever; GDP was up nearly 5% the year before— and that’s real growth, before adding inflation, which itself was just 1.4%.
Unemployment was 4%, the lowest in thirty years. And there was no other country on the planet that could come close to rivaling America’s dominance.
Best of all, the federal government was running a surplus… a real one. It was so strong that, even excluding the Social Security surplus, the government took in $86 billion more than it spent.
So the Treasury didn’t need to borrow any money. Naturally it still held bond auctions, because when you issue the global reserve currency, you have to give investors a safe place to park their money. But Treasury was retiring more debt than it issued, and even started buying its own bonds back early.
And after wondering what “the meaning of the word is is”,Bill Clinton bragged that the country was “on track to pay down nearly $300 billion in debt” by the end of the year.
And in the middle of all that, the 10-year Treasury yield hit 6.79%.
In other words, investors wanted a 6.79% annual return to hold extremely safe US government bonds… at a moment when America was on top of the world and the government’s finances were in their best shape in decades.
That interest rate was not a crisis. After all, the government didn’t have to borrow to keep the lights on or the military funded or Social Security solvent. So they didn’t really care.
The Treasury’s interest bill was shrinking as a share of tax revenue every single year.
Imagine that.
Fast forward to earlier this week, and after a hot inflation report and with oil back above $100, the same 10-year yield briefly crossed 5%.
The reaction was instant panic.
Imagine being able to go back in time for a moment… back to January 2000. Imagine talking to an economist back then. You explain that you’re from the future, and that in 2026, the national debt is $40 trillion and growing faster than the economy. The foreign central banks that used to buy America’s debt are dumping Treasuries and buying gold instead.
You explain that there are wars in Ukraine and Iran, socialism is creeping back into American politics, and Congress can barely function.
You then ask the economist from January 2000 to guess where they think the 10-year yield would be, given all of that bad news.
They’d probably guess 10%, maybe 12%, and they’d be amazed to hear it only just crossed 5%.
So why did it take so long?
Because after the 2008 financial crisis, the Fed cut rates to zero… and left them there for seven years. There were a few ceremonial hikes, but when COVID arrived, the Fed slashed rates right back to zero.
It was able to do this because the Fed conjured trillions of dollars out of thin air… and used that money to buy bonds and suppress yields.
The 10-year was so low, in fact, that the federal government could issue those notes at less than 0.5%.
For thirteen years money was essentially free, and an entire generation came to believe that was normal. It wasn’t, and that era is clearly over.
Think about what an opportunity that was: when you can borrow at 0.5%, $2 trillion in debt costs just $10 billion a year. Investing that money at even a measly 1% means the government would be making money on its debt.
A 1% hurdle rate is not particularly high. But Congress couldn’t manage even that much.
Despite racking up tens of trillions in debt, there’s realistically nothing to show for all of that money: the national debt has quadrupled since the financial crisis, while the economy has only doubled.
Now, each year, much of the national debt matures, and the Treasury doesn’t have the money to pay it back. So they have to issue new debt to repay the old debt.
Problem is, the new debt is issued at much higher rates. They were paying 0.5% on the old debt. The new yield of 5% is TEN times the interest on the same amount of debt.
And with an average maturity of about six years, most of the $40 trillion rolls over within just a few years… which means before long the annual interest bill will reach $2 trillion per year.
Add nearly $3 trillion for Social Security and Medicare, and that’s the vast majority of tax revenue.
Literally everything else, including the military, roads, and light bill at the White House, is funded with more debt.
In 2000, the government could shrug at a 6.79% yield because it was paying debt down. Today everyone’s panicking at 5% because Congress borrows $2 trillion a year and can’t stop.
So, is Congress going to suddenly find its inner fiscal discipline?
I’m not holding my breath.
That leaves exactly one way to get the 10-year back down, and it’s the same way the Fed did it back in 2020: conjure more money out of thin air and make capital infinite.
And as the world discovered shortly after in 2021 and 2022, the consequence of that policy is inflation.
P.S. In 2000, a 6.79% Treasury with 1.4% inflation was a fantastic deal. Today’s 5% Treasury with the inflation that’s coming is a losing one.
Real assets are where you come out ahead: gold, energy, and industrial metals rise when the dollar falls. The profitable, debt-free companies that produce them are what we research in Schiff Sovereign’s Strategic Assets.
On Sunday afternoon, the power went out at ExxonMobil’s refinery in Channahon, Illinois, a southwest suburb of Chicago.
Oil refineries run at tremendous heat and pressure, so whenever the power goes out, all that heat and pressure has to go somewhere. It’s basic physics. Hence why the plant burned it off through the flare stacks, with black smoke visible for miles.
The power came back around 7 p.m., but the plant stayed down, and as of Monday ExxonMobil still hadn’t said when it would restart, likely up to a week.
Bear in mind this is a plant that processes about 275,000 barrels of crude a day— close to 10% of the region’s fuel supply.
But that’s not what caused the highest diesel prices ever.
Even before this refinery was taken out of commission, the national average price of diesel went above $6 a gallon last week for the first time ever. Filling up a long-haul semi truck now costs more than $1,000.
It’s important to note that a barrel of crude oil is almost useless until somebody turns it into something. A refinery cooks the crude and breaks it apart into gasoline, diesel, jet fuel, heating oil, the raw material for plastics, etc.
Everyone knows about the squeeze on oil due to the war with Iran. But the shortage of REFINERIES is another issue.
Sure, the wars have taken a toll on refineries and other fuel plants. Iran bombed Bahrain’s only refinery, shut ever since. It also wrecked half of Shell’s Pearl GTL in Qatar, the world’s largest plant for turning natural gas into diesel, jet fuel and lubricants. Ukrainian drones, meanwhile, have cut Russia’s refining by roughly a third.
And the rest of the world’s refineries can’t pick up the slack.
US refineries are already running at almost 98% of capacity. There’s no spare refining capacity, and that’s because governments have treated refining as the enemy of humanity for the past decade.
For example, ten years ago Britain had six refineries. Then the UK government announced a ban on new gasoline and diesel cars and piled punitive taxes specifically on refineries, and today Britain is down to four.
I guess the “Just Stop Oil” fanatics are happy now. They actually declared victory last year and hung up their hi-vis (oil-based) vests, and quit (oil-based) gluing themselves to things, because “no new oil” had become official government policy in the UK.
California, meanwhile, imposed a new penalty tax on refinery margins, and then passed climate change regulations for refineries that are virtually impossible to achieve.
Unsurprisingly, in the past year, California lost two refineries: Phillips 66’s in Los Angeles and Valero’s in Benicia near San Francisco. That’s 17% of California’s refining capacity.
Then Newsom panicked and changed his tune, realizing that California fuel prices would surge. He suddenly promised to “work closely with refiners.” He directed his own energy commission to pause the punitive refinery tax for five years. He even pushed legislators to consider paying hundreds of millions of dollars to Valero to keep their plant open.
Too little, too late. The refiners left, or idled their plants. You can only bite the hand that feeds so many times before they take action.
But of course, everyone will pay for Newsom’s idiocy, because diesel moves everything. So much of American imports arrive at California ports (like the Port of Long Beach), and trucks haul it across the country from there. Trains do the rest.
And nearly every big truck and freight train runs on diesel, which is now a lot more expensive in California. So the cost of Newsom’s lunacy is paid by every consumer.
Harvest is starting across the Midwest right now, and everything from tractors to grain dryers burns fuel. Phosphate (another critical fertilizer ingredient) is mined and hauled with diesel.
So the farmer pays $6 a gallon, the trucker pays $6 a gallon… and consumers reimburse these costs in the form of higher prices.
And let’s not forget, winter is coming.
Heating oil is diesel by another name (it comes out of the same refinery), and about 5 million American homes heat with it, more than 80% of them in the Northeast. One Gulf oil executive warned last week of “a very difficult winter coming in Northwest Europe. This is only the beginning.”
Bottom line, the power outage at Channahon is a problem. But it’s a small problem compared to the larger war on refineries.
With the spare refineries gone, even the slightest issue at remaining refineries now shows up in the price of diesel, food and everything else that moves on a truck.
Unexpected disruptions from war and power outages are one thing.
But governments deliberately villainizing refiners and chasing them out of town, for the crime of creating the energy the world desperately relies on, is another.
Their green policies and ESG mandates also helped drive a decade of underinvestment in the physical things civilization runs on: ships, mines, oil fields, smelters… and refineries.
Now the world is in the midst of a destructive war. When there is no spare capacity, every disruption has to be resolved by price, and the companies that own the scarce, strategic assets collect the difference.
And owning a piece of those companies yourself is the best way to protect yourself from higher prices and inflation.
P.S. That’s the whole point of Schiff Sovereign’s investment research newsletter, Strategic Assets: profitable, low-debt companies that own or move real things, bought while they’re still cheap.
Two oil tanker owners we featured when nobody wanted them are up more than 180% and 130%— one of them runs the ships that haul diesel— and our palm oil grower is up nearly 140%.
Last week, Treasury Secretary Scott Bessent sat down for a fireside chat at Southern Methodist University in Dallas and told the room what the plan is for the national debt.
“We don’t have a revenue problem,” he said. “We have a spending problem.” Contain the spending, add 3% growth, and America can “grow our way out of this.”
That’s a nice idea… and, it’s possible. The key part there is the spending freeze: arrest the growth in federal spending, and the deficit will eventually melt away.
The problem, of course, is that Congress won’t even cut obvious fraud. So I don’t think taxpayers should hold their breath for sudden fiscal responsibility.
The growth side of his approach is feasible. But what does “grow our way out” of the debt actually mean?
The national debt is now a little over $40 trillion. Meanwhile the entire US economy— everything produced by every business and every worker in the country over a full year— is about $32.5 trillion.
This means the debt is 123% of GDP, i.e. the all-important debt-to-GDP ratio is 123%.
That ratio is the key indicator that bond investors watch. And it’s the number Secretary Bessent is talking about when he says the US can grow its way out of debt.
The whole point is to bring that percentage down, from 123% today to something more like 80% or 90%.
Notice what he did NOT say. He didn’t say the debt would shrink. He didn’t say the deficit would go away. Growing your way out means the debt keeps getting bigger… it just grows at a slower pace, while the economy grows at a much more rapid pace.
Specifically, the US national debt has been growing at an average 6.7% per year over the past few years… which means ‘growing our way out’ will require the US economy to expand by at LEAST 7% per year, just to make a dent in the debt-to-GDP ratio.
Now go back to Bessent’s number: he’s talking about 3% growth.
And when he says 3%, he means real growth, i.e. the economy producing 3% more goods and services than it did the year before. That means more cars, more houses, more software, more oil… more actual stuff.
But we just established that the economy will require 7% growth in order to fix the debt challenge.
So where, exactly, is the other 4% supposed to come from?
It comes from inflation. In short the economy produces 3% more stuff, but the stuff costs 4% more. In total that gets you to more or less 7% GDP growth, while the debt increases by 6.7%.
And with that, you have a tiny improvement to America’s dismal debt-to-GDP ratio.
This is already the path that they’re on; in the last year, America’s total (i.e. nominal) GDP growth was 6.5%. Of that, only 2% was real growth, i.e. the production of more goods and services.
The rest, about 4.5%, was from rising prices.
So “growing our way out” is really just a polite way of saying inflation. And the government is effectively telegraphing a 4% inflation target. As it happens, that’s about where inflation already is right now.
In other words, the plan is to make everything else more expensive faster than the debt grows, and to call that a fix.
Four percent a year doesn’t sound like much. But it compounds, and at that rate a dollar loses about a third of its purchasing power in ten years.
The solution is to own the stuff they can’t conjure out of thin air.
A government can print money by the trillion, but it can’t print an ounce of gold or a barrel of oil, or anything else that’s real or critical to the economy.
That’s why real assets tend to hold their value when the currency is losing value… and why the businesses that produce those assets— gold miners, energy companies, copper producers, chip makers, etc.— often do spectacularly well.
P.S. Real assets are the whole premise of Schiff Sovereign’s investment research newsletter, Strategic Assets: profitable, well-run companies that produce the things a government can’t print, researched while they’re still cheap.
We locked in gains of more than 10x on a small silver producer we featured last year, and a gold producer has gone up 5x yet still trades cheaper against its earnings than the day we wrote it up. Two oil tanker owners we covered when nobody wanted them are up more than 150% and 110%.
In July, the Canadian uranium miner Cameco stopped producing at its mine in northern Saskatchewan (known as ‘Cigar Lake’) for two weeks.
Cigar Lake itself was fine, nothing was wrong with the mine. The problem was their sulfuric acid plant— a crucial ingredient in processing uranium ore— broke down.
Normally they would have just bought sulfuric acid from somewhere else while they fixed their company-owned acid plant. But this year that’s not so easy.
About half the world’s seaborne sulfur moves through the Strait of Hormuz, and since the war with Iran began, those shipments have almost completely stopped. China, the world’s largest exporter of sulfuric acid, restricted its own exports in May to make sure they had enough.
So a simple mechanical problem at an acid plant caused a two-week shutdown of the world’s largest uranium mine.
Two weeks is a really long time for a huge mine like Cigar Lake to have an unscheduled shutdown; that’s because uranium is already in critical supply— there simply isn’t enough uranium being produced right now to keep up with demand.
The math is easy: miners produced roughly 155 million pounds of uranium in year. Reactors burn about 185 million pounds. So there’s already a significant deficit.
For the past several years, the deficit between uranium production versus reactor demand was covered by stockpiles that had been building up over decades. So the nuclear industry effectively burned through its uranium ‘savings’.
But those stockpiles of uranium are now basically depleted… which means that nuclear power companies will need to rely on uranium production in order to meet their needs.
This is a problem… and one that we can quantify.
Because uranium is literally THE most important resource for a nuclear reactor, the reactor companies tend to line up their uranium supply needs years and years in advance through forward contracts and term agreements.
There’s no black magic here— it’s a pretty predictable quantity. A 2GW nuclear plant, for example, already knows exactly how much electrical capacity they have, so they know how much fuel they need to serve their customers… hence they can forecast their future uranium needs.
For this year at least, US nuclear power companies have more or less the amount of uranium that they anticipate needing. But next year they’ll be in a deficit… and one that grows each year.
By 2030, US nuclear power companies will be short 40% of their anticipated uranium needs. By 2033, they’ll be short 91%. Basically all of it.
Big deal, right? Existing uranium producers can simply mine more.
But that’s not really happening… at least, not at current prices.
Kazatomprom (based in Kazakhstan) is the largest uranium miner in the world. And their management is deliberately pulling back on production right now.
The company believes that it’s simply not worth mining and selling uranium at the current price. Why bother producing at your full potential now when they KNOW the price is going to rise in the future, hence they make a LOT more money in the future if they mine less now.
OK well, the big shortage in the 2030s is still a few years away. So the industry has time to start more mines and bring new uranium production online.
Well, that’s easier said than done.
A company called NexGen Energy discovered a major uranium deposit in Saskatchewan back in 2014. They finally got their construction license this March, started building in August, and expect their first ore in 2030.
In other words, SIXTEEN years from discovery to production— and that’s about average for the industry.
You can’t just turn on uranium production like a light switch; it takes years and years to make most things happen in business, and uranium mining is no different.
This is common across many real assets— there has been years of underinvestment. Very few new uranium mines. Very little oil & gas exploration. Not enough new shipyards, refineries, smelters, etc.
It takes several years… plus a lot of risk capital… to discover a new resource deposit and bring a mine to life. Years.
Demand can grow much more quickly. Just look at the increase in electricity demand (thanks in large part to data centers). When electricity demand surges, but the supply of the fuel required to generate electricity is stagnant, the end result is higher prices.
And not just higher electricity prices— higher prices for the fuel as well, i.e. higher natural gas prices, higher uranium prices, and even higher coal prices.
(Coal is especially interesting— it was basically chased out of town. NO ONE wanted to invest in a new coal mine thanks to Greta Thunberg. Yet the International Energy Agency now expects coal-fired power generation to rise this year to make up for energy imbalances. Stagnant supply meets rising demand.)
That’s tough news for anyone with an electricity bill. But you can also be on the other side of it and make money from this trend.
When supply and demand is so fundamentally unbalanced, the companies that produce these scarce resources tend to perform extremely well.
This is the primary investment ethos for our investment research newsletter, Strategic Assets.
We look for the most critical resources that the economy runs on; we find sectors where there has been chronic underinvestment and focus on undervalued yet successful companies with great management and balance sheets.
Energy has been good to us. Two oil tanker owners we featured when nobody wanted them are up more than 150% and 110%.
A small South American oil producer we featured last month has no debt and sells every barrel at the wellhead to one of the largest oil companies on earth— so shipping is someone else’s problem. A typical new well takes years to pay for itself. This company’s fastest did it in 37 days.
It’s so simple, how could no one have thought of this before?
The man currently polling in second place to become the next President of France has put forward an ingenious solution to tackling France’s national debt, currently standing at around 117% of the country’s GDP.
Jean-Luc Mélenchon says, “All we have to do is take the 18% held by the Bank of France and chuck it in the fire.”
This is the guy who has a real shot at running the second-largest economy in the eurozone, and he’s telling voters that roughly €636 billion of what their government owes can simply be erased.
And the voters like the sound of it. Of course they do, who doesn’t love getting something for nothing?
Quick economics lesson for the brilliant man who wants to lead France: the Bank of France bought those bonds with euros it created for the purpose… the European Central Bank’s own explainer says buying bonds “creates money in the banking system.”
Normally those euros come back out of circulation as the debt gets repaid. Mélenchon’s plan skips that part: the government ‘throws the debt in the fire’ and doesn’t pay it back. So the central bank eats the loss… meaning that the €636 billion conjured out of nothing stays in the system.
This creates inflation, plain and simple.
Goods and services cannot be created out of nothing. Euros can. So when there’s suddenly more money in the system relative to the same amount of goods and services, the end result is inflation.
The other obvious implications is that France would still owe the rest of its debt… and those lenders will have seen that France is willing to default. I wonder what that would do to French bond yields?
Or maybe they’ll rest easy with Mélenchon’s assurance that “I’m not going after private creditors, not at this step in any case.”
Why do French voters even care about the national debt? Because they’ve been feeling the consequences of idiotic fiscal policy for years.
Interest alone costs the French government more than its entire defense budget. There’s no taxing their way out, either: the French are already the second-most-taxed people in the developed world, at about 44% of GDP.
So every fix takes some benefit away from taxpayers. Last year’s plan canceled two public holidays, froze pensions, and cut civil-service jobs… and the prime minister who proposed the solutions was thrown out.
The plan before that raised the retirement age from 62 to 64 brought the biggest protests France had seen in decades; that plan has now been suspended to keep the current government alive.
Meanwhile, growth was less than 1% last year, and unemployment is at its highest since 2020.
And here comes Mélenchon with a plan that costs nobody anything: delete a portion of the debt and go back to spending as if everything is OK.
However dumb the solution, at least the French are talking about the problem.
The US government crossed $40 trillion in debt last month. That’s roughly 123% of GDP, worse than France.
America gets away with it, for now, because the dollar is still the world’s reserve currency. Central banks hold a lot of their strategic financial reserves in US Treasury bonds, so Congress has always had a line of foreigners waiting to lend it money no matter how large the deficit.
But that line of foreigners is now getting shorter. Foreign holdings of Treasuries fell by $72 billion in June alone, China’s are at their lowest since 2008, and so far this year foreigners have bought just 7% of the new debt the US government issued.
The reasons aren’t a mystery: a dysfunctional government that can’t even pass a budget or eliminate fraud from its spending, while increasingly weaponizing access to the US dollar system.
When the foreign buyers stop showing up, America finds itself with France’s problem. Automatic cuts to Social Security are only six years away. Interest on the debt is already larger than the defense budget.
Extreme government spending is already pushing inflation higher… and socialists are everywhere now promising to spend even more.
These people genuinely believe that money is something you can conjure out of thin air with no consequence.
But whether they cancel the debt, or simply continue to ignore it, the consequence ultimately comes back to inflation.
That’s because conjuring money out of thin air, or borrowing from future generations to spend today, doesn’t produce one more barrel of oil, one more bushel of wheat, or one more pound of copper. It just produces more euros and dollars.
America has been here before.
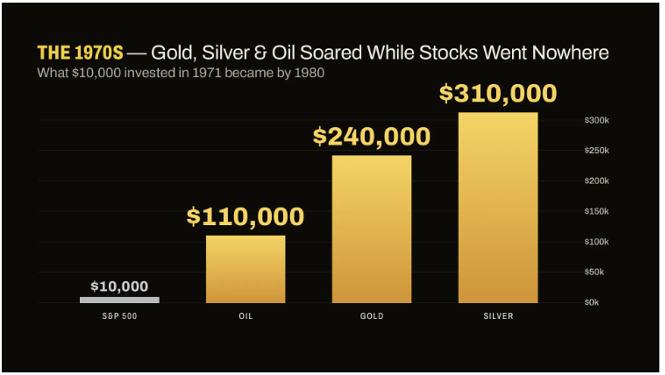
Through the 1970s the US government ran deficits for Vietnam AND a historic expansion of welfare spending… then cut the dollar’s last link to gold in 1971. They created new money to cover the difference.
Consumer prices doubled over the decade, and the Dow finished 1979 where it started 1970, which after inflation was a loss of about half in real terms.
Meanwhile, gold went from $35 an ounce to $850. And oil went from about $3.40 a barrel to nearly $30. The world’s most important (and scarce) resources not only held their value, but they dominated. And the companies that produced them did far better.
Over roughly the same stretch, Barron’s index of gold mining stocks rose more than 1,200% while the S&P 500 managed 43%.
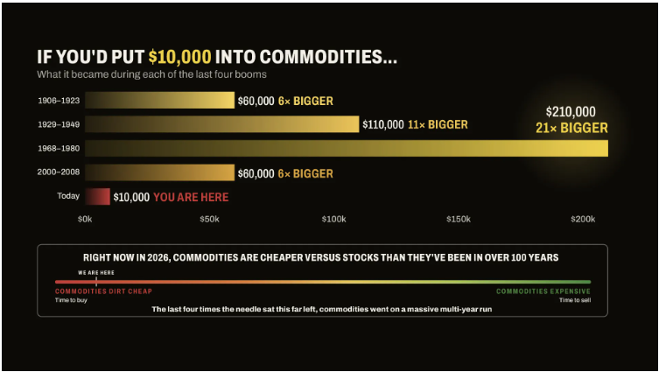
The new money has to go somewhere, and it flows into whatever the government cannot create more of.
Today, a lot of the companies that produce those real assets like metals, energy, food, and the ships that carry them, are still cheap.
We find them for subscribers of our investment research newsletter, Strategic Assets.
Gold and silver moved first, as central banks started diversifying out of the dollar. A small silver producer we featured in April 2025 rose more than 10x in ten months. A gold producer has gone up 5x, yet it’s earning money so fast that the stock is cheaper against its earnings today than the day we wrote it up. It pays a dividend, too.
Now the rest is showing life. A zinc producer we featured is up more than 150% in under a year. A tin miner is up more than 230% and trading at all-time highs. Two oil tanker owners we bought when nobody wanted them are up more than 150% and 110%, and one just reported the best quarter in its history.
For years, near-zero rates pushed investors into stocks. Today, cash and bonds offer attractive returns again—changing the market's risk/reward setup and giving investors more reason to be selective. Here's what it means for your portfolio.
The market could pull back 20% from current levels. Plus, Bessent's bond move… Sectors to buy (and avoid) as long-term rates rise… Offshore oil stocks… How to manage big winners… And one of the best business models in the world.
The latest nonfarm payrolls report lands Friday, September 4 at 8:30 a.m. ET, and it’s the biggest, most volatility-inducing number of the month. Consensus is looking for a gain of around +55,000 after July actually lost 23,000 jobs. But our August jobs report preview says the crowd has it wrong.
I’m going to tell you the same thing I told our room on this morning’s live show: the number isn’t the story. Risk is already repricing where the real money lives — and it’s not in the VIX. It’s in the bond market.
I spent 28 years making markets, first on the floor of the CBOE and then trading bonds from 2003 to 2012. And the yield curve was always my first tell for the direction of the whole stock market. Right now, that tell is flashing, most traders are watching the wrong gauge, and Friday’s print is the catalyst that decides which way this thing air-pockets.
Let me walk you through it.
Key Numbers to Know Before Friday
Report
August 2026 nonfarm payrolls (jobs report)
Release
Friday, September 4, 2026 — 8:30 a.m. ET (7:30 a.m. CT)
Consensus
~ +55,000 jobs (estimates run from roughly −25K to +140K)
Prior (July)
−23,000
Unemployment rate
Expected to hold near 4.1%–4.2%
VIX
~15–16 — near its lowest levels all year
MOVE index (bond vol)
~78 and rising, up from ~70 last week
10-year Treasury yield
~4.8%
Fed funds rate
3.50%–3.75% — markets pricing ~65% odds of a hike in September
What Time Is the August 2026 Jobs Report Released?
The Bureau of Labor Statistics releases the August employment report on Friday, September 4, 2026, at 8:30 a.m. ET (7:30 a.m. CT). It’s the single biggest catalyst of the month — the one number that moves the dollar, the bond market, and the stock market in the same breath, usually inside the first few seconds.
What Is the Forecast for August Nonfarm Payrolls?
Consensus is centered around a gain of +55,000, with the unemployment rate expected to hold near 4.1%. But be honest about the spread: the estimates run all the way from a 25,000 decline to a gain of 140,000.
When the pros can’t agree inside a 165,000-job range, that’s your first tell. This is a convexity setup, not a coin flip. The wings are priced for a big move — up or down — because there’s simply too much uncertainty for this market to sit still. Nobody actually knows what prints, which means the market is going to react, hard, to whatever does.
MOVE Index vs. VIX: The Number That Matters
Here’s the part almost nobody is talking about.
For the last year, the crowd has watched the VIX — the “fear gauge” for the S&P. Fine. But the VIX is sitting down in the dumps around 15, near its lowest levels of the entire year, while the market has been quietly selling off. That combination — market down, VIX asleep — usually doesn’t happen. It’s a tell that traders have gotten too comfortable with risk.
So don’t watch the VIX right now. Watch the MOVE index.
The MOVE (it’s a Bank of America product) is to bonds what the VIX is to the S&P — it measures volatility in the Treasury market. And while the VIX naps, the MOVE has climbed to roughly 78, up from around 70 last week. Bond volatility is rising while stock volatility pretends everything’s fine. When those two disagree, you don’t fight the bonds. The bond market is bigger than the equity market, and it’s usually right first.
Why is bond vol waking up? The 10-year yield is pushing 4.8% and the 30-year is at its highest in a long while. The Treasury even stepped in to buy the back end of the curve to try to force those rates down — but you can’t fight the free markets for more than a day or two. That’s the real reason the QQQ, the IWM and the S&P have been leaking lower. It isn’t a VIX story. It’s a bond-volatility story, and the MOVE is your first tell. If it bounces again before Friday, this market goes into the number under serious pressure.
Will the Fed Raise Rates in September?
Now layer the jobs number on top of that.
For most of 2024 and 2025, the trade was simple: weak jobs → the Fed cuts → stocks rally. “Bad news is good news.” That trade is dead right now, and here’s why.
Sticky inflation never went back in the box — the Fed’s preferred gauge is still running well above its 2% target, and with U.S.–Iran tensions heating up and tankers being hit exiting the Strait of Hormuz, oil is catching a hard bid. That’s more inflation, not less. At Jackson Hole, Fed Chair Kevin Warsh made it about as clear as a central banker gets that prices worry him more than a soft patch in hiring. The July meeting was a 9–3 hold, and all three dissenters wanted to raise rates. After Warsh spoke, fed funds futures flipped to roughly two-in-three odds of a September hike.
I’ll say it plainly, same as I said it live: I strongly believe the Fed raises rates at its September meeting.
So flip your logic before Friday:
A hot number (think +100K or more) tells Warsh the labor market can take a hike — that’s the hawkish outcome, and it’s a headwind for stocks, a tailwind for the dollar and short-term yields.
A weak number is what takes hike risk off the table — and that’s the one the equity crowd would actually cheer.
Read that twice, because it’s backwards from what you’ve been conditioned to do. This is my First Law in action: money drives markets. Not the headline, not the pundit spin — the repricing of rate expectations. Ask yourself which game you’re playing before 8:30.
Why the VIX Looks Too Cheap Into the August Jobs Report
Put it all together and the VIX being this low makes no sense. We’re walking into nonfarm payrolls — the biggest catalyst of the month — in a September that’s historically one of the most volatile stretches of the year, with bond vol climbing, yields near the highs and inflation a live concern. And the crowd is treating protection like it’s worthless.
That’s exactly when volatility gets mispriced. Stocks don’t like to hang around big round numbers — right now the Nasdaq is sitting right on its 100-day moving average, and markets rarely just drift there. They give a level a kiss and then either bounce or air-pocket straight through it. Into a number with this much uncertainty, that’s a move waiting to happen — which is why watching and respecting volatility here matters far more than the crowd thinks.
And don’t let last week’s Nvidia headline lull you either. Everyone circled the 89% implied year-over-year revenue growth and cheered — but a big share of that profit came from Nvidia’s own investments in AI companies that turn around and buy its chips. That’s circular financing, and it’s part of why the rally underneath is more fragile than the tape looks.
What the Unemployment Rate Isn’t Telling You About the Jobs Report
July’s rate “fell” to 4.1%, and you’ll see that spun as strength. It isn’t. It dropped for the wrong reason — the labor force shrank by more than a quarter-million people and the participation rate slid to 61.4%, the lowest outside the Covid shock since the mid-1970s.
When the workforce is shrinking, the number of jobs needed just to holdunemployment steady falls too. So, a small payroll print — even a slightly negative one — no longer automatically means the economy is cracking. This is my Third Law: nothing is cheap or expensive on its own. You have to know why a number moved before you trade it.
What the BLS Benchmark Revision Means for the Jobs Report
Two weeks ago the BLS dropped its preliminary benchmark revision — the annual re-basing of payrolls against actual tax records. The economy had 79,000 fewer jobs in the year through March 2026 than first reported. That’s 0.1%. A rounding error — and a fraction of last year’s roughly −911,000 revision that had half the internet screaming cover-up.
But don’t stop at the headline. Look at where the jobs moved, because the tape can’t hide. The biggest cuts hit retail trade (−154,600), private education and health (−96,000), wholesale trade (−86,200) and manufacturing (−67,000). The upward revisions went to transportation and warehousing (+135,100), government (+99,000), information (+87,000) and financial activities (+85,000). That’s not random. That’s the goods-and-retail economy bleeding while logistics, government and information hold the line. Follow the money and the picture gets a lot clearer than the one-line summary. Second Law: the tape can’t hide
How to Think About Trading the Jobs Report
I’m not handing you a ticket to punch — this is the setup, not a recommendation. But here’s how I’m framing Friday.
The edge on an event like this is almost never in guessing the number. It’s in watching the right gauge and understanding the reaction. So watch bonds. For those with access to futures, the ladder is your read: ZN (10-year), ZB (30-year), UB (ultra), ZF (5-year), ZT (2-year) — or just follow TLT and the MOVE index. If yields start coming down and the MOVE settles, the market can rally. If the MOVE bounces and TLT gets crushed, that’s very bearish for stocks.
And whatever you do, my Fourth and Fifth Laws carry the day on an event like this: decide your risk before you enter, not after the number prints — and survive first. Size it so a whipsaw can’t take you out of the game.
What the Jobs Report Means for the September Fed Rate Decision
This report doesn’t land in a vacuum. It’s the first of two big inputs before the Fed’s September meeting, with the August CPI report following the week after. Neither is a formula that spits out a decision — they’re evidence, and Warsh has told us he’s reading it through an inflation lens. A firm payroll number plus another sticky inflation print keeps the September hike squarely on the table. A clearly weak jobs report is what could talk the committee back toward patience.
FAQ
What time is the August 2026 jobs report?
Friday, September 4, 2026, at 8:30 a.m. ET (7:30 a.m. CT), from the U.S. Bureau of Labor Statistics.
Will the Fed raise rates in September 2026?
It’s a live debate, and it’s leaning hawkish. After Chair Warsh’s Jackson Hole speech, fed funds futures moved to roughly 65% odds of a quarter-point hike — a sharp shift from the pause markets had expected. Friday’s payrolls and the following week’s CPI will shape the final call.
Why is a strong jobs report bad for stocks right now?
Because inflation is still above target and the Fed is leaning toward hiking. A strong labor market gives the Fed cover to raise rates, which pressures equities and lifts the dollar and yields. The old “weak-jobs-means-cuts” trade is inverted for now.
What is the MOVE index and why does it matter for the jobs report?
The MOVE index measures expected volatility in the U.S. Treasury market — it’s the bond market’s version of the VIX. With bond volatility rising while the VIX stays low, the MOVE is the more honest read on risk heading into a market-moving number like nonfarm payrolls.
What was the July 2026 jobs report number?
Nonfarm payrolls fell by 23,000 in July against expectations for a gain, with prior months revised down by roughly 103,000 combined. The unemployment rate ticked to 4.1%, but largely because the labor force shrank.
The Bottom Line
Friday isn’t about the headline — it’s about the reaction to the headline, and the reaction function is flipped. Forget the VIX, watch the MOVE, respect the volatility, and know which game you’re playing before 8:30.
That’s how we do it every market morning over at Masters in Trading, 11:00 a.m. ET. Follow the money, not the narrative.
Editor’s Note: Forbes calls $1 billion fund manager Louis Navellier “the king of quants.” Today, he’s stepping forward to reveal why he’s investing $358 million of his own firm’s money in the next stage of Artificial Intelligence… a technological sea-change that could erase millions of jobs, solve humanity’s biggest mysteries, and spark a wave of moneymaking opportunities — both in and outside the stock market. Click here for the details…
I’ve been spending time and money in this country since 1997.
Lief and I have been living here full- and part-time since 2008.
We’ve raised our son here. Based our business here. Made every kind of property investment it’s possible to make from pre-construction condos to commercial buildings and from productive land to land for banking and the legacy undertaking that is Los Islotes on Panama’s gloriously undiscovered Veraguas Pacific coast.
Based on all that experience, what do I say to anyone who asks me what I think of Panama today?
“Get on a plane and come see for yourself,” I suggest.
Because if you aren’t taking a good close look at all that Panama has to offer right now, you’re missing out.
I appreciate the great advantages that Panama offers the globally minded entrepreneur, but, to be honest, I don’t love Panama City.
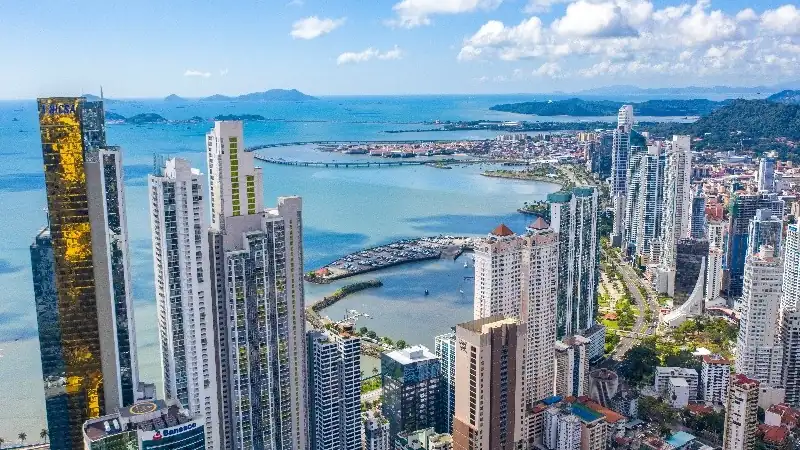
Panama City is a boom town… crowded, dirty, noisy, and hot.
Our now 27-year-old son, on the other hand, enjoys every chance to return to the town where he grew up. He and his friends from school hit the clubs, the restaurants, the casinos.
Panama City is recognized by his generation and other folks younger than me as Miami South.
My favorite thing about Panama City is driving out of Panama City, across the Bridge Of The Americas, headed west.
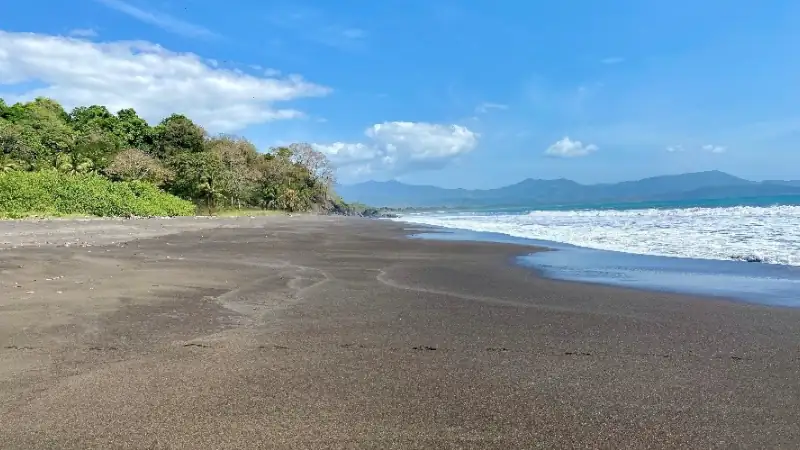
Privacy, elbow room, and a chance to create your own reality in the most virgin natural setting imaginable—those are the things that attracted Lief and me to this outpost in the first place and those are the things we most appreciate about this secret coast still.
Panama City is the most developed city in the region and increasingly recognized as a brand-name city on the world stage alongside Miami and Dubai…
Panama’s Veraguas coast is one of the most unspoiled spots on our planet…
In between are just about every other lifestyle option you could be in the market for… from cool, comfortable living among a welcoming community of fellow expats in Panama’s highlands…
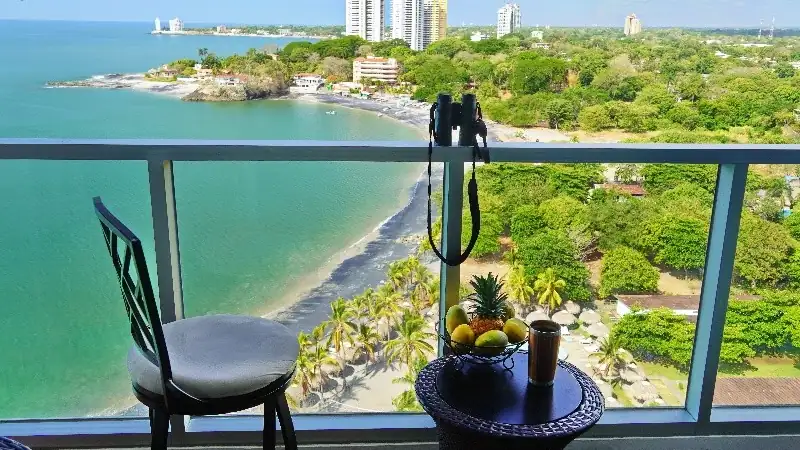
To beaches that are weekend-commutable, within a couple of hours drive of Panama City…
Pounding Pacific beaches that attract the world’s best surfers…
And tranquil Caribbean beaches ideal for unplugging and recharging…
This little country is hugely diverse not only when it comes to lifestyle. Panama also offers one of the world’s most diversified investment markets.
Start Your New Life Overseas Today!
Sign up for our free daily e-letter, Overseas Opportunity Letter, and we'll send you a FREE report on the 12 Best Places To Retire Overseas In 2026.
We Value Your Privacy! We will not share your email address with anyone else, period.
Venezuelans, Colombians, Hondurans, El Salvadorans, Argentines, and others from across Latin America… when they have capital to safeguard, they put it in Panama.
Americans and Canadians, too, likewise, prize this safe-haven marketplace… alongside the French, the Dutch, the Irish, the Spanish, Norwegians, Brits…
As well as, increasingly, investors from Dubai and across the Middle East…
Anyone anywhere seeking safe harbor… they’re looking to Panama.
Jose’s father Herman was one of the first people I met in Panama. Herman took me to see the beach just outside Panama City that he was preparing to develop.
Today, nearly three decades later, that Playa Bonita is a Westin-branded stretch of coastline. We hosted our Beachfront Living Event here this past July…
In the decades since we connected with him, Herman’s Empresas Bern has become “The Brand That Built Panama City”… headed up now by Jose.
As Jose put it when we spoke, investors who want to grow their money need to go to a place that’s growing.
After decades of firsthand experience on the ground in this country, I can tell you…
Boy, howdy, yes indeed. Panama’s growing.
If you’re interested in expanding your lifestyle… or your investment portfolio… or, like me, both…
I strongly recommend that you come on down and see this little country for yourself.
I’d love the chance to show you all that Panama has to offer in person.
If you're an income investor, there's one piece of news you never want to hear: that a company in your portfolio is cutting its dividend. Fortunately, there are signs you can watch out for to help identify coming dividend cuts.
The best index funds let investors earn attractive returns from major indexes such as the S&P 500, Nasdaq-100, and Dow Jones Industrial Average with little effort.
Index funds provide diversification and reduce the risks of investing in individual stocks, but their broad exposure also means some individual stocks can dramatically outperform them.
Investors who successfully identify and invest in outperforming stocks have the potential to generate returns well above the average returns offered by index funds.
Index funds can be a great way to invest in the stock market, and the best index funds allow you to earn attractive returns. The largest and most popular index funds track major stock indexes such as the Standard & Poor’s 500 (“S&P 500”) and the Nasdaq 100 Index.
The S&P 500, Nasdaq 100, and Dow Jones Industrial Average are stock indexes that include America’s largest publicly traded companies and come with a strong long-term track record. The funds based on these stock indexes deliver nearly the same return as the indexes themselves. So, they’re an attractive way to achieve the index’s return with minimal analysis and work.
Top index funds also typically charge low expense ratios, the annual cost of the fund as a percentage of your investment. Top funds might charge $2 to $3 annually for every $10,000 invested in a fund, so you’re not paying a lot for the fund’s advantages. Index funds can charge low fees because they’re passively managed, meaning that they simply replicate the stocks in the index rather than paying analysts to actively find and invest in stocks.
Here are the best index funds for the major indexes, including both exchange-traded funds (“ETFs”) and mutual funds.
Source: Returns from Morningstar, as of Aug. 24, 2026
These funds track the S&P 500, which includes around 500 of the largest stocks traded on American exchanges, such as Nvidia (NVDA) and Apple (AAPL). So, it shouldn’t be surprising that these funds have basically the same average annual return of 13.1% over the previous five years. Therefore, the key differentiator here is the fund’s expense ratio, which ranges from 0% to 0.095%.
While ETFs are usually available to buy and sell wherever you can trade stocks, not all brokerages give you access to the entire mutual fund universe. Mutual funds often charge a minimum initial investment, too.
Three of these S&P 500 funds are ETFs, while four are mutual funds. Just one fund – the Vanguard mutual fund – charges a minimum investment, while its counterpart – the Vanguard S&P 500 ETF – charges a lower expense ratio and does not have a minimum investment. So, it makes sense to buy the Vanguard ETF or another lower-cost ETF unless you can’t access them.
Source: Returns from Morningstar, as of Aug. 24, 2026
These funds track the Nasdaq, with three following the Nasdaq 100, which includes the 100 largest non-financial firms on that exchange. The other fund tracks the Nasdaq Composite, which measures the performance of all stocks trading on that Nasdaq exchange, including Microsoft (MSFT) and Amazon (AMZN).
While the Invesco QQQ Trust has long been the most popular ETF, the recently introduced Invesco Nasdaq 100 ETF has delivered the same performance at a lower expense ratio.
Meanwhile, the Victory Nasdaq-100 index fund is a mutual fund tracking the Nasdaq 100 and requires a $3,000 minimum investment. The Fidelity fund here tracks the Nasdaq Composite rather than the Nasdaq 100, giving it broader exposure and less concentration in the largest tech stocks.
Invesco Dow Jones Industrial Average Dividend ETF (DJD)
11.9%
0.07%
None
Source: Returns from Morningstar, as of Aug. 24, 2026
Fewer funds track the Dow Jones Industrial Average and its 30 stocks, including Goldman Sachs (GS) and Caterpillar (CAT). The SPDR Dow Jones Industrial Average ETF is the key name to watch here. Meanwhile, the Invesco ETF here focuses only on dividend-paying stocks in the Dow Jones Industrials.
Investors looking for more dividend-paying investments should review the best dividend ETFs.
Which Index Fund Is Best for You?
In general, if you’re searching for an index fund for a major index such as the S&P 500 or Nasdaq 100, you have several fund choices. Since funds tracking the same index deliver very similar performance, the best pick is often the one with the lowest expense ratio.
Any of the funds on these lists are cheap or reasonably priced. The S&P 500 funds here offer the lowest expense ratios overall, but even funds in other categories are still fairly priced.
If you go with the Fidelity ZERO fund above, which charges no expense ratio, it’s important to know it does so by avoiding the S&P branding and the related fees. The fund still tracks the index, but Fidelity can’t market it as an S&P 500 fund.
In general, unless you need to buy a mutual fund – say, you’re investing in a retirement account – an ETF is often the better choice. They tend to have a lower expense ratio and don’t require a minimum initial investment, unlike mutual funds. Plus, they trade throughout the market day, unlike mutual funds, which are priced and traded only at the end of the day.
As mentioned above, not all mutual funds are available at all brokers. For example, the Fidelity fund with no expense ratio is not available at many brokers. However, any of the ETFs above should be available at any broker that offers stock trading.
Reasons to Invest in an Index Fund
The key advantage of an index fund is that investors can earn strong returns without spending much time or energy analyzing stocks.
Investors in an S&P 500 Index fund get exposure to the 500 or so stocks in that index, and the funds closely track the index’s performance, which has been about 10% over long periods and even more recently. Each share of the index fund lets investors own a small slice of all the companies in the index, and it charges one low management fee that is deducted seamlessly from the account.
Index funds offer immediate diversification, lowering the risk of investing in an individual stock. Diversification is the idea that your money is spread out across many different investments, so that the performance of one stock doesn’t hurt your overall performance too much.
Of course, there’s a flip side to diversification, too. An index fund’s performance is just the weighted average performance of all the stocks in it. So, it’s necessarily an average. In other words, some stocks will perform much better than the average.
If you can find outperforming stocks, your overall return can do drastically better than an index fund’s average. So, it can be worth your time and money to search out high-flying stocks.
Regards,
James Royal, PhD
Editor’s Note: Whitney Tilson called the rise of Apple, Amazon, and Netflix… as well as the collapse of dozens of companies that went bankrupt. Now the former $200M hedge fund firm manager is stepping forward with what he calls the most important financial warning of his 30-year career. He’s sharing two free stock recommendations (one to buy, one to sell immediately) along with details of a new proprietary system fueling his predictions. See it all in his free presentation.
On June 7, 1939, US President Franklin Roosevelt signed a new law authorizing $100 million (a lot of money back then) to buy rubber, tin, tungsten, etc., and put it all in storage.
The United States was still at peace at the time. World War II had not yet broken out, and global trade was still relatively seamless.
But anyone reading a newspaper could see what was coming. Hitler had annexed Austria the year before and swallowed the rest of Czechoslovakia that March. Japan had been at war in China for two years.
Every commodity on Roosevelt’s list had one thing in common: America produced next to none of it. Nearly all of the rubber used by US companies, for example, came from British Malaya and the Dutch East Indies. A lot of tin came from Malaya as well.
Congress and Roosevelt were being appropriately cautious. And within a short time they had stockpiled hundreds of thousands of tons of these strategic assets.
Then came the War. Then Pearl Harbor. And then full-blown economic chaos.
By March 1942, for example, Japanese troops had overrun Malaya and the Dutch East Indies… meaning that about 90% of America’s rubber supply vanished overnight. Fortunately, their foresight to build stockpiles cushioned the blow.
This critical lesson in self-sufficiency is easily forgotten. As long as global peace and cooperation feel permanent, governments never think about resource scarcity. They assume they will always be able to trade for what they need… so why waste money stockpiling?
But global peace and cooperation can quickly turn to conflict and tension, and that is the environment we are in today.
The last major global conflict was World War II. Before it was over, 730 delegates from 44 nations literally sat down at a conference and hammered out a new framework for economic cooperation that made the US dollar the world’s undisputed reserve currency.
As a result, every country on earth has parked its savings in US government bonds for the past eight decades.
It hasn’t always been easy. The US formally ended the convertibility between the dollar and gold in the 1970s, and there was some thought to creating a new financial system. But the dollar managed to survive as king.
The dollar’s status has also been at risk throughout this century, between the skyrocketing US national debt and heavy-handed legislation (like FATCA) that the US government forced on the rest of the world.
But, still, the dollar survived. And foreign countries kept buying dollars and Treasury bonds.
But everyone has a breaking point, including foreign countries.
The US government’s response to freeze Russian assets in 2022 was the start. Then came last year’s so-called “Liberation Day”, when decades of trade policy were upended, overnight. Then came the Iran war. And now a $40 trillion national debt with no end in sight.
This has all been enough for foreign governments and central banks to finally reverse course; at first they slowed their purchases of US Treasury bonds. Now they’re actually selling… and diversifying away from the dollar.
The immediate beneficiary has been gold. And we’ve written about this— gold is the most logical asset for central bank diversification because it is already a traditional reserve asset… plus the gold market is very large and liquid.
We believe this trend will continue; gold prices will rise as a result, and quality mining companies should prosper.
But there’s a second element to this diversification story.
After Iran closed the Strait of Hormuz— which carried a fifth of the world’s oil and a host of other critical resources— every government on the planet re-learned the same lesson of World War II: trade and cooperation can vanish in an instant.
And now the entire globe feels a sense of urgency to prepare for the next conflict.
Will China invade Taiwan? Will the US and China go to war? Will Russia and NATO come to blows? Nobody knows, and no government wants to be caught flat-footed, unable to import the critical resources that their economies need to function.
In Roosevelt’s era it was things like rubber and tin.
Today, these critical resources (what we refer to as ‘real assets’) start with energy— oil, natural gas, even coal… plus uranium for some countries.
Now, not every commodity is a real asset. Sugar is a commodity… but the world would be just fine without it. No government is going to stockpile orange juice, lumber, or wool. Or even rubber anymore.
But cut off a country’s oil supply and it reverts to the Dark Ages.
That’s why countries are now stockpiling the strategic assets that are the vital inputs to their economies: copper, rare earths, and even the IP and hardware that power AI.
China is the clearest example. In 2025 alone it added more than a million barrels a day to an oil stockpile and now holds roughly 1.4 billion barrels— the world’s largest reserve.
When Hormuz closed and the US and 31 other countries released 400 million barrels from their emergency reserves, China barely touched its pile and by July was adding to it again.
Its nuclear-fuel imports hit a record last year too, far beyond what its reactors burn; the excess went into stockpiles. And this summer Beijing put a new $9 billion state company in charge of buying mines around the world.
Saudi Arabia, on the other hand, produces plenty of oil, so they don’t need to stockpile it. But they are building nearly two gigawatts of data centers at home rather than risk being cut off from computing power.
A government that sells a Treasury still has to put the money somewhere, and the sensible places are the assets that the US government cannot freeze… and that no central bank can print. That is why the long-term direction of gold is still up.
But it’s also why energy, industrial metals, productive technology, and other vital resources— plus the companies which produce them— have a bright future.
This is the thesis behind Schiff Sovereign’s investment research newsletter, Strategic Assets. A world that no longer trusts the US government moves into gold, and a world that can no longer count on trade cooperation secures its own stockpiles.
We provide research on companies that mine, pump, and build what governments are stockpiling.
Subscribers who acted on our research locked in more than 10x on a small silver producer and more than 6x on a gold and silver producer, both in under a year.
A tin producer featured last summer is up more than 3x, a zinc producer more than 2.5x, and a tanker company about 2.5x. Across the companies we have closed out, winners and losers together, the average return is 172%.
Reinvesting dividends is one great—and very simple—way to grow your wealth. Today, we'll go over how this method works… and share a few details that can make a big difference in the final outcome.
The best dividend stocks can build long-term wealth while generating a growing stream of income that investors can use however they choose.
These top stocks offer current dividend yields of up to 5.9% and have increased their payouts by nearly 20% annually over the past five years.
The strongest dividend stocks are backed by durable businesses that can keep raising payouts for decades while also delivering capital gains.
The best dividend stocks offer solid payouts that investors can rely on for years. They help investors build wealth over time, offer a growing dividend, and are backed by the safety of a company with a solid track record. With a sizable portion of their returns paid out in cash, these top stocks are a great choice for retirees or anyone seeking income.
Top dividend stocks can offer investors the following benefits:
Strong, long-term returns, with attractive capital gains and not just a high payout
A high dividend, with yields higher than 2%, much greater than the S&P 500’s yield
A growing dividend, with a payout that grows at least at the target rate of inflation
A solid business, a larger company that has survived and thrived, often for decades
Lower volatility, meaning the stock fluctuates less than the average stock
The best dividend stocks give you the chance to build wealth while offering a growing stream of dividends for decades, giving you the cash to spend however you like. Certain investors prefer dividend stocks with high yields and some growth over time, while others prefer a lower yield today but higher growth potential over time.
This list of 11 dividend stocks offers options for both approaches.
Best Dividend Stocks: How They Compare
Stock (Ticker)
Dividend yield
Five-year annualized dividend growth
Five-year annualized return
Verizon Communications (VZ)
5.9%
2.0%
2.0%
Edison International (EIX)
5.0%
5.7%
8.6%
Kimco Realty (KIM)
4.4%
8.6%
5.7%
Fidelity National Financial (FNF)
4.3%
8.4%
4.5%
Lamar Advertising (LAMR)
4.1%
19.9%
10.9%
Paychex (PAYX)
3.8%
11.9%
4.2%
CareTrust REIT (CTRE)
3.7%
6.0%
15.0%
Public Storage (PSA)
3.7%
8.5%
4.7%
NextEra Energy (NEE)
2.9%
10.7%
2.8%
McDonald’s (MCD)
2.7%
7.3%
5.0%
Coca-Cola (KO)
2.4%
4.5%
11.1%
Data: Charles Schwab, Morningstar, as of August 14, 2026
Everyone knows Verizon as one of the major U.S. telecom players, but maybe less well known is that it pays a massive dividend of nearly 6%. The trade-off for that high current yield is slow dividend growth, but investors can decide for themselves how they want to play the dividend game. The stock has not had a great five-year run, but its higher current yield gives investors plenty of reason to stick around and wait for the stock to catch a bid.
Market cap: $201 billion
Dividend yield: 5.9%
2. Edison International (EIX)
Electrical utilities can be great dividend picks because they enjoy stable, growing demand for their key product. They also tend to increase prices year after year, and their stock tends to be relatively stable because of these advantages. For California-based Edison, that has resulted in an attractive dividend and a history of raising it quickly.
Market cap: $27 billion
Dividend yield: 5.0%
3. Kimco Realty (KIM)
Kimco Realty is a real estate investment trust (“REIT”) that owns grocery-anchored shopping centers and mixed-use properties in major metro areas. Kimco’s “must-visit” properties generate reliable rents that grow over time, and as a REIT, it must pay out most of its income as dividends.
The company’s meaty current yield doesn’t come at the expense of strong dividend growth over the past five years either.
Market cap: $16 billion
Dividend yield: 4.4%
4. Fidelity National Financial (FNF)
Fidelity National Financial may not be a familiar name for many investors, but if you’ve ever bought or sold a house, there’s a good chance you’ve used the company for its title insurance. It’s the leading player in this oligopolistic industry, and it has delivered excellent returns over time, even if the past five years have been ho-hum.
It offers a high current yield, and management hasn’t been stingy about increasing the payout over the past half-decade, giving investors reason to hold the stock for a while.
The company has grown its meaty dividend nearly 20% annually over the past five years, on the way to putting up nearly 11% annualized returns.
Market cap: $16 billion
Dividend yield: 4.1%
6. Paychex (PAYX)
Paychex offers human resources management and payroll processing for small- and medium-sized businesses, among other related services. It has delivered tremendous returns for investors over time, even if the past five years have been a bit mediocre.
But that may be just a brief pause before another period of exceptional performance. Today’s investors can lock in a strong dividend and look for signs that management will raise that payout aggressively moving forward.
Market cap: $43 billion
Dividend yield: 3.8%
7. CareTrust REIT (CTRE)
CareTrust may not be a household name like others on this list, but it has delivered solid returns to investors, with a high yield and a growing payout over time.
As a REIT, it must make sizable dividend payments, and its business of leasing out healthcare facilities on long-term leases with annual rent escalators ensures the stable revenue that’s a prerequisite for a top dividend stock.
Market cap: $9 billion
Dividend yield: 3.7%
8. Public Storage (PSA)
Public Storage is the behemoth in the self-storage space. As a real estate investment trust, it has to pay out most of its income as dividends. It offers a high current yield that has grown at a brisk 8.5% annually over the past five years, meaning you’re getting the best of both worlds.
NextEra is one of the largest North American electric utilities, with about 80 gigawatts of generation and storage capacity. NextEra is almost the definition of a “must-have” asset, with a product that will always be in demand, even while offering strong upside as AI-driven power demand pushes prices higher.
The stock’s above-average dividend has been growing quickly over the past half-decade, and recent price weakness may be a long-term opportunity.
Market cap: $179 billion
Dividend yield: 2.9%
10. McDonald’s (MCD)
McDonald’s may be famous for its Big Mac, but the firm makes much of its money from franchise fees and leasing out the real estate that sits beneath its thousands of restaurants.
As one of the most popular consumer businesses, the Golden Arches has shown notable durability, helping drive a solid dividend that’s grown at a fast 7.3% over the past five years.
Market cap: $193 billion
Dividend yield: 2.7%
11. Coca-Cola (KO)
While everyone knows the company’s namesake drink, Coca-Cola is a drink distributor that can deliver whatever consumers want – sodas, water, sports drinks, and juices. Coca-Cola has proven that it can thrive over decades, while increasing its dividend for 64 straight years.
Although its yield is on the lower side of our list, it has grown at a reasonable 4.5% annualized clip, while the stock has returned about 11% annually on average over the past five years.
Market cap: $377 billion
Dividend yield: 2.4%
Another Top Dividend Stock to Consider for Retirement Investors
The best dividend stocks offer strong returns over time that investors can rely on year after year, and Wall Street veteran Whitney Tilson has spent decades hunting for a business so durable that an investor could build an entire retirement portfolio around it.
Now, he says he has found a business that could deliver even bigger, more durable returns than the legendary business of Berkshire Hathaway and keep delivering for decades.
Most investors have never heard of this company, and it only has around 100 employees. The company doesn’t exactly sit in a major metropolitan area either, doing business on a stretch of West Texas and New Mexico bigger than the size of Rhode Island.
That might make you think of oil, but this company doesn’t drill wells and doesn’t own a data center or generate any power. Instead, it owns the ground beneath one of the largest industrial build-outs in modern American history.
And every single time someone wants to use that ground, this company collects a payment.
Rick Rule is the GOAT of resource investing—and we just sat down together to go through every major commodity on the board. From gold's pullback to uranium's structural deficit, the opportunities are bigger than most investors realize.
Wall Street veteran Whitney Tilson has spent decades hunting for one thing…
A business so durable, and so hard to copy, that an investor could build an entire retirement portfolio around it.
For years, his answer was Warren Buffett’s Berkshire Hathaway (BRK-B).
Whitney owned shares… recommended the company to his friends, family, and readers… and even flew to Omaha for 27 of the past 28 Berkshire annual meetings.
But today, he says he has found a business that could deliver even bigger, more durable returns… and keep delivering for decades.
It’s a company that most investors have never heard of. It has barely more than 100 employees and sits on a stretch of West Texas and New Mexico bigger than the size of Rhode Island.
Now, Texas might make you think about oil…
But this company doesn’t drill wells… doesn’t own a data center… or generate any power. Instead, it owns the ground beneath one of the largest industrial build-outs in modern American history.
And every single time someone wants to use that ground… this company collects a payment.
Why You Should Buy America’s Greatest Retirement Stock
Before we get to the company itself… and yes, Whitney reveals the name and ticker symbol free of charge, which we’ll cover below… it helps to understand why he’s making such an extraordinary claim in the first place.
After all, this is a legendary investor who spent nearly two decades running hedge funds in Manhattan. And for most of his career, he told anyone who would listen that Berkshire Hathaway was the single best place to park retirement money.
He hasn’t turned against Berkshire, exactly. In his free daily letter this January, Whitney highlighted several of his favorite stocks for 2026. There, he noted Berkshire’s share price was trading at about a 7% discount to its intrinsic value, concluding that:
At that price, I view Berkshire as a comfortable hold, not a buy.
And sure enough, so far this year, Berkshire has traded in a fairly tight, go-nowhere range.
The stock is trading at a 14.6% discount to my estimate of intrinsic value.
So, in the past year, Berkshire has swung from being 8.9% overvalued to 14.6% undervalued. That’s why it wasn’t attractive then – but is today.
I’m especially bullish because in addition to today’s discounted stock price, I’m optimistic that [new CEO Greg] Abel can create value via operational improvements and capital allocation.
This combination leads me to believe that Berkshire’s stock is highly likely to beat the S&P 500 [Index] over the next five years, perhaps by a margin of two to three percentage points. So if the S&P 500 compounds at 5%, I would expect Berkshire to do roughly 7% to 8% – with a bias toward the upside.
That’s a solid outperformance expectation… But if you’re putting new money to work for the next 10 or 20 years, Whitney believes there’s a better option.
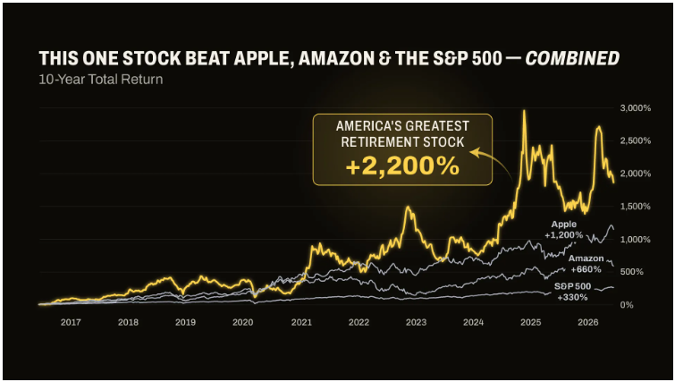
This single stock returned more than 2,200% over the past decade. Over that same stretch, he notes, the S&P 500 returned about 330%, Amazon (AMZN) returned about 660%, and Apple (AAPL) returned about 1,200%.
By his math, this single company beat Apple, Amazon, and the S&P 500… combined.
The question is… can it do it again?
Can This Company Turn $10,000 Into $220,000?
This company operates what Whitney calls the world’s most profitable tollbooth.
It’s a surprise beneficiary of two industries that the federal government is now treating as matters of national security… artificial intelligence (“AI”) and energy. Plus, it overlaps with a third resource that almost nobody on Wall Street is watching.
The core business of America’s Greatest Retirement Stock is simple: It owns land… And it leaves the hard work to everyone else.
When an oil giant pumps crude from under its land, the company collects a royalty.
When someone pulls natural gas from the same ground, another royalty.
When a tech giant wants to build on the surface, it pays lease and easement fees.
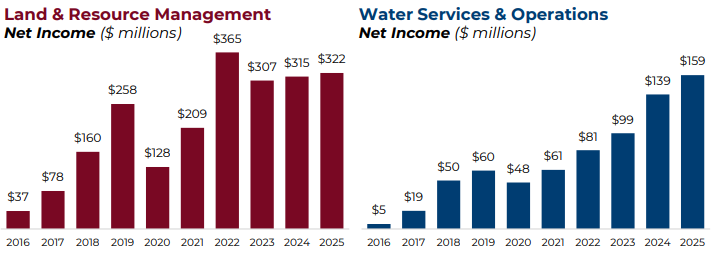
And when anyone needs water out in that desert… sure enough, they buy it from this company, too.
That’s four separate streams of income, just from owning a big patch of dirt. And because the company operates like a tollbooth, it hardly has any costs.
As a result, this company’s business model produces incredible numbers…
It carries no debt, has averaged gross margins of around 90% for the past five years, and converts more than 60 cents of every dollar in revenue into pure profit.
All that cash has to go somewhere. That’s why, while the company pays a regular quarterly dividend like many blue chips, it also pays a special dividend once or twice a year to shareholders that can run 5 to 10 times the size of the normal payout.
By Whitney’s count, an investor who held 1,000 shares would have collected more than $45,000 in total dividends in 2024 alone… and roughly $146,000 over the past six years.
Of course, those amounts depend entirely on when you buy and how much you own. But the point is that this is a business that gushes cash and hands it back to its investors. And Whitney expects it will keepdoing so, just as it has through the many booms and busts over the past century.
And right now, the heavyweights are taking notice…
Eric Schmidt, the man who ran Alphabet’s (GOOGL) Google for a decade, jumped in this past December. He’s building massive AI data-center campuses on this exact stretch of West Texas land. Schmidt explained his reasoning in an interview with Fortune magazine earlier this year:
Energy is the main constraint in scaling AI. If we want to keep America competitive, we have to solve this problem… We realized that combining my technical expertise with [this company’s] unrivaled land, abundant water, and access to low-cost energy could create the infrastructure needed to meet the virtually infinite demand for compute.
One of the most connected technologists alive looked across the entire country for the best place to solve AI’s biggest problem… and picked this company’s land.
Add it all up, and Whitney lands on an extraordinary projection. He believes a $10,000 investment in this company today could grow into $220,000 over the long term. (You can watch his full interview by clicking here.)
That’s not a guarantee, of course. But Whitney argues that number could even prove conservative if the build-out he witnessed in Texas keeps accelerating.
So let’s dig into the details that Whitney believes will drive the next decade of gains…
The Largest Construction Boom in American History
America’s Greatest Retirement Stock, according to Whitney Tilson, is Texas Pacific Land (TPL).
It owns roughly 882,000 acres across West Texas and southern New Mexico, with most of that footprint sitting in the Permian Basin… the most productive oil basin on the planet. As Fortune noted, that’s more acreage than the entire state of Rhode Island.
For years, that land mostly just sat there… Then came the shale revolution, and the royalty checks started rolling in. And now, something even bigger is happening…
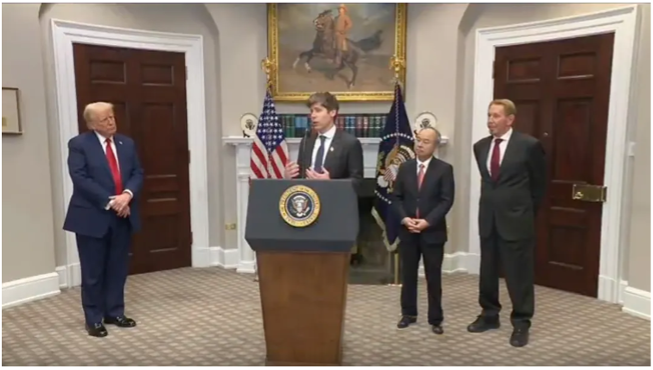
On his first full day back in the White House, President Donald Trump stood beside three of the most powerful men in technology… OpenAI’s Sam Altman, Oracle’s (ORCL) Larry Ellison, and SoftBank’s (SFTBY) Masayoshi Son… and announced a venture called Project Stargate.
The plan calls for up to $500 billion of AI infrastructure spending in the U.S. by 2029.
Trump framed the program as a response to a national emergency, and promised to use executive orders liberally to clear the way for the construction permits and power plants the facilities will need.
And right now, the first Stargate data-center campus is going up outside Abilene, Texas.
The campus now covers ground equal to about 750 football fields, with plans for enough electricity to power 750,000 homes. And just down the road, the Pentagon is pouring $1.6 billion into Dyess Air Force Base to prepare it for the B-21 Raider, America’s new stealth bomber.
Whitney flew to Abilene with his research team, then rented a helicopter to see all this construction from the air. His guide was an old friend and longtime source – third-generation Texas wildcatter Charles Schroeder… who everybody simply calls “Cactus.”
It’s like it pops up overnight… Those construction people are working 24/7. They have lights. They work all night, they work all weekend.
AI spending by the biggest tech companies is expected to jump 71% this year alone, from roughly $380 billion in 2025 to an estimated $650 billion in 2026, according to my colleague Jim Royal’s analysis of the major tech companies. Whitney pegs spending by the five biggest players at nearly $700 billion this year.
And this stretch of West Texas is ideal for four reasons, as Whitney notes:
Vast open acreage… cheap and abundant power… massive water supplies… and the right geology – rock formations that hold the natural gas needed to power these projects.
America’s Greatest Retirement Stock controls all four on nearly a million acres… in the exact region where all of this is happening.
In addition, West Texas is remote… There’s almost nobody around to object to these massive projects. The permit fights and lawsuits I noted in my data-center backlash coverage mostly happen where data centers crowd against suburbs.
Out past Pecos and Abilene, the nearest angry neighbor might be a herd of cattle.
It’s no surprise that land values out there have gone vertical. When Cactus started working this land decades ago, Whitney says, ranch land changed hands for $300 to $500 an acre. Today, AI companies are paying as much as $50,000 an acre.
Of course, TPL isn’t selling…
Instead, the company collects its surface leases, easements, and access fees… keeping its ownership of the dirt underneath. And a tech giant building a data center stuffed full of billions of dollars of chips is one of the “stickiest” long-term tenants out there.
But as big as the land story is, Whitney believes Wall Street is missing an even bigger opportunity…
Every Data Center Needs Water
A single large data center can consume up to 5 million gallons of water per day… about the same as a city with 50,000 residents.
And dozens of these data centers are planned for West Texas…
That’s another big opportunity for TPL. Over the years, it has built one of the largest water operations in the Permian Basin.
Oil drillers were TPL’s original customers. Every fracked well needs massive volumes of water to get the oil out. And now, data centers are lining up for access, too.
As part of the joint venture, America’s Greatest Retirement Stock holds the right of first refusal to supply water to every project built through the partnership.
In other words, Schmidt agreed to make this company his water supplier – for every facility he builds.
Even Schmidt himself called out this company’s “abundant water” as one of the key reasons he made this $150 million bet.
Mark my words: Within 24 months, Wall Street analysts will be valuing the water business of America’s Greatest Retirement Stock alone at billions of dollars. Right now, most of them barely mention it.
Already, TPL’s water business – through water sales and produced water royalties – made up nearly half of its revenue in its latest fiscal year. And it’s growing fast.
The chart below from the company’s recent investor presentation compares its net income for its land and resource operations with its water business…
The kind of repricing that Whitney is expecting can move TPL stock massively.
And of course, we still haven’t gotten to the company’s true focus…
Royalty Checks on Both Oil and Natural Gas
TPL’s vast acreage is in the Permian Basin, where ExxonMobil (XOM) and Chevron (CVX) run some of their largest operations. So when those oil majors pull crude oil from under TPL’s land, the company collects a royalty on every barrel.
It’s one of the world’s best businesses…
While an oil producer has to spend millions on drilling holes and hiring crews, a royalty business like TPL that owns the land just collects a check. That makes royalties one of the cleanest hedges for inflation, rising energy prices, and a falling dollar.
But Whitney believes TPL’s oil royalties are only part of the story now… and that its natural gas income stream is about to surge.
AI data centers require electricity on a scale the American power grid simply cannot deliver. Whitney’s presentation puts the average wait to connect a large new facility to the grid at more than eight years. That’s not a realistic time frame for hyperscalers trying to win the AI race.
The U.S. power grid can’t keep up with AI’s electricity demands.
Mainstream publications like the Wall Street Journal and the Washington Post have called the current U.S. grid “archaic” with “onerous and outdated” regulation and years of underinvestment.
The North American Electric Reliability Corporation (“NERC”), the body responsible for ensuring grid reliability, has warned of growing risks of widespread blackouts. The Department of Energy is also projecting sharp increases in blackout risk by 2030.
So, to power its data centers, Big Tech companies have stopped waiting and started building their own power plants… typically fueled by natural gas.
In Texas alone, natural gas power projects in development will add nearly 58 gigawatts of new generating capacity. For comparison, that’s more than the annual peak demand of the entire state of California. And most of that new capacity – 40 gigawatts’ worth – was specifically planned to power data centers.
And this summer, the biggest behind-the-meter deal yet landed right in TPL country.
Project Kilby is expected to consume about 2.7 gigawatts (“GW”) of power. According to CNBC, that’s enough power to fuel more than 2 million homes. Construction hasn’t started just yet. The data center is expected to start receiving power in 2028.
Chevron has a large footprint in the Permian Basin in West Texas and southeastern New Mexico. This allows it to quickly and efficiently supply power to Texas data centers like Project Kilby, says Jeff Gustavson, Chevron’s president of New Energies, in a statement announcing the deal.
Follow the money on this kind of deal, and you can watch TPL cash in on every single one of its four main royalty streams…
When Chevron pulls Permian gas to fuel its turbines, TPL collects a percentage.
When Microsoft (MSFT) builds its data center on leased TPL land, it collects a rent check.
When millions of gallons of water are used for cooling the chips inside the data center, TPL’s water business gets paid.
And when pipelines and power lines cross TPL’s acreage to supply these data centers, the company also gets paid easement fees.
In nearly 20 years of running a hedge-fund firm, I’ve analyzed thousands of businesses. I have never seen anything like this one.
It has no debt… nearly $500 million in annual free cash flow… more than 60 cents of every revenue dollar converted into net profit… and remarkably low operating expenses – because this company doesn’t drill, doesn’t build, and doesn’t lay pipe.
It makes deals and turns those assets into cash.
You don’t have to guess which AI company wins. You don’t have to pick the best oil driller, either. You can simply buy TPL and enjoy its regular royalty stream as the AI race grows more frenetic.
Of course, while TPL is a great way to play this trend over the long term, Whitney also points to potentially much bigger gains to be made in the short term, too…
How to Make Even Bigger Gains From the Commodity Supercycle
Now, the one commonality across TPL’s royalty streams is that they’re largely focused on hard assets… land, oil, natural gas, water.
Commodities.
And right now, Whitney believes we may be at the beginning of the biggest commodity supercycle of our lifetimes.
In each cycle, he says, the best resource investments handed early buyers gains of 500%, 1,000%, or more… even as ordinary stocks stagnated.
Take the late 1960s and early 1970s…
By his figures, silver exploded 3,000% in the following decade, gold soared 2,300%, and oil climbed 1,000%… while the S&P 500 went nowhere for 10 straight years.
And today, commodities are currently trading near the cheapest levels of the past century. Whitney charted out 120 years of commodity prices with the stock market in his presentation:
Why is this supercycle kicking off right now? Whitney points to three specific catalysts:
First, a decade of starved supply has sent prices higher. Mining exploration budgets have collapsed about 40% from their 2012 peak, and oil and gas capital spending has fallen from $900 billion in 2014 to $570 billion in 2025.
Second, demand is exploding, courtesy of the AI build-out we covered above. Every data center needs massive amounts of electricity, copper, steel, and fuel.
Finally, the dollar itself is under pressure. Gold has been shattering records as central banks swap Treasury bonds for bullion, a trend Whitney notes has topped 1,000 tonnes of official annual gold purchases for three consecutive years.
When paper money weakens, hard assets tend to rise. And TPL may be the hardest asset of them all… land that gets paid royalties from oil, gas, and water… located smack-dab in the one place America’s biggest companies are spending trillions.
What Investors Should Do Today
Whitney believes commodities are the single best thing you can own in the world today.
And he has the credentials to back up that claim…
As a former hedge-fund manager, he grew $1 million into a collection of funds worth more than $200 million.
He has helped his readers get into stocks like Netflix (NFLX) at 78 cents, adjusted for stock splits, before it soared more than 11,000%… Apple at 38 cents, before it climbed 80,000%… and Amazon at $2.80… before it went on a 9,000% run.
And he has been featured in practically every major financial publication and TV show, including two appearances on CBS’s 60 Minutes to announce a major stock exposé.
After leaving the hedge-fund world, Whitney moved into investment research and education and now heads a team of analysts at one of the largest independent financial publishers in the world.
There, he shares his highest-upside opportunities with tens of thousands of subscribers… including at least five paid-up billionaires.
And of course, Whitney is offering a full 30-day money-back guarantee for all new subscribers. So you can give his research a try without a long-term commitment today.

 Login