❌

Reading view

Moving Arrowhead Pharmaceuticals Off The Watchlist

In Porter’s first issue of Porter & Co. Biotechnology, he recommended one of the key players in gene silencing, Arrowhead Pharmaceuticals (Nasdaq: ARWR). However, he felt that we needed to wait for a better entry price. In that August 1 issue, he said that Arrowhead had done everything right: its triglyceride drug is approved and selling, it has pushed gene silencing into muscle, fat, lung, and brain, and the large drugmakers have paid Arrowhead billions for access. The stock had run from $15 to $87 in the past year. We want to own this company below $75, he concluded.

Shares of Arrowhead Pharmaceuticals are now trading around $67 per share, so we are moving them from our watchlist into a “buy” recommendation, below $75.

Action to Take: Buy Arrowhead Pharmaceuticals (Nasdaq: ARWR) below $75 per share

The post Moving Arrowhead Pharmaceuticals Off The Watchlist appeared first on Porter & Co..

  •  

Trading Club Pro Alert And Update – Week Of September 14, 2026

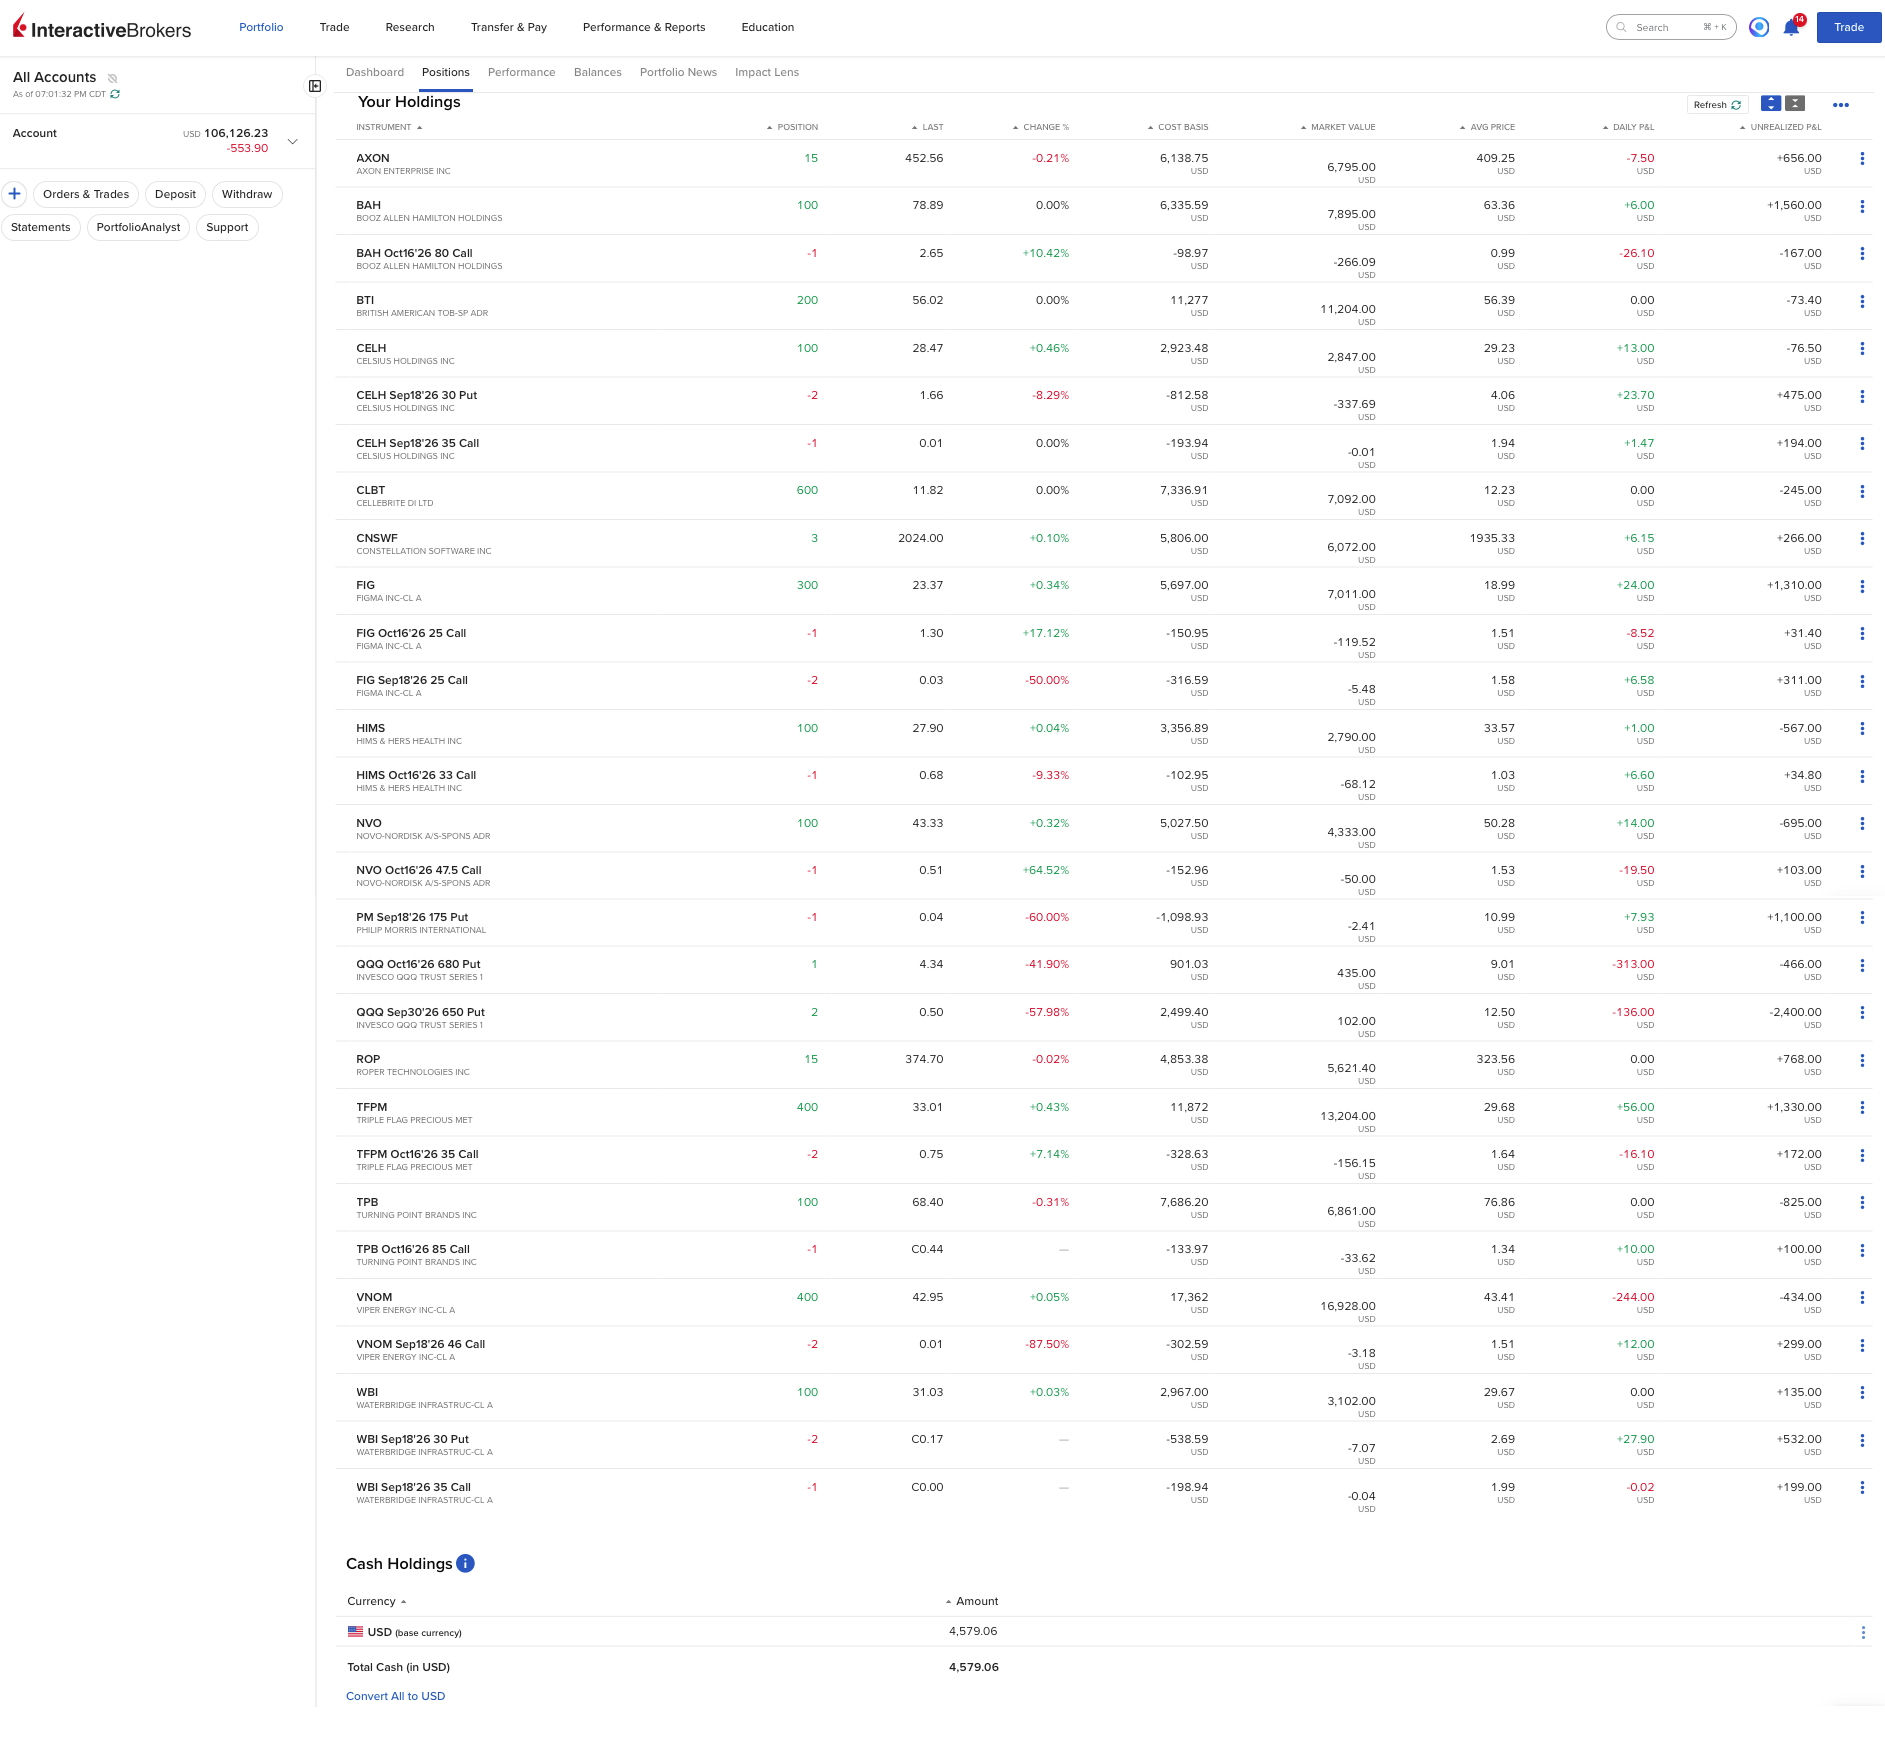
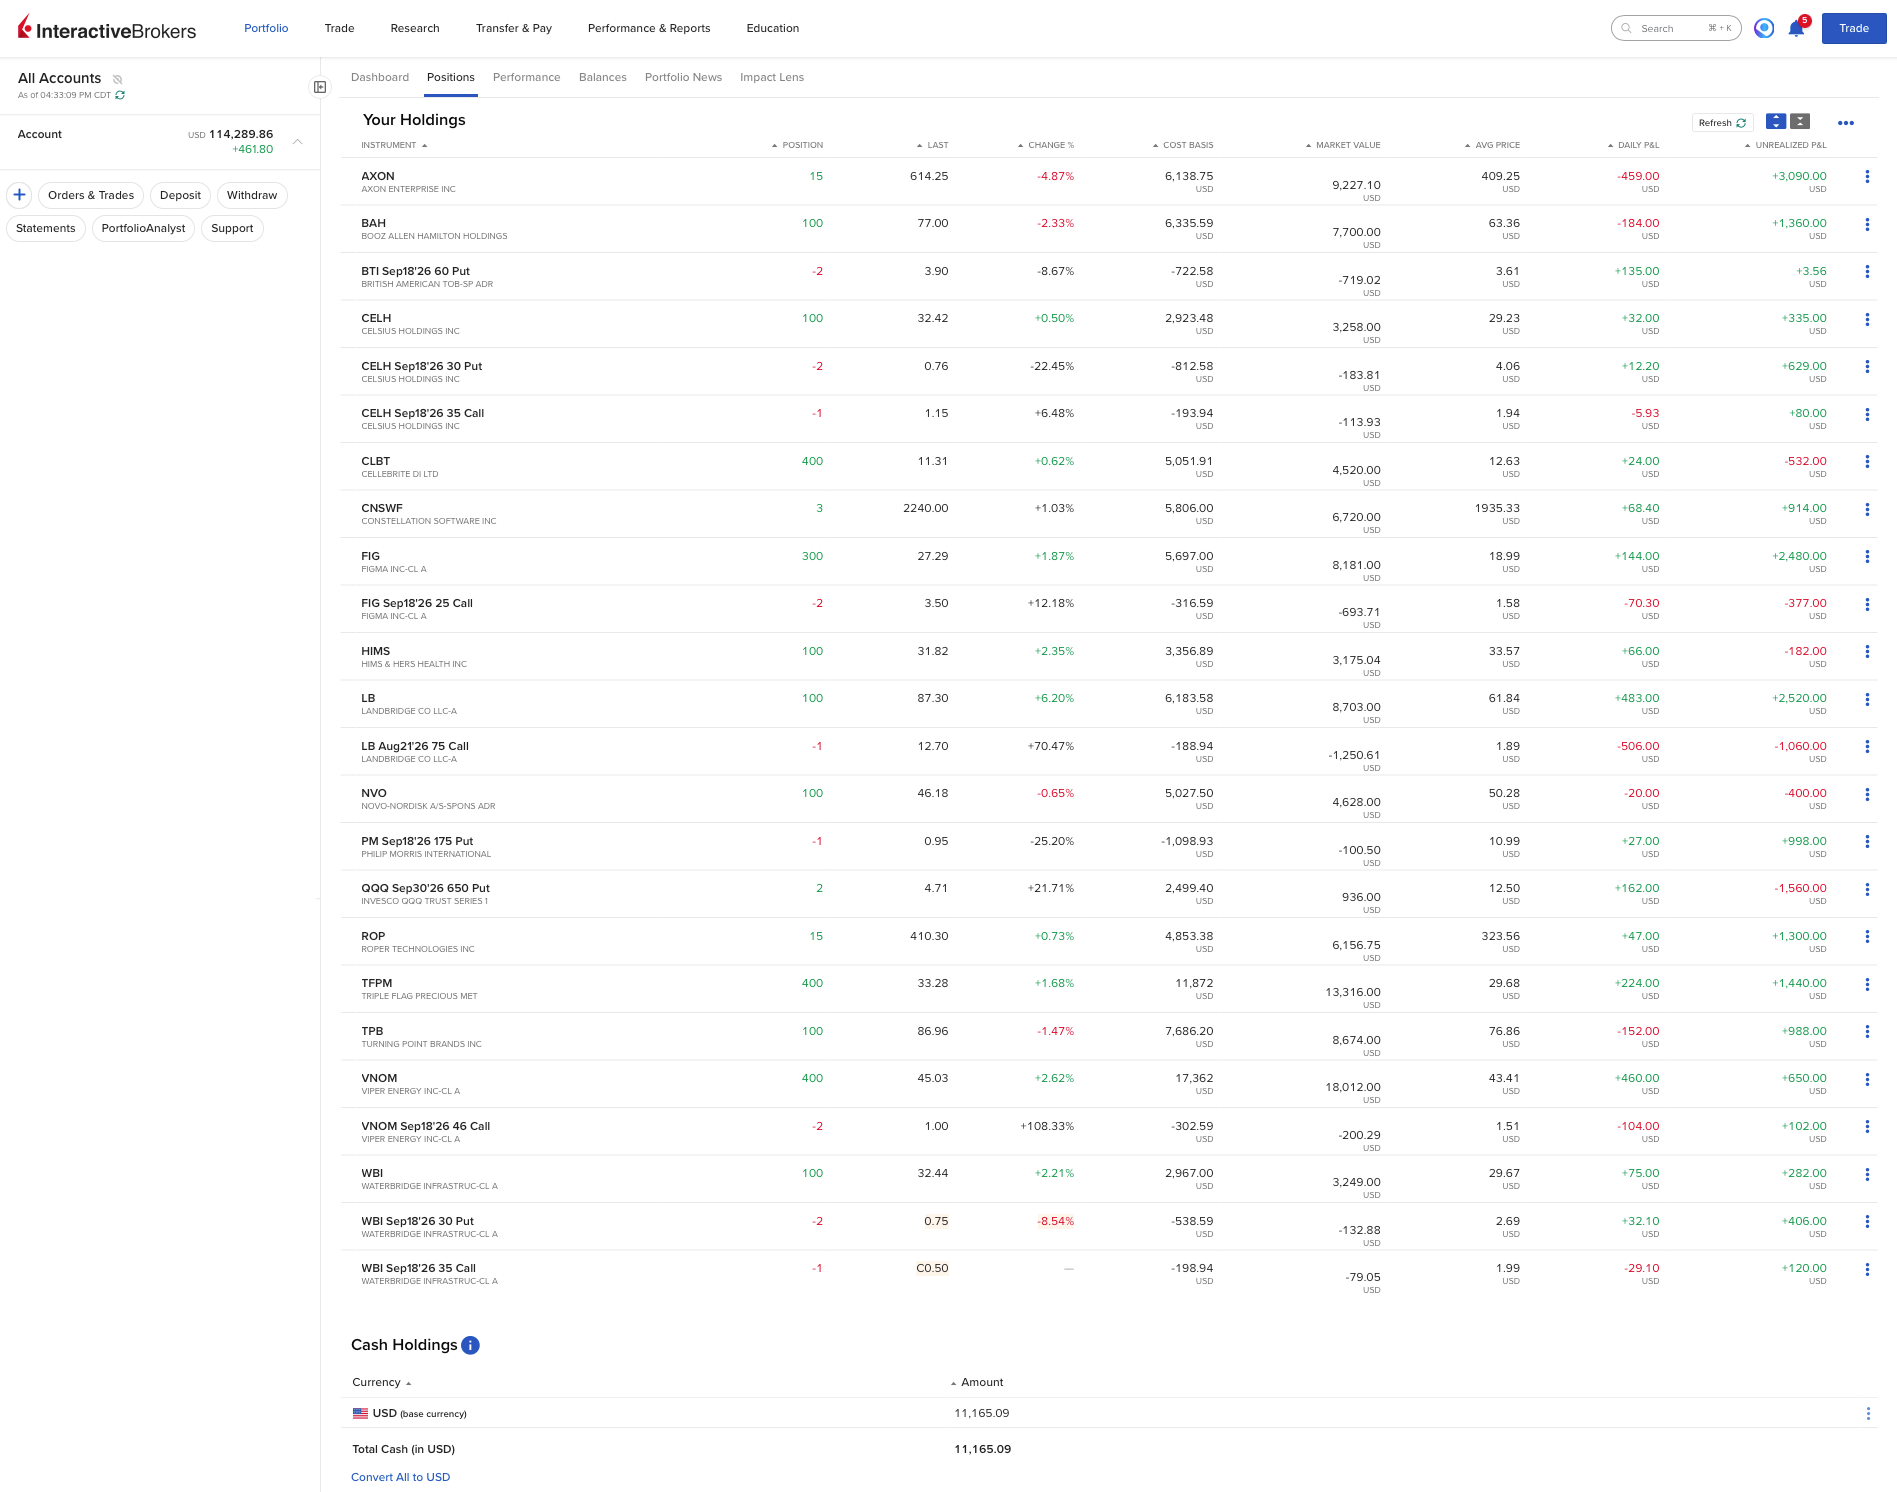
The value of The Trading Club Pro tracking portfolio settled at $106,126 as of Thursday, September 17 – up 6.1% since the June 22, 2026, inception date (see the detailed portfolio snapshot below). Based on last Friday’s trade alert, we made the following transaction in our Trading Club tracking account on Monday:

Bought to open one Invesco QQQ Trust (Nasdaq: QQQ) $680 put, expiring October 16, 2026, at $9.06 per share.

In this update, we review the options set to expire today, September 18, and set the stage for our next series of trades to be released next week. As a reminder, the upcoming recommendations will be shorter-duration “interim” trades, expiring in mid-October. Later in the month, we will return to our normal schedule of publishing quarterly trades, as well as a video recording that walks through each position.

Options Expiration Review

Eight options positions in The Trading Club portfolio are scheduled to expire at the close of trading today, including five covered-call positions and three cash-secured put trades. No action is needed, as we plan to hold all positions through the expiration date.

We’ll begin with a review of the covered-call positions, listed below.

Covered Calls Expiring Today

  • One Celsius Holdings (Nasdaq: CELH) $35 covered call, covering all 100 shares of our 100-share long position
  • Two Figma (NYSE: FIG) $25 covered calls, covering 200 shares of our 300-share long position
  • One WaterBridge Infrastructure (NYSE: WBI) $35 covered call, covering all 100 shares of our 100-share long position
  • Two Viper Energy (Nasdaq: VNOM) $46 covered calls, covering 200 shares of our 400-share long position
  • One WaterBridge Infrastructure (NYSE: WBI) $35 covered call, covering all 100 of our 100-share long position

Based on Thursday’s closing prices, each of the underlying stock prices for these call options are well below the call strike price. As such, these covered calls will likely expire out-of-the-money and become worthless at the close of trading today. In this scenario, we pocket the premiums free and clear, while still retaining the underlying shares, meaning we are then able to repeat a similar trade.

Conversely, if any of the underlying stocks rally and close above the option strike prices today, the options will expire in-the-money. This means our shares will get “called away” and sold at the strike price after the close of trading.

We’re happy with either scenario, and thus no action is needed for these trades.

Next, we’ll review the cash-secured put positions, listed below.

Cash-Secured Puts Expiring Today

  • Two Celsius Holdings (Nasdaq: CELH) $30 cash-secured puts, representing a $6,000 capital commitment to purchase 200 shares at $30
  • One Philip Morris International (NYSE: PM) $175 cash-secured put, representing a $17,500 capital commitment to purchase 100 shares at $175
  • One WaterBridge Infrastructure (NYSE: WBI) $30 cash-secured put, representing a $3,000 capital commitment to purchase 100 shares at $30

Based on Thursday’s closing prices, shares of Celsius were well below the put-option strike price, meaning this option will likely expire in-the-money at the close of trading today. In this scenario, our broker will automatically purchase 200 shares of Celsius on our behalf at $30 per share, for a $6,000 purchase commitment.

Alternatively, if Celsius shares rally above the strike price by the close of trading today, the option will expire out-of-the-money, and we pocket the premiums free and clear, while our obligation to purchase shares disappears.

Conversely, shares of Philip Morris and WaterBridge were above their respective put-option strike prices at the close of trading on Thursday. If shares remain at or above these recent prices, the put options will expire out-of-the-money, removing our obligation to purchase shares. Conversely, if shares fall below their option strike prices, we will be on the hook to purchase 100 shares of stock at the option strike price.

In all cases, we have enough available buying power to make good on these purchase commitments. And because we are willing buyers of each of these underlying stocks at the option strike prices, we will simply hold these positions through the expiration date.

Next, we’ll briefly review our plan for Monday’s trades.

Monday’s Game Plan

To set the stage for our overall market outlook and trading plan going forward, we’ll begin by addressing the following subscriber question from The Trading Club Forum:

Today [September 15], Porter published a very worrying post about the national debt situation and rising interest rates. He recommended selling P&C insurance stocks. I know we don’t hold these stocks, but clearly he is very concerned about the market. I am hoping you can provide your thoughts on the state of the market and how you plan to prepare for what seems like an inevitable market fall. Very worrying times ahead for sure and NOT a time to take risks and not have a clear strategy in place in advance. As the Boy Scouts motto says, “Be Prepared,” which sounds smart to me.

Yes, I share the same concerns as Porter regarding the sharp rise in interest rates, along with the global energy supply crisis, on top of the risks associated with the potential unwind of the artificial intelligence (“AI”) boom. We’ve written about these threats in our prior two weekly updates, which you can find here and here. And in response to these risks, we’ve begun aggressively adding defensive positions into the portfolio, including our recent covered-call sales and protective put purchases.

Of course, it’s also worth pointing that Porter included one key caveat with his warning about the threat from higher interest rates. That is, no one – not even God himself – can predict the future path of interest rates. And I would extend that caveat to the broader idea that no one can reliably predict the near-term swings in any market prices. The past week provided yet another reminder of this fact. Energy prices fell despite additional attacks on energy infrastructure. Long-term bond yields fell despite the Federal Reserve hiking overnight interest rates. And technology stocks rallied even as the two leading AI companies warned of an imminent AI-apocalypse and a potential slowdown in large-language-model development.

So, yes, we are mindful of the downside risks in the market. But the flip side is that we can be wrong, or early (which is the same thing), in recognizing and reacting to these risks. And ultimately, it’s up to every individual investor to decide how they will allocate their capital in the face of the potential risks in the market.

As for our approach in The Trading Club, our goal is to strike a balance between both sides of the risk/return equation – a goal we believe is made possible with a prudent options-trading strategy. Right now, that means foregoing upside on a substantial portion of the portfolio in order to harvest consistent options premiums with our covered-call and put-selling strategies. And to reinvest a portion of these premiums into downside hedges in the technology sector, which we believe is most at-risk from an inevitable (but unpredictable) turn in the market cycle.

Finally, we also plan to maintain a focus on stocks that are beaten down and out of favor, where the discounted valuation means the long-term risk of capital impairment is low. But of course, that doesn’t mean that a cheap stock can’t get cheaper, or won’t get swept up in overall market volatility, as we’ve seen across a large number of our holdings recently.

Over a full market cycle, we have confidence that this basic process of buying good stocks on the cheap, harvesting consistent options premiums, and hedging the downside is a winning formula. That confidence comes from having seen this process work in our own investing portfolios, and it’s why we put real money behind this strategy and promised to show you every trade along the way, warts and all.

On Monday, we plan to continue executing our same basic strategy with a series of similar trades to the ones that expired today. We remain bullish on each of the existing holdings in the portfolio. But given the risks we see in the broader market, we will continue playing defense by harvesting consistent options premiums on many of these stocks, and reinvesting a portion of these premiums into additional hedging trades.

Stay tuned for more on Monday, when you can expect to receive the next trade recommendations in your inbox.

Next, we’ll show each position in the portfolio broken down by trade type.

Portfolio Review

The table below shows all current holdings as of the close of trading on Thursday, September 17. Please note that we have recently modified some of our recommended prices.

A few notes on how to read and interpret this portfolio table.

Please pay special attention to the “Action” column, where we specify whether each trade is a “buy” or “sell to open” transaction.

Next, the position size for each trade is equal to the current value of the position, with the exception of the cash-secured puts. In the case of the cash-secured puts, we define the position size as the total value of our future commitment to purchase 100 shares for each contract. This number is calculated as follows:

Position size = number of contracts x 100 x put strike price

We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade.

For example, in the case of the WaterBridge Infrastructure (NYSE: WBI) $30 puts, the position size equals 2 x 100 x $30 = $6,000. We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade. It’s commonly referred to as the “notional value” of the trade.

To see the current profit/loss across each open position and other details, please see the live snapshot of our tracking portfolio at the end of this update.

We have compiled a summary overview of the latest quarterly trades released on June 22, which you can find here. Since then, we have recommended the additional trades listed below:

  1. On July 17, we recommended purchasing shares of Novo Nordisk (NYSE: NVO), which you can find here
  2. On July 21, we recommended purchasing shares of Hims & Hers Health (NYSE: HIMS), and we provided the analysis for the company on July 24, which you can find here

As a reminder, we calculate the leverage ratio using the following formula:

Leverage ratio = total long exposure/portfolio equity value

We define total long exposure as the sum of all long positions, including uncovered stocks, covered stocks, cash-secured puts, and option purchases. In the current portfolio, as of Wednesday’s close, these values were as follows (note: we show each value in our portfolio table below):

  • Uncovered stocks: $51,969
  • Covered stocks: $49,161 (netting out the underlying stock value against the covered-call value)
  • Put sales: $29,500 (this “notional value” is the value of stock we’ve committed to purchasing)
  • Long options positions: $534

Adding up all of these values gives us $131,164 of total long exposure in our current tracking portfolio. We then divide this number into our account equity of $106,126 to arrive at a 124% leverage ratio – well within our self-prescribed limit of 150%.

If you have any questions or feedback, The Trading Club Forum is the best chance to get a quick response from our team.

Alternatively, you can always email us at mailbag@porterandcompanyresearch.com.

Good investing,

Ross Hendricks
Porter & Co.

The post Trading Club Pro Alert And Update – Week Of September 14, 2026 appeared first on Porter & Co..

  •  

Trade Alert And Update – Week Of September 14, 2026

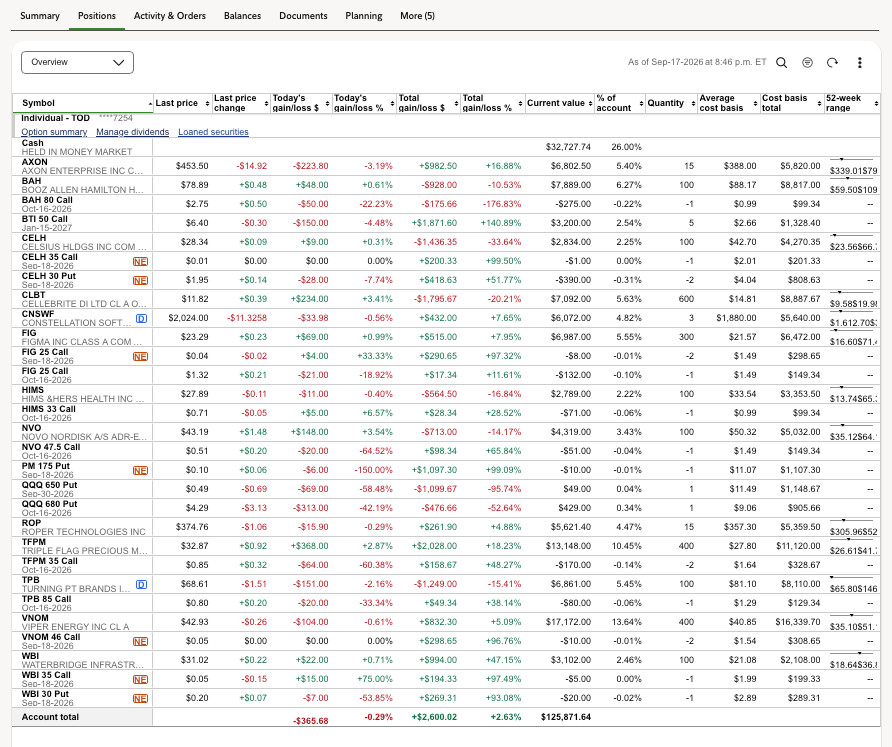
The value of The Trading Club tracking portfolio settled at $125,872 as of Thursday, September 17 – up 25.9% since the May 30, 2025, inception date (see the detailed portfolio snapshot below). Based on last Friday’s trade alert, we made the following transaction in our Trading Club tracking account on Monday:

Bought to open one Invesco QQQ Trust (Nasdaq: QQQ) $680 put, expiring October 16, 2026, at $9.06 per share.

In this update, we review the options set to expire today, September 18, and set the stage for our next series of trades to be released next week. As a reminder, the upcoming recommendations will be shorter-duration “interim” trades, expiring in mid-October. Later in the month, we will return to our normal schedule of publishing quarterly trades, as well as a video recording that walks through each position.

Options Expiration Review

Eight options positions in The Trading Club portfolio are scheduled to expire at the close of trading today, including five covered-call positions and three cash-secured put trades. No action is needed, as we plan to hold all positions through the expiration date.

We’ll begin with a review of the covered-call positions, listed below.

Covered Calls Expiring Today

  • One Celsius Holdings (Nasdaq: CELH) $35 covered call, covering all 100 shares of our 100-share long position
  • Two Figma (NYSE: FIG) $25 covered calls, covering 200 shares of our 300-share long position
  • One WaterBridge Infrastructure (NYSE: WBI) $35 covered call, covering all 100 shares of our 100-share long position
  • Two Viper Energy (Nasdaq: VNOM) $46 covered calls, covering 200 shares of our 400-share long position
  • One WaterBridge Infrastructure (NYSE: WBI) $35 covered call, covering all 100 of our 100-share long position

Based on Thursday’s closing prices, each of the underlying stock prices for these call options are well below the call strike price. As such, these covered calls will likely expire out-of-the-money and become worthless at the close of trading today. In this scenario, we pocket the premiums free and clear, while still retaining the underlying shares, meaning we are then able to repeat a similar trade.

Conversely, if any of the underlying stocks rally and close above the option strike prices today, the options will expire in-the-money. This means our shares will get “called away” and sold at the strike price after the close of trading.

We’re happy with either scenario, and thus no action is needed for these trades.

Next, we’ll review the cash-secured put positions, listed below.

Cash-Secured Puts Expiring Today

  • Two Celsius Holdings (Nasdaq: CELH) $30 cash-secured puts, representing a $6,000 capital commitment to purchase 200 shares at $30
  • One Philip Morris International (NYSE: PM) $175 cash-secured put, representing a $17,500 capital commitment to purchase 100 shares at $175
  • One WaterBridge Infrastructure (NYSE: WBI) $30 cash-secured put, representing a $3,000 capital commitment to purchase 100 shares at $30

Based on Thursday’s closing prices, shares of Celsius were well below the put-option strike price, meaning this option will likely expire in-the-money at the close of trading today. In this scenario, our broker will automatically purchase 200 shares of Celsius on our behalf at $30 per share, for a $6,000 purchase commitment.

Alternatively, if Celsius shares rally above the strike price by the close of trading today, the option will expire out-of-the-money, and we pocket the premiums free and clear, while our obligation to purchase shares disappears.

Conversely, shares of Philip Morris and WaterBridge were above their respective put-option strike prices at the close of trading on Thursday. If shares remain at or above these recent prices, the put options will expire out-of-the-money, removing our obligation to purchase shares. Conversely, if shares fall below their option strike prices, we will be on the hook to purchase 100 shares of stock at the option strike price.

In all cases, since these are cash-secured puts, our broker has already set aside enough restricted cash to make good on these purchase commitments in the event that any of these put positions expire in-the-money. And because we are willing buyers of each of these underlying stocks at the option strike prices, we will simply hold these positions through the expiration date.

Next, we’ll briefly review our plan for Monday’s trades.

Monday’s Game Plan

To set the stage for our overall market outlook and trading plan going forward, we’ll begin by addressing the following subscriber question from The Trading Club Forum:

Today [September 15], Porter published a very worrying post about the national debt situation and rising interest rates. He recommended selling P&C insurance stocks. I know we don’t hold these stocks, but clearly he is very concerned about the market. I am hoping you can provide your thoughts on the state of the market and how you plan to prepare for what seems like an inevitable market fall. Very worrying times ahead for sure and NOT a time to take risks and not have a clear strategy in place in advance. As the Boy Scouts motto says, “Be Prepared,” which sounds smart to me.

Yes, I share the same concerns as Porter regarding the sharp rise in interest rates, along with the global energy supply crisis, on top of the risks associated with the potential unwind of the artificial intelligence (“AI”) boom. We’ve written about these threats in our prior two weekly updates, which you can find here and here. And in response to these risks, we’ve begun aggressively adding defensive positions into the portfolio, including our recent covered-call sales and protective put purchases.

Of course, it’s also worth pointing that Porter included one key caveat with his warning about the threat from higher interest rates. That is, no one – not even God himself – can predict the future path of interest rates. And I would extend that caveat to the broader idea that no one can reliably predict the near-term swings in any market prices. The past week provided yet another reminder of this fact. Energy prices fell despite additional attacks on energy infrastructure. Long-term bond yields fell despite the Federal Reserve hiking overnight interest rates. And technology stocks rallied even as the two leading AI companies warned of an imminent AI-apocalypse and a potential slowdown in large-language-model development.

So, yes, we are mindful of the downside risks in the market. But the flip side is that we can be wrong, or early (which is the same thing), in recognizing and reacting to these risks. And ultimately, it’s up to every individual investor to decide how they will allocate their capital in the face of the potential risks in the market.

As for our approach in The Trading Club, our goal is to strike a balance between both sides of the risk/return equation – a goal we believe is made possible with a prudent options-trading strategy. Right now, that means foregoing upside on a substantial portion of the portfolio in order to harvest consistent options premiums with our covered-call and put-selling strategies. And to reinvest a portion of these premiums into downside hedges in the technology sector, which we believe is most at-risk from an inevitable (but unpredictable) turn in the market cycle.

Finally, we also plan to maintain a focus on stocks that are beaten down and out of favor, where the discounted valuation means the long-term risk of capital impairment is low. But of course, that doesn’t mean that a cheap stock can’t get cheaper, or won’t get swept up in overall market volatility, as we’ve seen across a large number of our holdings recently.

Over a full market cycle, we have confidence that this basic process of buying good stocks on the cheap, harvesting consistent options premiums, and hedging the downside is a winning formula. That confidence comes from having seen this process work in our own investing portfolios, and it’s why we put real money behind this strategy and promised to show you every trade along the way, warts and all.

On Monday, we plan to continue executing our same basic strategy with a series of similar trades to the ones that expired today. We remain bullish on each of the existing holdings in the portfolio. But given the risks we see in the broader market, we will continue playing defense by harvesting consistent options premiums on many of these stocks, and reinvesting a portion of these premiums into additional hedging trades.

Stay tuned for more on Monday, when you can expect to receive the next trade recommendations in your inbox.

Next, we’ll show each position in the portfolio broken down by trade type.

Portfolio Review

The table below shows all current holdings as of the close of trading on Thursday, September 17. Please note that we have recently modified some of our recommended prices.

A few notes on how to read and interpret this portfolio table.

Please pay special attention to the “Action” column, where we specify whether each trade is a “buy” or “sell to open” transaction.

Next, the position size for each trade is equal to the current value of the position, with the exception of the cash-secured puts. In the case of the cash-secured puts, we define the position size as the total value of our future commitment to purchase 100 shares for each contract. This number is calculated as follows:

Position size = number of contracts x 100 x put strike price

We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade.

For example, in the case of the Celsius Holdings (Nasdaq: CELH) $30 puts, the position size equals 2 x 100 x $30 = $6,000. We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade.

To see the current profit/loss across each open position and other details, please see the live snapshot of our tracking portfolio at the end of this update.

We have compiled a summary overview of the latest quarterly trades released on June 22, which you can find here. Since then, we have recommended the additional trades listed below:

  1. On July 17, we recommended purchasing shares of Novo Nordisk (NYSE: NVO), which you can find here
  2. On July 21, we recommended purchasing shares of Hims & Hers Health (NYSE: HIMS), and we provided the analysis for the company on July 24, which you can find here

If you have any questions or feedback, The Trading Club Forum is the best chance to get a quick response from our team.

Alternatively, you can always email us at mailbag@porterandcompanyresearch.com.

Good investing,

Ross Hendricks
Porter & Co.


The post Trade Alert And Update – Week Of September 14, 2026 appeared first on Porter & Co..

  •  

Important Allocation Update

Issue#159, Volume#3

Why We’re Changing Our Allocation In A “Permanent” Portfolio


Today’s Journal is extremely serious, but let me begin with a joke.

Normally, bond salesmen never get into heaven. If you’ve never read the classic Liar’s Poker, then you may not understand why. Bond prices are opaque. That means bond salesmen can frequently get away with “murder” – taking a huge spread out of the trades they do for customers. There are a lot of bond traders without scruples who take advantage of “muppets” and sell them bonds with spreads wide enough to drive a new Ferrari through.

And so bond salesmen generally don’t get into heaven. But when 9/11 happened, God made some exceptions. An entire bond trading firm (Cantor Fitzgerald) got wiped out when the planes hit the towers. So God brought them all in. And he explained:

Look, you guys really don’t deserve to be here, okay. But I feel terrible about what’s happened to you. You’ve lost your lives, your families… your Ferraris. Everything. So, I’m willing to make an exception – this time. But I need something in return…

Well, as you can imagine, the bond traders were shocked and confused at first. But then they realized that God needed something from them. And unless they could give it to him, they were going to hell – for eternity!

The emerging-markets managing director came to his senses first. (He was the one most used to everything going to hell.) He stood up and faced God.

God, you’ve saved us. Thank you. We are all in your debt. And looking back, I understand why you don’t normally allow bond traders in here. We are all grateful and want to do whatever we can to help. What can we do for you, God?

God walked over to him. He put his arm around him and said, “Walk with me a minute.”

As they walked out of earshot of the other traders, God asked…

What do you think interest rates are going to do next year…?

We’re making a substantial change to our recommended allocation in Porter’s Permanent Portfolio. We recognize that there are lots of good reasons not to follow our advice about this change.

In the first place, no one can predict interest rates, not even God. And, secondly, the entire idea of a Permanent Portfolio is that you do not have to do any trading or hedging, as the portfolio is already hedged. It holds 25% in cash and 25% in gold and Bitcoin, which is a hedge against monetary volatility. Assuming you rebalance each year, this kind of portfolio will survive a crisis and continue to prosper – just as it did in 2008/2009 and just as it did during the COVID market panic.

But even though there are real risks to making this change, we think it’s the best course – for conservative investors who are retired.

Here’s why.

The 10-year U.S. Treasury yield hit 5% on Monday, September 14, driven by soaring energy prices, the widening war with Iran, and a bond market losing patience with Washington’s deficits.

Interest rates on the benchmark U.S. bond have only touched that level once since before the Global Financial Crisis, in October 2023. But by that point, the Fed had raised its benchmark rate 11 times (!) since starting the cycle in March 2022, taking the federal funds target range up to 5.25-5.50%.

In other words, back in October 2023, the Fed was already well into a tightening cycle. Commodity prices were already coming down, and measures of inflation were moderating. And the Fed Funds rate was at par with two-year Treasury notes.

Today, commodity prices are soaring. And the Fed hasn’t begun a determined hiking cycle – putting itself way behind the curve. The Fed Funds target range is currently 3.50%-3.75%, while the two-year Treasury yield is 4.67%. That means the Fed is about 100 basis points behind the market’s rate of interest.

What does all this mean? We’re on the cusp of a rate-hiking cycle.

And there are real risks to this cycle because of the size of the national debt. We are entering uncharted waters with the massive size of the coming refundings. Total marketable U.S. Treasury debt outstanding is $31.8 trillion, carrying a weighted-average interest rate of about 3.48%. About 33% of that debt, roughly $10.5 trillion, matures within 12 months. Call it $15 trillion over the next 18 months. So roughly half of the national debt will reprice in the next 18 months.

If rates average 5% (which, again, is behind the curve currently), that will add $220 billion in annual interest expense. That would be a 21% increase to current interest expense ($1 trillion currently). It would also add 12% to the annual deficit.

While important, the bigger issue is how this big increase in interest expense will be paid for. There’s zero chance the government reforms entitlements or cuts military spending. Which means these bigger interest payments will surely be paid for by yet more inflationary government deficit spending. And the deficit is already running at 6% of GDP (gross domestic product).

That will push us into a very dangerous situation. The Fed may not be able to raise rates high enough to stop the inflation this time because our debt stock is now so large relative to GDP that a Paul Volcker-style interest rate-hiking cycle isn’t fiscally survivable like it was in 1980.

These risks are not priced into the market yet and, in fairness, these risks may not materialize for a few more years. However, I do note that Bank of America (BAC) is down 10% in the last month. It’s my best canary in the coal mine stock to gauge interest rate risks, because of its enormous, low-yielding bond portfolio. (Bank of America bought $700 billion in 2% bonds in July of 2020.) As rates go higher, the risks grow that Bank of America will fail because of the losses on these bonds.

My main concern is that this inflationary cycle may be much harder to control, because it’s being driven by factors (entitlement spending, global geopolitics) that aren’t easily constrained. And as I told you yesterday, that kind of macro outlook reminds me very much of the 1973-1974 inflationary period, which didn’t resolve for a decade.

That means our property-and-casualty (P&C) insurance stocks face a very tough outlook.

P&C insurers write the policies that cover your car, your home, and your business against loss. They invest the premiums they collect, called float because it sits in their account between the day you pay and the day a claim gets paid. And insurance companies invest mostly in bonds.

That business model works well when rates and inflation are calm. It comes apart when they spike, for three reasons that hit at once.

  1. Claims get more expensive. It costs more to rebuild a fire-damaged house, replace a wrecked car, or settle a lawsuit when the general price level is rising. State regulators approve premium rate increases with a lag, sometimes a year or more, so claims costs can outrun the premium dollars collected to pay for them. Insurers call this loss-cost inflation. On liability lines, where lawyers and juries set the price, it’s called social inflation: litigation costs and jury awards climbing even faster than the government’s own inflation figures.
  2. The bonds insurers already own lose value. A bond paying 4% is worth less the moment the market can buy a new one paying 6%. That loss shows up immediately on the balance sheet, in book value: the net worth per share that investors use to price insurance stocks in the first place.
  3. The whole stock market’s multiple, the price investors will pay for each dollar of a company’s earnings or net worth, shrinks. When a 10-year Treasury pays 5% with no credit risk, investors demand more from every other asset, including P&C stocks that already trade close to book value. Book value shrinks from the bond losses, and the multiple applied to what’s left shrinks too, so both hits land in the same quarter.

There is one important offset to these risks. As insurance companies’ old, low-coupon bonds mature, insurers reinvest the cash into new bonds paying the higher rate. Thus, investment income rises over the following one to two years, and the stocks’ dividends rise with it, usually with a lag of a year or two behind the rate move itself. But that rebuilding takes years to show up in earnings, while the bond losses and the multiple compression show up the day rates move. The stock falls first, and recovers. If it recovers, it does so on a much longer clock than the dividend does.

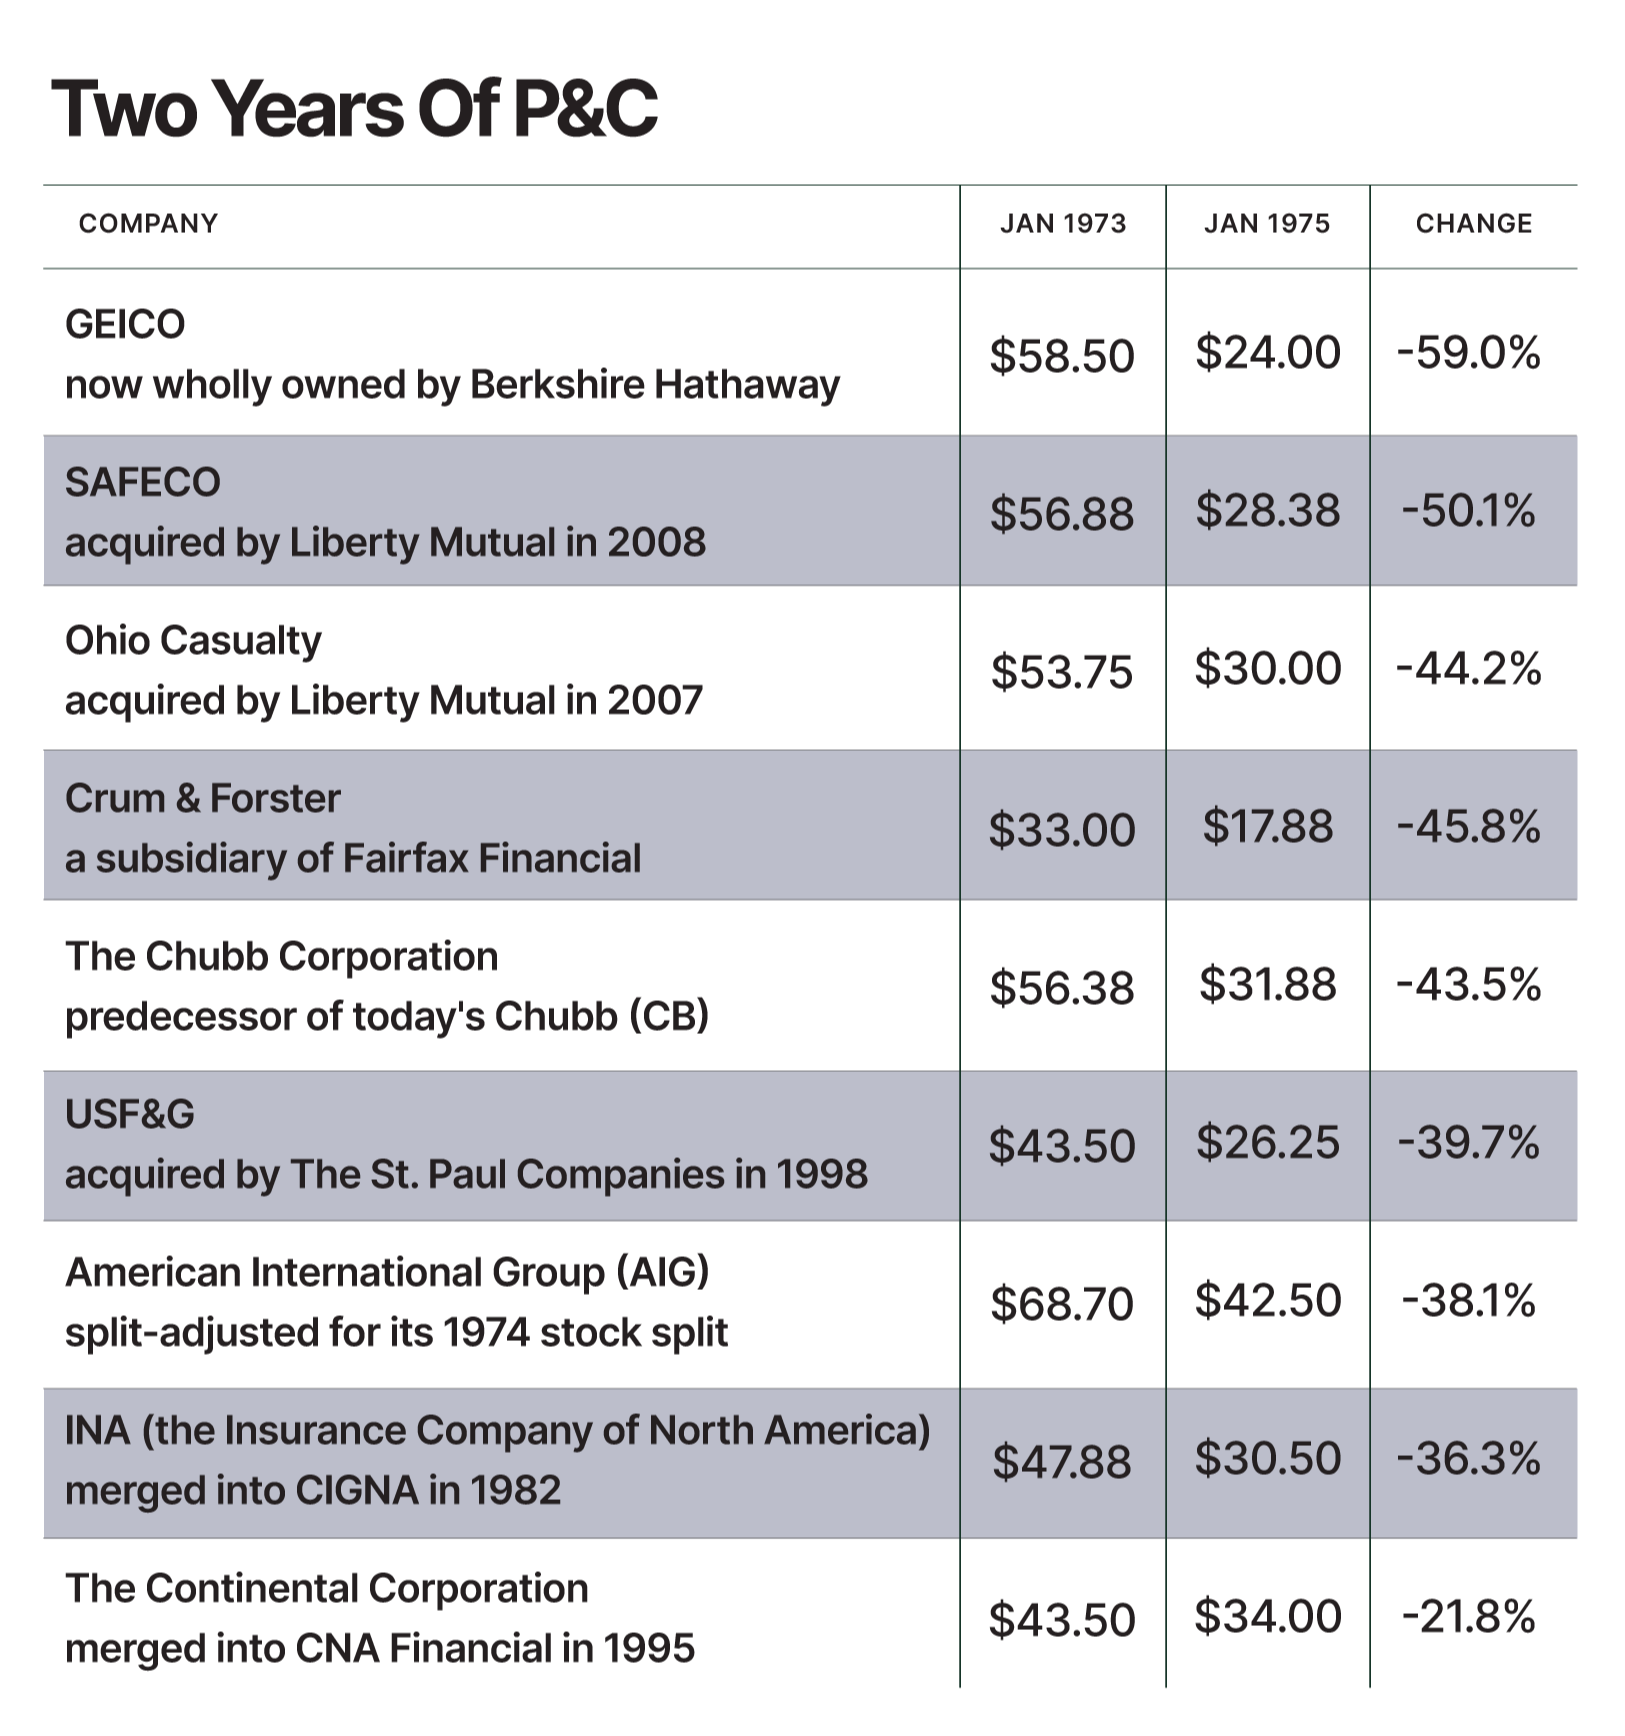
I wanted to know how this unfolded during the 1973-1974 inflation. So I went back to the last time inflation and rates did this to P&C insurers, and I studied their share prices between January 1973 to January 1975, the two years bracketing the oil embargo, the wage-price spiral, and the 1973-74 bear market.

I used a primary source: the Associated Press‘ own NYSE and over-the-counter stock tables, printed daily in newspapers and digitized by the University of North Texas’s Portal to Texas History. We pulled the closing quotes nearest January 1973 and January 1975 for every major P&C insurer that was trading at the time, while we carefully excluded life insurers. Then we cross-checked the prices against Yahoo! Finance.

Here is what a pure-play P&C portfolio did over those two years.

The average decline across those nine names was 42%. The median was 43.5%. The S&P 500 itself fell 41% – from 119.10 to 70.23 – over the same stretch.

P&C insurance, the industry investors buy for safety, fell in line with the broader market, and in several cases fell harder.

We left several well-known names out of that table on purpose. Aetna Life & Casualty, Travelers, CNA Financial, Old Republic International, General Reinsurance, and Kemper all traded through the same period, and all fell too, in some cases much further. CNA Financial dropped 85%, but CNA was carrying a large life and health insurance book and came within a step of insolvency in 1974, when Loews bought 83% of its stock in a rescue. Aetna and Travelers ran life insurance and group health divisions as large as their P&C operations. General Reinsurance wrote reinsurance, not primary policies.

For a conservative investor, our recommendation is simple: stand aside from the P&C insurance industry until interest rates find a ceiling.

For our own track record, we are selling our 25% P&C allocation (“Insurance”) inside Porter’s Permanent Portfolio, in full. The proceeds move into our cash holdings, whose target allocation rises from 25% to 50% of the portfolio. The Lindy stocks (“Equities”) and the gold-and-Bitcoin allocation remain at 25% each.

We acknowledge that this kind of tactical move is risky. Selling triggers taxes and opens us to another risk: selling too soon. I recognize the 10-year U.S. benchmark yield touched 5% in 2007 and again in 2023, and both times it reversed. If that happens a third time, we will look foolish holding half the portfolio in cash while stocks and bonds recover without us.

As always, I simply give you the information I would want if our roles were reversed. In my personal portfolio, I have established a $10 million short position in long-duration bonds. I’m using that to hedge my exposure to the stock market. I’m not suggesting that’s right for you. I’m only explaining that I have a substantial amount of capital at risk based on the very analysis that I’m giving you.

I see a slew of risks that our country hasn’t faced in 50 years: massive and growing deficits, an energy shock now running through the global bond market, and the automatic cost-of-living increases built into Social Security and other entitlement programs. Together they point toward double-digit inflation and a 10-year Treasury yield above 8%, not a retreat below 5%.

Note: This change applies to our own track record, not to every account built around this idea. The Porter & Company Porter Portfolio Index ETF (PCPP) that Tuttle Capital Management runs keeps its rules-based 25% allocation to each of its four sleeves. And your own allocation may not need to change either, depending on your tax situation, your time horizon, and how much of this risk you are already hedging elsewhere.

Our new target allocation, until rates stabilize, is 25% Lindy stocks (high-quality businesses with the pricing power to raise prices as fast as their costs rise), plus 25% gold and Bitcoin. The rest, 50% cash, sits ready so we can redeploy into high-quality stocks and bonds once it looks like the inflation tide is going to recede.

A 10-year Treasury yield at 5% and moving higher doesn’t break a good insurer’s underwriting. But it does change the price investors will pay for it.

Tell me what you think of today’s Journal: porterstansberrydirect@gmail.com

Good investing,

F. Porter Stansberry
Stevenson, Maryland

Presented By: Banyan Hill Publishing

Hall Of Fame Trader Jon Najarian’s Top 5 Trades This Week

For the first time ever, he went live to show folks how it’s possible, but by no means probable, to make more in a single week than most people make in a year.

Starting this week!

He even detailed his FIVE new trade alerts… and gave away the name and ticker of his #1 play during the event.

Click here to watch now and see everything.

Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Banyan Hill is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.


3 Things To Know Before We Go…

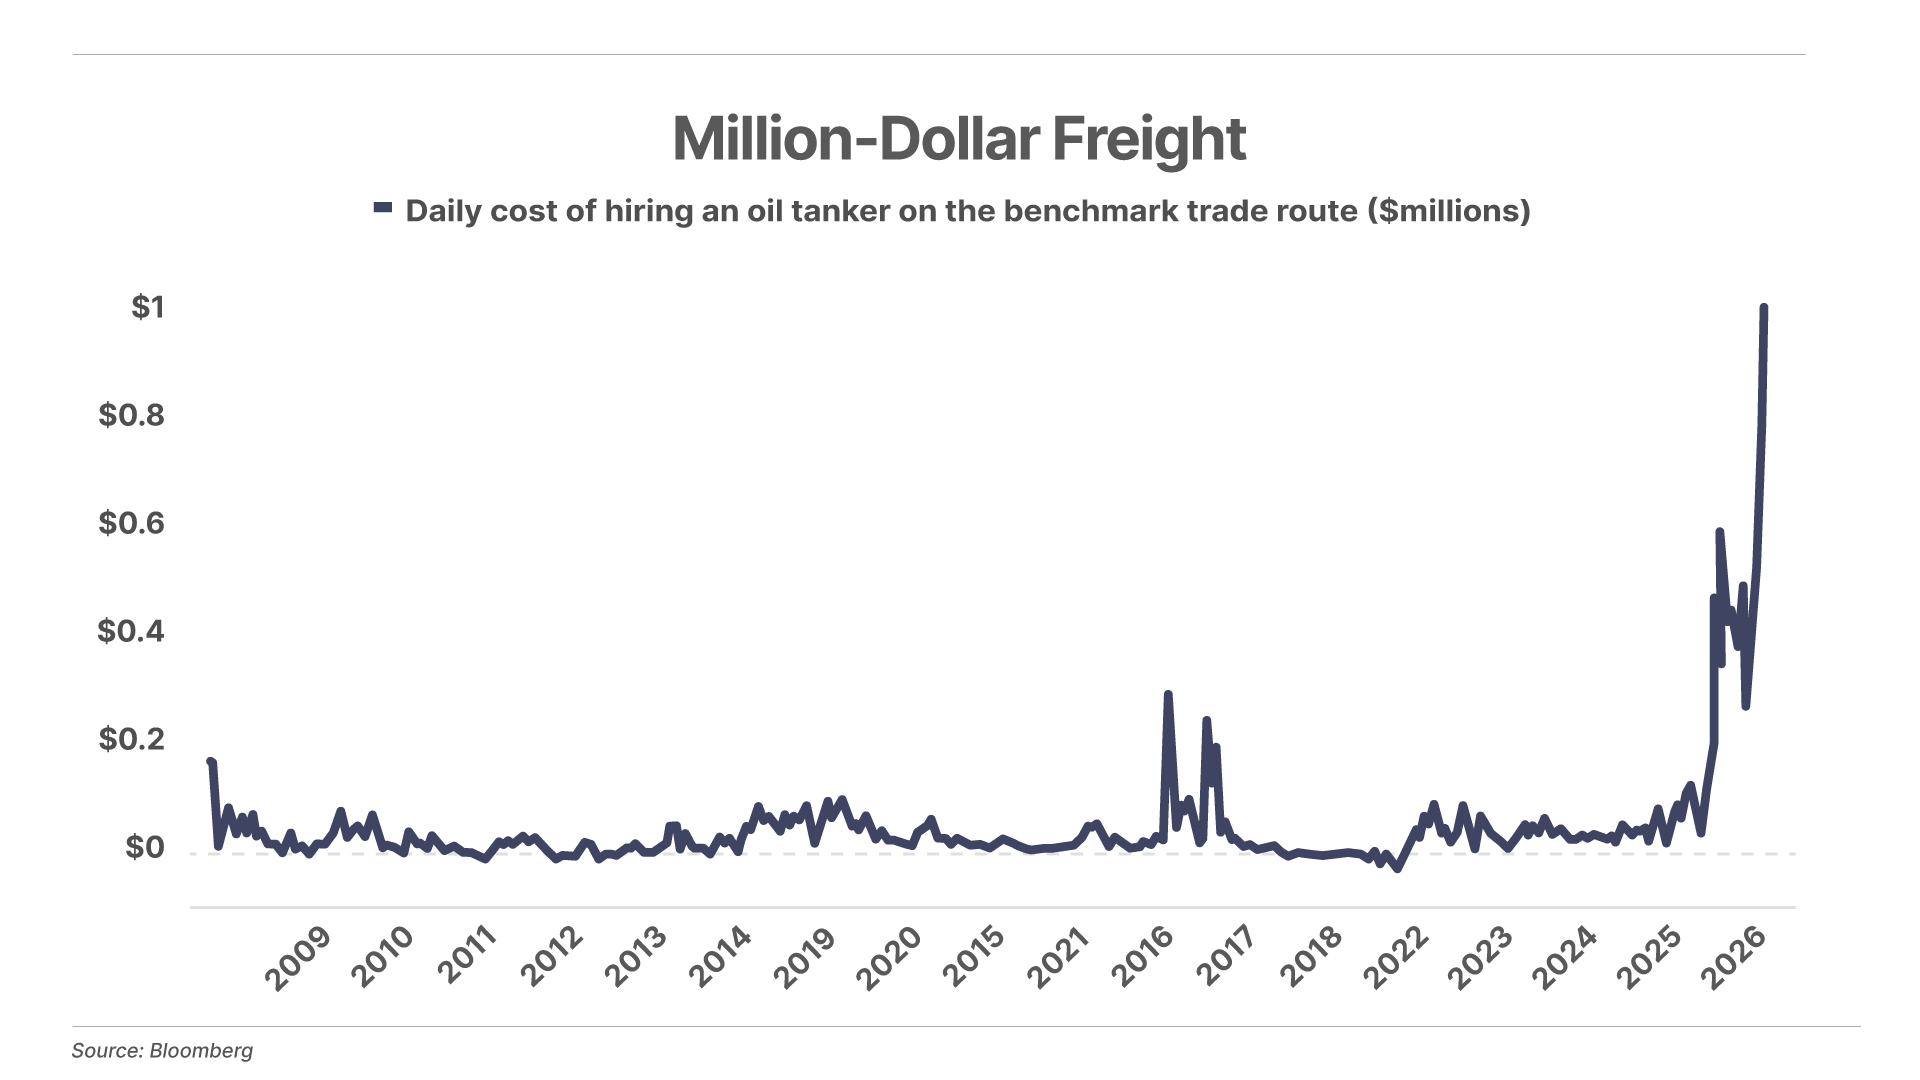
1. Oil tankers now cost more than $1 million a day to hire. The Baltic Exchange, the London body that publishes shipping’s benchmark prices, assessed a supertanker carrying crude oil from the Persian Gulf to China at $1.035 million a day on Monday, the first seven-figure reading in the index’s history. The same route set a record of about $424,000 a day when the Iran war began in late February, and before the war, shipbroker Clarksons expected these ships to average just $75,000 a day. Few owners will currently send a vessel through the Strait of Hormuz. Crude is instead ferried out to the Gulf of Oman and transferred ship-to-ship, and Houthi attacks in the Red Sea are forcing some tankers onto a detour around Africa that adds roughly 30 days to transit. Every extra day at sea removes a ship from the market.

2. Energy executives warn: “Crisis is here.” A growing chorus of energy veterans is sounding the alarm that the energy-supply crisis has officially arrived. This includes Chevron (CVX) CEO Mike Wirth, who noted at an energy conference on Friday that the short-term efforts to mitigate the supply crisis “have largely now played out.” This includes the depletion of strategic stockpiles around the world, which can no longer provide a buffer to offset a record supply deficit. The market is sending the same message, with oil prices now firmly above $100 per barrel and refined products like diesel trading above $200 per barrel.

3. Bond yields break out across the globe. The U.S. 10-year bond yield hit 5.04% overnight, reaching the highest level since 2007. Across the pond, the 10-year bond yields in the UK, France, and Germany have all hit their highest levels since 2009. And in Japan, the 10-year bond yield is now at 3% – the highest level since 1996. With government debts ballooning and a building energy crisis feeding into higher inflation, this will likely keep the upward pressure on borrowing costs globally.


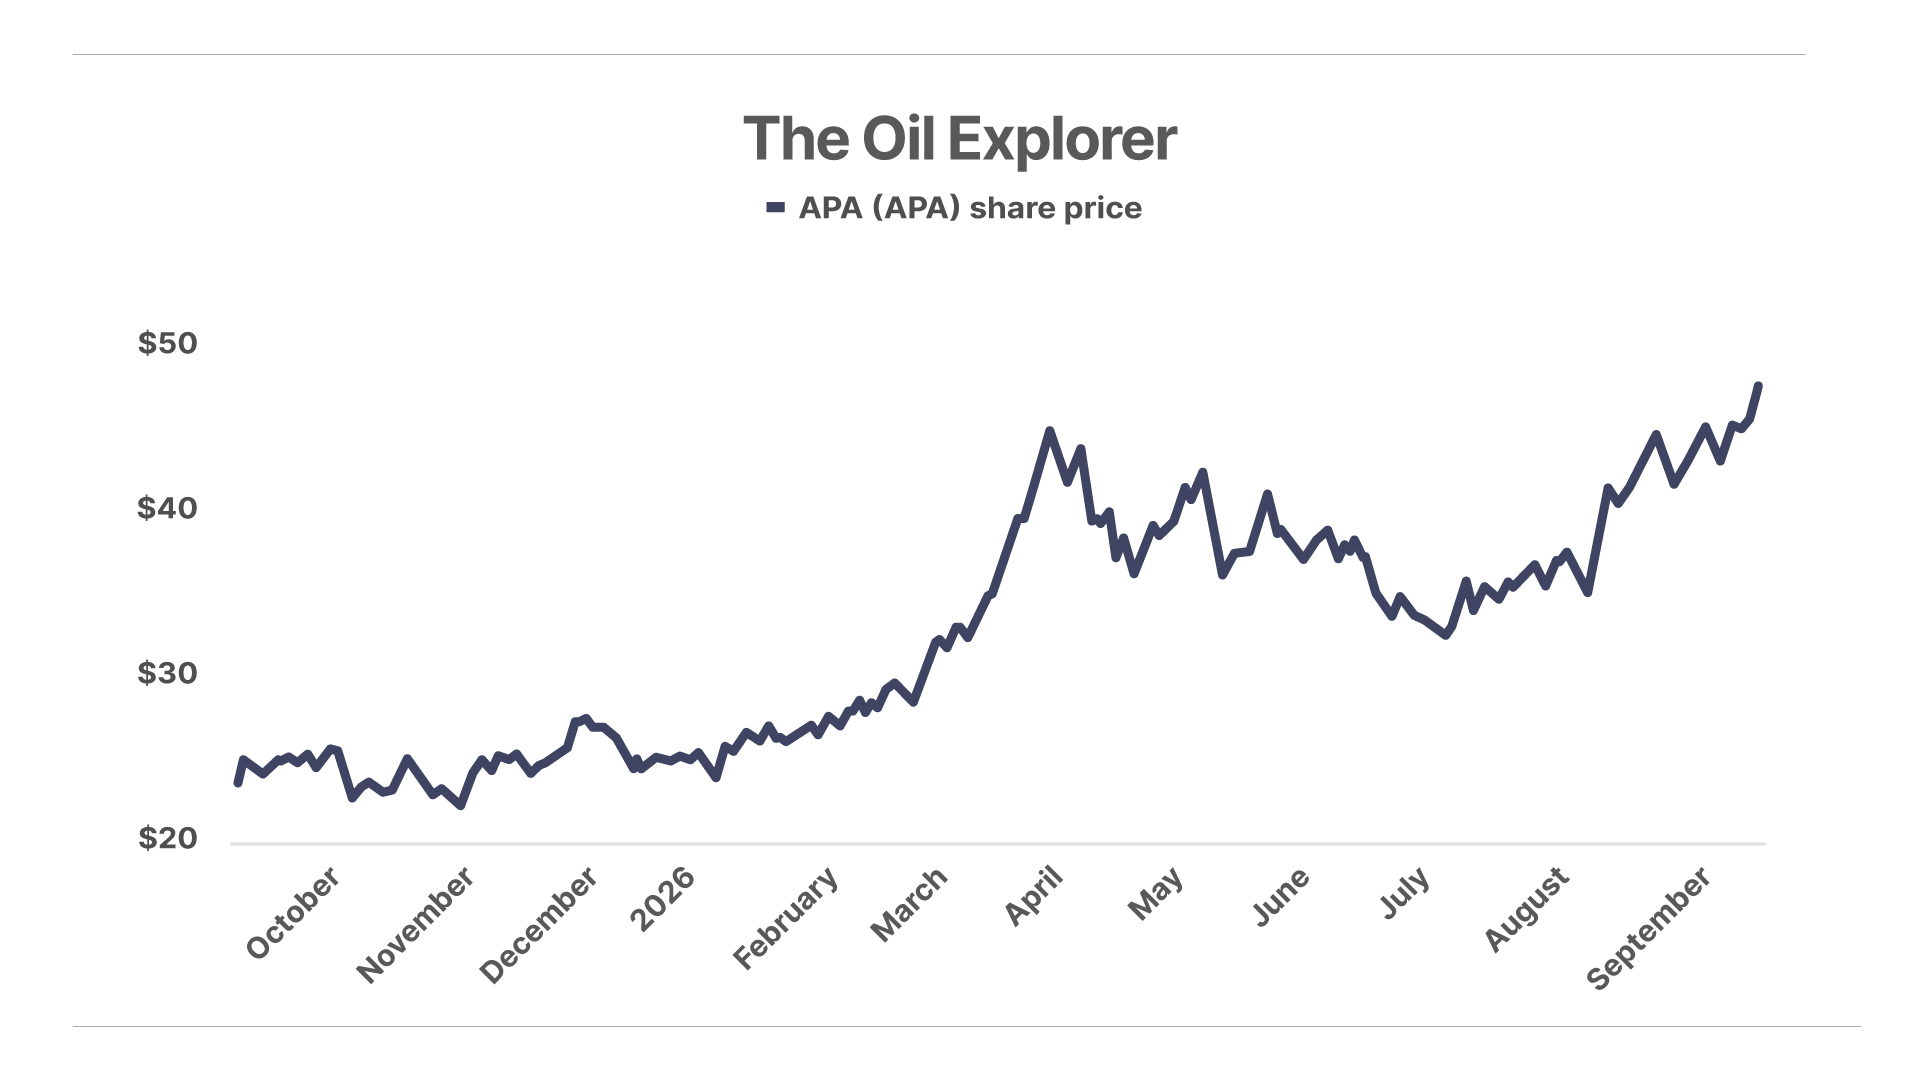
Chart Of The Day… APA (APA)

Shares of oil-exploration firm APA (APA) have soared 105% over the last year and 161% since we recommended them in Porter & Co’s Asymmetry, an advisory offered exclusively to Partner Pass members.


Today’s Poll

Tomorrow, the Federal Open Market Committee (“FOMC”), led by Federal Reserve Chair Kevin Warsh, will vote on future interest rate policies. Markets are pricing in roughly a 90% chance of a 25-basis-point interest rate hike because of a higher-than-expected August consumer price index (“CPI”) report and oil trading above $100 per barrel.
Loading
Please enable JavaScript in your browser to complete this form.

Mailbag

In yesterday’s Journal, Porter wrote that the rise of yields on 10-year Treasuries to 5% will cause inflation to break out – as a result, the Fed will face a choice past Fed Chair Paul Volcker never faced: it will have to choose between fighting inflation and keeping the Treasury solvent.

“The Seventies”

Jim H. writes:

I appreciate the ’70s history, as I lived through it, and the technical explanation that I can understand. Thanks.


“It’s Very Scary”

William S. writes:

Thank you for the advice. It’s very scary. I’ve been investing in gold shares with Garrett Goggin at Golden Portfolio, 40%. I have some in gold coins, 15%, and the rest in cash.


“Thank You So Much”

Thomas V. writes:

I always feel like I’ve learned something whenever I read your commentary. Thank you so much. I’ve been following your work since around 2006 or so and I feel blessed to have found you.


Porter & Co. Market Snapshot

Price Yesterday’s Return Year-to-Date Return
S&P 500 Index $7,619.98 -0.48% 12.2%
Gold per ounce $4,299.64 -0.79% -1.0%
Bitcoin $79,085 2.28% -12.3%
Oil (West Texas Intermediate) per barrel $101.39 -0.84% 78.4%
Berkshire Hathaway (BRK) $771,770.02 0.75% 2.2%
Porter’s Permanent Portfolio – 0.54% 3.8%
The Better Than Berkshire Index – 0.36% 7.0%
Total Return Annual Return
Porter & Co’s Top Ranked* 35.0% 15.9%
Yield Yesterday’s Change Change
Year-to-Date
U.S Treasury 30-Year Yield 5.34% -1 bps 50 bps
Prices as of 4:00 pm ET September 14, 2026 | bps = basis points (or 0.01%)
*A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


Porter & Co. Top Positions

Publication Ticker Description Total Return
Biotechnology QURE uniQure 237%
Biotechnology SGMT Sagimet Biosciences 202%
Complete Investor BTC/USD Bitcoin 189%
Biotechnology ROIV Roivant Sciences 181%
Complete Investor BWXT BWX Technologies 162%
Biotechnology TGTX TG Therapeutics 152%
Complete Investor PM Philip Morris 141%
Complete Investor SKWD Skyward Specialty Insurance 137%
Biotechnology SGMT Sagimet Biosciences 135%
Biotechnology NUVB Nuvation Bio 134%
Prices as of 4:00 pm ET September 14, 2026


Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

The post Important Allocation Update appeared first on Porter & Co..

  •  

Trading Club Pro Update – Week Of August 17, 2026

Editor’s note: For the month of August, we’re shifting the publication schedule for The Trading Club to bi-weekly updates. We will post our next update on September 4, after which we’ll return to our regular weekly publishing schedule.


The value of The Trading Club Pro tracking portfolio settled at $114,290 as of Thursday, August 20 – up 14.3% since the June 22, 2026, inception date (see the detailed portfolio snapshot below). We made no trades this week.

In this issue we provide an update on a covered-call position expiring today, review the latest earnings report from one of our software holdings, and address a recent subscriber question in the “Mailbag.”

Update On LandBridge Covered Call Expiring Today

The following covered-call contract on our 100-share position in West Texas land leasing company LandBridge (NYSE: LB) is set to expire at the close of trading today:

One LandBridge (NYSE: LB) $75 covered call, expiring August 21, 2026

No action is needed as we plan to continue holding the position through today’s expiration date.

With shares of LandBridge trading just under $90, the option is likely to expire in-the-money at the close of trading today. In this scenario, our shares will get called away, meaning our broker will automatically sell our 100-share position at the $75 strike price after the close of trading today.

Conversely, if shares fall below the $75 strike price by the close of trading today, the option will expire out-of-the-money and we will retain our 100-share position.

Either scenario is an acceptable outcome for us. Let’s briefly review the latest quarterly results and the valuation of the business that leads us to this conclusion.

LandBridge reported excellent Q2 results on August 5, including revenue of $67 million, up 41% year-on-year (“YOY”), while net income increased 68% YOY to $31 million. The company is benefitting from the resumption of drilling activity across the Permian basin, as the major drillers like ExxonMobil (XOM) and Chevron (CVX) add new drilling rigs in response to higher oil prices. And with oil production on the rise across the Permian, this is leading to greater volumes of produced water, translating into higher royalty payments for LandBridge.

Based on the steady growth in drilling activity, the company reiterated its 2026 outlook for EBITDA (earnings before interest, taxes, depreciation, and amortization) to reach $220 million. It also announced advanced discussions with seven counterparties representing over 10 gigawatts of power and data center capacity for land leasing deals. LandBridge CFO Scott McNeely characterized these as projects with signed documents undergoing diligence or agreements currently under negotiation, rather than preliminary outreach. He also noted that the counterparties include a mix of hyperscalers, engineering, and procurement companies, as well as power generation businesses.

Management expects that “multiple” of these negotiations could convert into firm leases with revenue beginning to flow in by the end of next year, although no formal deals have yet been announced. But that hasn’t stopped the market from beginning to price in this potential future upside, as the shares have enjoyed a significant valuation re-rating in recent weeks.

At just under $90 per share, LandBridge trades with a $7.9 billion enterprise value (“EV”), putting its valuation at a relatively rich 36x EV/EBITDA ratio. That’s a 15% premium to Texas Pacific Land (TPL), currently trading at 31x EV/EBITDA, with both companies growing at similar rates.

While the business is performing well, we are ok with taking profits on the stock. At today’s stretched valuation, we believe investors are paying up for shares based on the promise of future data center deals that have yet to come to fruition. That presents a risk of a valuation de-rating in the event that these deals fail to materialize, or take longer to begin generating revenue than the market is currently pricing in. For now, we’ll continue monitoring the story and may re-enter the position should the opportunity present itself.

In the meantime, we plan on reinvesting a portion of the freed-up cash we expect to receive if the shares close above the covered-call option strike price today.

And for that, we turn to the latest opportunity provided by what we view as an over-reaction to a minor hiccup in the quarterly report from one of our favorite software stocks.

Cellebrite’s Minor Sales Hiccup Creates Buying Opportunity

Digital forensics platform Cellebrite (Nasdaq: CLBT) delivered modestly disappointing Q2 results on August 13. The company generated $131 million in Q2 revenue, or just shy of the $132 million analysts estimated, while earnings per share of $0.11 was in line with expectations. Management also reduced its forecasted revenue for the full year down by 3% to $555 (at the midpoint of the guidance range). However, despite the revenue downgrade, management increased its forecast for adjusted EBITDA up by 3% to $156 million for 2026.

The primary cause of the sales weakness was attributed to a slower pace of deal closing for the company’s cloud-based software offerings, which were stymied by unexpected regulatory steps. This resulted in a slightly elongated sales cycle, although no deals in the company’s sales pipeline were lost, as we’ll discuss in greater detail below.

In isolation, we viewed the revenue weakness in Q2 and downgrade in management’s outlook as modest disappointments. But the company also announced the unexpected retirement of CEO Tom Hogan, to be replaced by the former President of Products and Technology, Shiv Ramji, effective immediately.

While it’s never good to see an earnings miss followed by a guidance cut, it’s even worse when accompanied by a sudden shakeup in leadership. We suspect it was this confluence of negative bits of news that drove the stock down 30% following the report, with some investors likely viewing the sudden CEO change as evidence of deeper problems within the company. However, after looking closely through the numbers and the management commentary from the earnings call, we believe the share price sell off was an extreme over-reaction.

Let’s start by setting the stage for the regulatory obstacles the company is facing. As we’ve written about previously, in order to legally sell cloud-based software to any agency of the U.S. federal government, the vendor must first secure approval from the Federal Risk and Authorization Management Program (“FedRAMP”).

Cellebrite secured FedRAMP approval on May 6, and management expected an immediate boost in sales from a healthy backlog of customer demand for its new cloud-based offerings starting in Q2. However, even after securing this approval, the company faced a new and evolving set of requirements that involved “multiple waivers, security reviews, and other other administrative approvals” in finalizing several of its large-scale cloud deals in Q2. CFO David Barter provided the following commentary on the earnings call that put the scope of these delayed deals into perspective:

When you put the quarter in context, we signed and took down orders probably well north of 1,000. In the end, it kind of came down to four, and it was four that crossed the line, and it was four that involved cloud. One in particular involved a platform. You might recall one of these deals we alluded to last time where they actually called us before we had FedRAMP approval. Even they were a little bit surprised about the changing procurement requirements when you get into cloud and AI and the approvals that we had to secure.

In other words, we’re talking about just four deals that contributed to the unexpected weakness in Q2. And importantly, none of these deals were lost, but merely delayed. Chief Revenue Officer Marcus Jewell noted on the call that $4 million worth of sales that were delayed in Q2 have since been closed as of the day of the conference call.

Now admittedly, a slower pace of deal closings will act as a modest drag on the rate of revenue growth over the next couple of quarters. However, the impact here should also be relatively muted over the long-run, with management estimating that the sales cycle was elongated by approximately six weeks for its cloud-based software sales.

Even with this slower sales cycle, the 3% decline in full year revenue for 2026 is far from a thesis-killer, with the company still on track to increase revenue by 17% this year at the midpoint of its updated guidance.

The bottom line is that we saw nothing in the report or in management commentary that should lead to any meaningful impairment to the long-term outlook for the business. Conversely, we saw signs of ongoing strength in the core business from the improving net revenue retention rate, which increased by two percentage points over Q1 to 117%. This tells us that the retention and expansion within the existing customer base actually improved sequentially, even as the growth rate from new sales slowed down from an elongated sales cycle.

We’ll also point out that there’s a flipside to the stringent regulatory requirements Cellebrite faces in selling cloud-based software to government agencies: it further widens the competitive moat around the business. Cellebrite is the only company among its peers that has achieved FedRAMP approval, which management described as a “long and tortuous process” on the Q2 earnings call. So as difficult as it is for the incumbent (Cellebrite) to navigate this complex regulatory environment, this also creates an incredibly high barrier to entry for smaller rivals that have fewer resources, and less of a track record in working with regulators, to overcome.

Meanwhile, the final thing we’ll point out is that ultimately its earnings and free cash flow (“FCF”) that determine the worth of a business, not the top-line revenue growth rate. And on this last point, we actually saw an improving outlook from the Q2 report, as management upped its earnings outlook by 3% for the full year while reiterating its 30% FCF margin target. This is a result of the company successfully scaling up the business while keeping its costs stable, including headcount – which remained unchanged through Q2 relative to the end of 2025, even as the business grows at mid-teens rates. Looking ahead, management noted that it is “increasingly optimistic about our potential to deliver the next step-up in our profitability and FCF in 2027 as we demonstrate that we can operate the business without material expansion of the headcount.”

Putting it all together, we see a business on track to increase revenue at a healthy mid-teens annual rate while generating approximately $167 million in FCF this year. At a recent price of around $11, the business trades at a market capitalization of $2.8 billion, with a pristine balance sheet that contains just over $500 million in net cash. That translates into an EV of $2.3 billion, and a valuation ratio of just under 14x EV-to-FCF compared with over 33x for the S&P 500.

Given Cellebrite’s dominant competitive position, wide structural moat, and high cash flow margins, we see no reason why this business should trade at a market discount. We suspect investors have grown frustrated with the shares after a year and a half of setbacks, starting with DOGE-related fears in early 2025, the perceived AI threat to all things software earlier this year, and now a guidance cut and CEO reshuffling. But simply looking at the objective business fundamentals, we see a deeply discounted stock where the underlying customer base remains sticky and a solid growth outlook.

Assuming the worst is behind it and the company achieves the latest guidance set out by management, we see no reason why the shares won’t compound in line with revenue growth going forward, at a high-teens rate. Plus, we also see significant upside potential from the valuation re-rating higher towards a market multiple, which would more than double the share price alone.

Our plan is to take advantage of this opportunity to increase our position in Cellebrite, using a portion of the freed-up cash from the LandBridge option expiration, assuming the option expires in-the-money at the close of trading today. That cash will be available for investment on Monday morning, at which point we’ll issue a new trade alert.

Next, we’ll show each position in the portfolio broken down by trade type.

Portfolio Review

The table below shows all current holdings as of the close of trading on Thursday, August 20:
A few notes on how to read and interpret this portfolio table.

Please pay special attention to the “Action” column, where we specify whether each trade is a “buy” or “sell to open” transaction.

Next, the position size for each trade is equal to the current value of the position, with the exception of the cash-secured puts. In the case of the cash-secured puts, we define the position size as the total value of our future commitment to purchase 100 shares for each contract. This number is calculated as follows:

Position size = number of contracts x 100 x put strike price

We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade.

For example, in the case of the WaterBridge Infrastructure (NYSE: WBI) $30 puts, the position size equals 2 x 100 x $30 = $6,000. We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade. It’s commonly referred to as the “notional value” of the trade.

To see the current profit/loss across each open position and other details, please see the live snapshot of our tracking portfolio at the end of this update.

We have compiled a summary overview of the latest quarterly trades released on June 22, which you can find here. Since then, we have recommended the additional trades listed below:

  1. On July 17, we recommended purchasing shares of Novo Nordisk (NYSE: NVO), which you can find here
  2. On July 21, we recommended purchasing shares of Hims & Hers Health (NYSE: HIMS), and we provided the analysis for the company on July 24, which you can find here

As a reminder, we calculate the leverage ratio using the following formula:

Leverage ratio = total long exposure/portfolio equity value

We define total long exposure as the sum of all long positions, including uncovered stocks, covered stocks, cash-secured puts, and option purchases. In the current portfolio, as of Wednesday’s close, these values were as follows (note: we show each value in our portfolio table below):

  • Uncovered stocks: $75,855
  • Covered stocks: $27,345 (netting out the underlying stock value against the covered-call value)
  • Put sales: $41,500 (this “notional value” is the value of stock we’ve committed to purchasing)
  • Long options positions: $942

Adding up all of these values gives us $145,642 of total long exposure in our current tracking portfolio. We then divide this number into our account equity of $114,290 to arrive at a 127% leverage ratio – well within our self-prescribed limit of 150%.

Next, we address a recent question from the “Mailbag”


Mailbag

Please note that nothing we write should ever be considered individual investment advice, as we are not licensed to provide such guidance. This material is for educational purposes only, and we recommend consulting with a licensed financial advisor for individual investment advice.

Today’s “Mailbag” letter comes from a subscriber with a question about our position in Celsius in the context of the recent sell recommendation of the stock in the Porter & Co. flagship advisory, Complete Investor.

I received the alert to sell Celsius Holdings (CELH) in Complete Investor, but there was no recommendation for the holdings in The Trading Club. Is Celsius still a recommended hold in The Trading Club, and if not, is the recommendation to close the options positions?

Ross Comment: Yes, we continue recommending holding the existing positions in Celsius Holdings (Nasdaq: CELH) in The Trading Club for the reasons described in our prior update on August 7.

With different analysts running the different publications at Porter & Co, we will sometimes have differing opinions on the same stocks. Plus, the option trading strategies in The Trading Club means we will sometimes have slightly different objectives versus a publication like Complete Investor that’s catered toward a buy-and-hold strategy.

For now, we’re happy to stick with our current strategy of selling options on Celsius, as we believe the downside risk is limited at current prices, while the elevated option premiums offer an attractive source of steady income potential.

If you have any questions or feedback, The Trading Club Forum is the best chance to get a quick response from our team.

Alternatively, you can always email us at mailbag@porterandcompanyresearch.com.

Good investing,

Ross Hendricks
Porter & Co.
The post Trading Club Pro Update – Week Of August 17, 2026 appeared first on Porter & Co..

  •  

Trading Club Update – Week Of August 17, 2026

Editor’s note: For the month of August, we’re shifting the publication schedule for The Trading Club to bi-weekly updates. We will post our next update on September 4, after which we’ll return to our regular weekly publishing schedule.


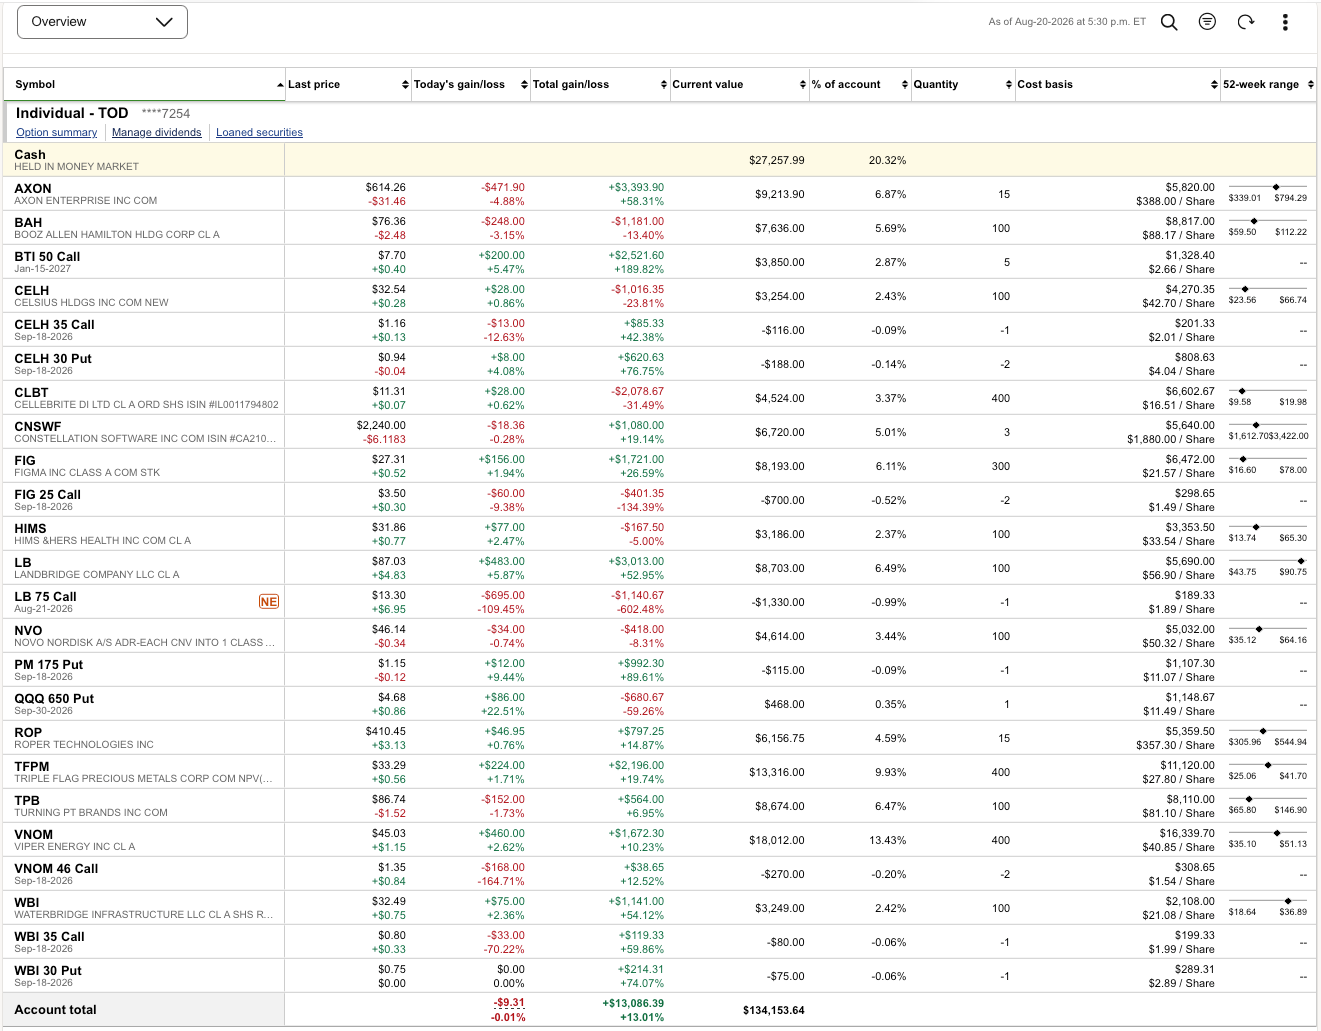
The value of The Trading Club tracking portfolio settled at $134,153 as of Thursday, August 20 – up 34.2% since the May 30, 2025, inception date (see the detailed portfolio snapshot below). We made no trades this week.

In this issue we provide an update on a covered-call position expiring today, review the latest earnings report from one of our software holdings, and address a recent subscriber question in the “Mailbag.”

Update On LandBridge Covered Call Expiring Today

The following covered-call contract on our 100-share position in West Texas land leasing company LandBridge (NYSE: LB) is set to expire at the close of trading today:

One LandBridge (NYSE: LB) $75 covered call, expiring August 21, 2026

No action is needed as we plan to continue holding the position through today’s expiration date.

With shares of LandBridge trading just under $90, the option is likely to expire in-the-money at the close of trading today. In this scenario, our shares will get called away, meaning our broker will automatically sell our 100-share position at the $75 strike price after the close of trading today.

Conversely, if shares fall below the $75 strike price by the close of trading today, the option will expire out-of-the-money and we will retain our 100-share position.

Either scenario is an acceptable outcome for us. Let’s briefly review the latest quarterly results and the valuation of the business that leads us to this conclusion.

LandBridge reported excellent Q2 results on August 5, including revenue of $67 million, up 41% year-on-year (“YOY”), while net income increased 68% YOY to $31 million. The company is benefitting from the resumption of drilling activity across the Permian basin, as the major drillers like ExxonMobil (XOM) and Chevron (CVX) add new drilling rigs in response to higher oil prices. And with oil production on the rise across the Permian, this is leading to greater volumes of produced water, translating into higher royalty payments for LandBridge.

Based on the steady growth in drilling activity, the company reiterated its 2026 outlook for EBITDA (earnings before interest, taxes, depreciation, and amortization) to reach $220 million. It also announced advanced discussions with seven counterparties representing over 10 gigawatts of power and data center capacity for land leasing deals. LandBridge CFO Scott McNeely characterized these as projects with signed documents undergoing diligence or agreements currently under negotiation, rather than preliminary outreach. He also noted that the counterparties include a mix of hyperscalers, engineering, and procurement companies, as well as power generation businesses.

Management expects that “multiple” of these negotiations could convert into firm leases with revenue beginning to flow in by the end of next year, although no formal deals have yet been announced. But that hasn’t stopped the market from beginning to price in this potential future upside, as the shares have enjoyed a significant valuation re-rating in recent weeks.

At just under $90 per share, LandBridge trades with a $7.9 billion enterprise value (“EV”), putting its valuation at a relatively rich 36x EV/EBITDA ratio. That’s a 15% premium to Texas Pacific Land (TPL), currently trading at 31x EV/EBITDA, with both companies growing at similar rates.

While the business is performing well, we are ok with taking profits on the stock. At today’s stretched valuation, we believe investors are paying up for shares based on the promise of future data center deals that have yet to come to fruition. That presents a risk of a valuation de-rating in the event that these deals fail to materialize, or take longer to begin generating revenue than the market is currently pricing in. For now, we’ll continue monitoring the story and may re-enter the position should the opportunity present itself.

In the meantime, we plan on reinvesting a portion of the freed-up cash we expect to receive if the shares close above the covered-call option strike price today.

And for that, we turn to the latest opportunity provided by what we view as an over-reaction to a minor hiccup in the quarterly report from one of our favorite software stocks.

Cellebrite’s Minor Sales Hiccup Creates Buying Opportunity

Digital forensics platform Cellebrite (Nasdaq: CLBT) delivered modestly disappointing Q2 results on August 13. The company generated $131 million in Q2 revenue, or just shy of the $132 million analysts estimated, while earnings per share of $0.11 was in line with expectations. Management also reduced its forecasted revenue for the full year down by 3% to $555 (at the midpoint of the guidance range). However, despite the revenue downgrade, management increased its forecast for adjusted EBITDA up by 3% to $156 million for 2026.

The primary cause of the sales weakness was attributed to a slower pace of deal closing for the company’s cloud-based software offerings, which were stymied by unexpected regulatory steps. This resulted in a slightly elongated sales cycle, although no deals in the company’s sales pipeline were lost, as we’ll discuss in greater detail below.

In isolation, we viewed the revenue weakness in Q2 and downgrade in management’s outlook as modest disappointments. But the company also announced the unexpected retirement of CEO Tom Hogan, to be replaced by the former President of Products and Technology, Shiv Ramji, effective immediately.

While it’s never good to see an earnings miss followed by a guidance cut, it’s even worse when accompanied by a sudden shakeup in leadership. We suspect it was this confluence of negative bits of news that drove the stock down 30% following the report, with some investors likely viewing the sudden CEO change as evidence of deeper problems within the company. However, after looking closely through the numbers and the management commentary from the earnings call, we believe the share price sell off was an extreme over-reaction.

Let’s start by setting the stage for the regulatory obstacles the company is facing. As we’ve written about previously, in order to legally sell cloud-based software to any agency of the U.S. federal government, the vendor must first secure approval from the Federal Risk and Authorization Management Program (“FedRAMP”).

Cellebrite secured FedRAMP approval on May 6, and management expected an immediate boost in sales from a healthy backlog of customer demand for its new cloud-based offerings starting in Q2. However, even after securing this approval, the company faced a new and evolving set of requirements that involved “multiple waivers, security reviews, and other other administrative approvals” in finalizing several of its large-scale cloud deals in Q2. CFO David Barter provided the following commentary on the earnings call that put the scope of these delayed deals into perspective:

When you put the quarter in context, we signed and took down orders probably well north of 1,000. In the end, it kind of came down to four, and it was four that crossed the line, and it was four that involved cloud. One in particular involved a platform. You might recall one of these deals we alluded to last time where they actually called us before we had FedRAMP approval. Even they were a little bit surprised about the changing procurement requirements when you get into cloud and AI and the approvals that we had to secure.

In other words, we’re talking about just four deals that contributed to the unexpected weakness in Q2. And importantly, none of these deals were lost, but merely delayed. Chief Revenue Officer Marcus Jewell noted on the call that $4 million worth of sales that were delayed in Q2 have since been closed as of the day of the conference call.

Now admittedly, a slower pace of deal closings will act as a modest drag on the rate of revenue growth over the next couple of quarters. However, the impact here should also be relatively muted over the long-run, with management estimating that the sales cycle was elongated by approximately six weeks for its cloud-based software sales.

Even with this slower sales cycle, the 3% decline in full year revenue for 2026 is far from a thesis-killer, with the company still on track to increase revenue by 17% this year at the midpoint of its updated guidance.

The bottom line is that we saw nothing in the report or in management commentary that should lead to any meaningful impairment to the long-term outlook for the business. Conversely, we saw signs of ongoing strength in the core business from the improving net revenue retention rate, which increased by two percentage points over Q1 to 117%. This tells us that the retention and expansion within the existing customer base actually improved sequentially, even as the growth rate from new sales slowed down from an elongated sales cycle.

We’ll also point out that there’s a flipside to the stringent regulatory requirements Cellebrite faces in selling cloud-based software to government agencies: it further widens the competitive moat around the business. Cellebrite is the only company among its peers that has achieved FedRAMP approval, which management described as a “long and tortuous process” on the Q2 earnings call. So as difficult as it is for the incumbent (Cellebrite) to navigate this complex regulatory environment, this also creates an incredibly high barrier to entry for smaller rivals that have fewer resources, and less of a track record in working with regulators, to overcome.

Meanwhile, the final thing we’ll point out is that ultimately its earnings and free cash flow (“FCF”) that determine the worth of a business, not the top-line revenue growth rate. And on this last point, we actually saw an improving outlook from the Q2 report, as management upped its earnings outlook by 3% for the full year while reiterating its 30% FCF margin target. This is a result of the company successfully scaling up the business while keeping its costs stable, including headcount – which remained unchanged through Q2 relative to the end of 2025, even as the business grows at mid-teens rates. Looking ahead, management noted that it is “increasingly optimistic about our potential to deliver the next step-up in our profitability and FCF in 2027 as we demonstrate that we can operate the business without material expansion of the headcount.”

Putting it all together, we see a business on track to increase revenue at a healthy mid-teens annual rate while generating approximately $167 million in FCF this year. At a recent price of around $11, the business trades at a market capitalization of $2.8 billion, with a pristine balance sheet that contains just over $500 million in net cash. That translates into an EV of $2.3 billion, and a valuation ratio of just under 14x EV-to-FCF compared with over 33x for the S&P 500.

Given Cellebrite’s dominant competitive position, wide structural moat, and high cash flow margins, we see no reason why this business should trade at a market discount. We suspect investors have grown frustrated with the shares after a year and a half of setbacks, starting with DOGE-related fears in early 2025, the perceived AI threat to all things software earlier this year, and now a guidance cut and CEO reshuffling. But simply looking at the objective business fundamentals, we see a deeply discounted stock where the underlying customer base remains sticky and a solid growth outlook.

Assuming the worst is behind it and the company achieves the latest guidance set out by management, we see no reason why the shares won’t compound in line with revenue growth going forward, at a high-teens rate. Plus, we also see significant upside potential from the valuation re-rating higher towards a market multiple, which would more than double the share price alone.

Our plan is to take advantage of this opportunity to increase our position in Cellebrite, using a portion of the freed-up cash from the LandBridge option expiration, assuming the option expires in-the-money at the close of trading today. That cash will be available for investment on Monday morning, at which point we’ll issue a new trade alert.

Next, we’ll show each position in the portfolio broken down by trade type.

Portfolio Review

The table below shows all current holdings as of the close of trading on Thursday, August 20:

A few notes on how to read and interpret this portfolio table.

Please pay special attention to the “Action” column, where we specify whether each trade is a “buy” or “sell to open” transaction.

Next, the position size for each trade is equal to the current value of the position, with the exception of the cash-secured puts. In the case of the cash-secured puts, we define the position size as the total value of our future commitment to purchase 100 shares for each contract. This number is calculated as follows:

Position size = number of contracts x 100 x put strike price

We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade.

For example, in the case of the Celsius Holdings (Nasdaq: CELH) $30 puts, the position size equals 2 x 100 x $30 = $6,000. We use this number because it accurately reflects our total capital commitment, and thus our total risk exposure on the trade.

To see the current profit/loss across each open position and other details, please see the live snapshot of our tracking portfolio at the end of this update.

We have compiled a summary overview of the latest quarterly trades released on June 22, which you can find here. Since then, we have recommended the additional trades listed below:

  1. On July 17, we recommended purchasing shares of Novo Nordisk (NYSE: NVO), which you can find here
  2. On July 21, we recommended purchasing shares of Hims & Hers Health (NYSE: HIMS), and we provided the analysis for the company on July 24, which you can find here

Next, we address a recent question from the “Mailbag”


Mailbag

Please note that nothing we write should ever be considered individual investment advice, as we are not licensed to provide such guidance. This material is for educational purposes only, and we recommend consulting with a licensed financial advisor for individual investment advice.

Today’s “Mailbag” letter comes from a subscriber with a question about our position in Celsius in the context of the recent sell recommendation of the stock in the Porter & Co. flagship advisory, Complete Investor.

I received the alert to sell Celsius Holdings (CELH) in Complete Investor, but there was no recommendation for the holdings in The Trading Club. Is Celsius still a recommended hold in The Trading Club, and if not, is the recommendation to close the options positions?

Ross Comment: Yes, we continue recommending holding the existing positions in Celsius Holdings (Nasdaq: CELH) in The Trading Club for the reasons described in our prior update on August 7.

With different analysts running the different publications at Porter & Co, we will sometimes have differing opinions on the same stocks. Plus, the option trading strategies in The Trading Club means we will sometimes have slightly different objectives versus a publication like Complete Investor that’s catered toward a buy-and-hold strategy.

For now, we’re happy to stick with our current strategy of selling options on Celsius, as we believe the downside risk is limited at current prices, while the elevated option premiums offer an attractive source of steady income potential.

If you have any questions or feedback, The Trading Club Forum is the best chance to get a quick response from our team.

Alternatively, you can always email us at mailbag@porterandcompanyresearch.com.

Good investing,

Ross Hendricks
Porter & Co.


The post Trading Club Update – Week Of August 17, 2026 appeared first on Porter & Co..

  •  
❌