❌

Normal view

  • ✇Market Wise
  • Stocks for investing in a massive new AI trend Brian Hunt
    Today’s issue in preview: Stocks for investing in a massive new AI trend This AI trade has turned into a moneymaking juggernaut This industry has massive upside potential. How to trade it from here Learn our Top Themes to buy now Stocks for investing in a massive new AI trend Credit: BlackJack3D To track and trade the world’s strongest business and technology trends, our Global Trend Tracker monitors over 170 industry groups, over 30 proprietary thematic indexes, over 70 ETFs, and ov
     

Stocks for investing in a massive new AI trend

6 October 2026 at 12:00

Today’s issue in preview:

  • Stocks for investing in a massive new AI trend

  • This AI trade has turned into a moneymaking juggernaut

  • This industry has massive upside potential. How to trade it from here

  • Learn our Top Themes to buy now


Stocks for investing in a massive new AI trend

Image

Credit: BlackJack3D

To track and trade the world’s strongest business and technology trends, our Global Trend Tracker monitors over 170 industry groups, over 30 proprietary thematic indexes, over 70 ETFs, and over 3,500 public stocks.

This trend-tracking system serves as our “all-seeing eye” – an early-detection system that tracks money flows and shifts in the market climate.

It is designed to identify powerful trends early in their lifespans, giving us the opportunity to capitalize on them before they become widely recognized. A business, product, or technology trend can barely twitch without being picked up by our Global Trend Tracker.

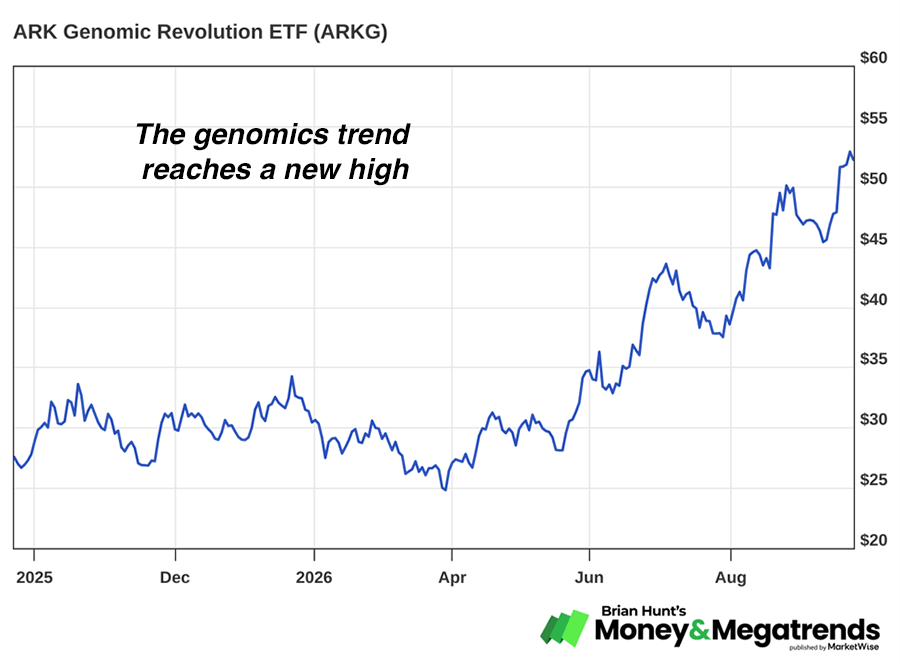
Today, one of the powerful messages our trend tracker is sending is that the genomics theme is booming… and our longstanding recommendation to be long this megatrend is paying off massively.

This week, genomics-related companies and ETFs reaching important new highs include:

  • Illumina (ILMN) is a leader in DNA sequencing systems and genomic analysis tools used in research, diagnostics, and precision medicine.

  • Guardant Health (GH), which develops blood-based cancer tests for early detection, treatment selection, recurrence monitoring, and precision oncology.

  • Twist Bioscience (TWST) is a manufacturer of synthetic DNA products used in drug discovery, diagnostics, genetic research, and next-generation sequencing.

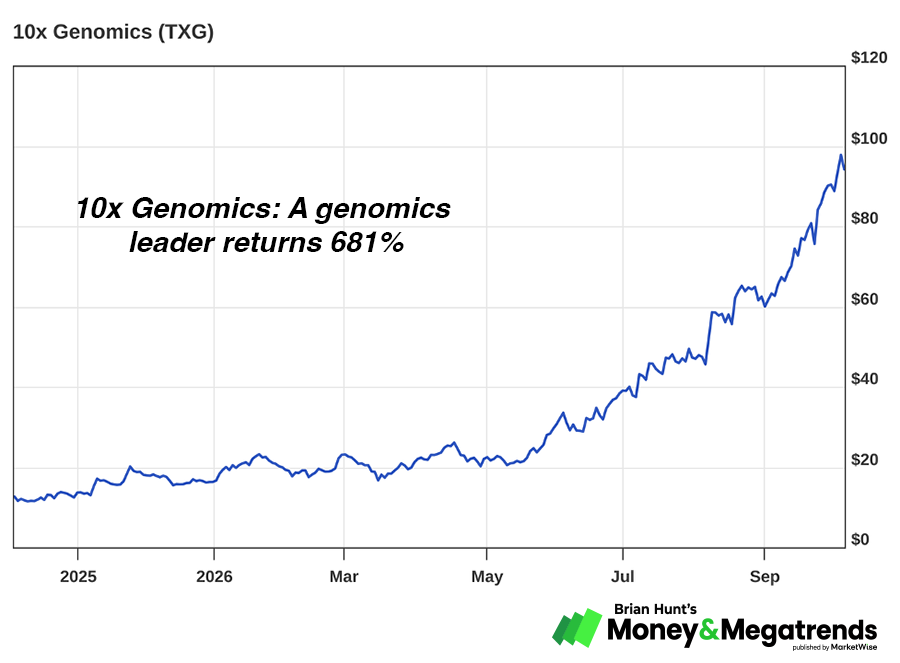
  • 10x Genomics (TXG) is a maker of advanced genomic research tools for analyzing individual cells, tissues, and spatial patterns of gene activity.

  • Adaptive Biotechnologies (ADPT), which analyzes immune-system genetics to develop tests and research tools for cancer, autoimmune, and infectious diseases.

  • GRAIL (GRAL) is a leading developer of blood-based screening tests designed to detect dozens of different cancers at their earliest stages.

  • The ARK Genomic Revolution ETF (ARKG) is one of the world’s most “bleeding-edge genomics-centric” ETFs.

Money & Megatrends readers in good standing are not surprised to see the genomics theme surge to new highs. On Oct. 9, 2025, we detailed the sector’s large upside potential and recommended getting long.

Over the past year, we’ve written over 20 research notes about the extraordinary upside potential of biotech and genomics. I don’t know of any other research publication that has been so early to this trend and written so frequently and emphatically about it.

Since our original note, many of the most important genomics companies have skyrocketed.

Genomics is the science of analyzing human DNA – the “software code of life” – to create tests, medicines, and treatments.

Years of innovation in this field are allowing healthcare firms to create customized treatments based on an individual’s DNA… and even “edit” genes to cure disease. This field is in the early innings of being transformed and turbocharged by AI. Super-intelligent computer programs can analyze massive datasets to enable early detection and personalized treatments. They are starting to design entirely new drugs.

The fusion of AI and genomics is generating massive winners in the stock market. We believe this trend is in its early stages. Researchers running superintelligent AI programs will be able to create useful new diagnostics and run millions of digital simulations of drugs and treatments. This will put medical innovation into overdrive… and create many big stock market winners.

This AI-driven, personalized, and preventative approach has us in the early innings of a historic revolution in healthcare. Ten years from now, medicine will be transformed… and a lot of money will be made along the way.

I’ve frequently mentioned how the ARKG is a good way to track and trade the genomics theme. It owns a basket of bleeding-edge genomic companies.

One of its largest holdings, Tempus AI (TEM), is often cited as a premier way to play “AI in health care.” It holds 10x Genomics and Twist Bioscience. It also holds significant positions in Guardant and Illumina… plus positions in promising “gene editing” companies CRISPR Therapeutics (CRSP) and Intellia Therapeutics (NTLA).

Getting into the genomics theme has proven to be one of our top-performing recommendations of the past two years. This sector was relatively small when we recommended getting into it. This means even modest new inflows of money can have enormous effects on stock prices.

Since our October 2025 recommendation, GH is up 181%. ILMN is up 204%. TWST is up 533%. TXG is up an extraordinary 681%.

These big individual moves have powered ARKG to a 74% since our 2025 recommendation, making it one of the world’s top-performing ETFs over that time.

After going on such a big run in such a short time, it is reasonable to expect the genomics theme to correct and digest its gains. But given how early we are in the process of “AI + genomics-based” diagnostics, analytics, and drug development, any such correction will likely be followed by another leg up for this high-growth industry.

Image

Recommended Link:

Elon’s $480 Trillion Currency Masterplan

Ad Image

He’s waited 27 years for this moment. Elon Musk just launched his biggest disruption ever, which could totally reset how millions of people access their money and even pay tax. Here’s exactly what to buy to profit.


This AI trade has turned into a moneymaking juggernaut

Image

Credit: ismagilov

Genomics isn’t the only well-timed Money & Megatrends theme on the stock market leaderboard. The cybersecurity sector is leading the market… and making our March 27 recommendation to get long the sector a large winner.

This week, cybersecurity stocks reaching important new highs include Palo Alto Networks (PANW), CrowdStrike (CRWD), Fortinet (FTNT), Okta (OKTA), Rubrik (RBRK, and SentinelOne (S).

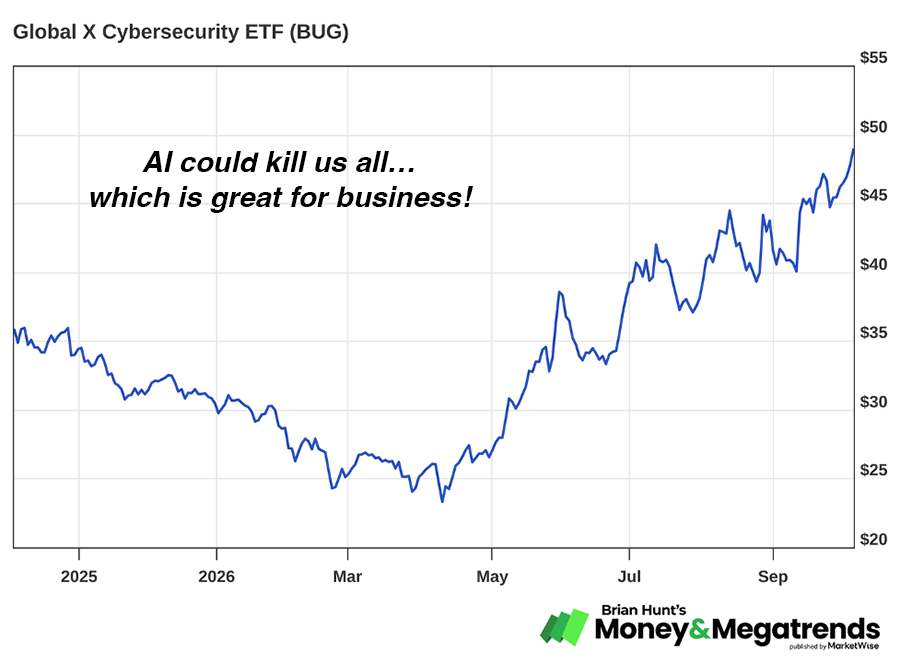
These strong individual performers have helped make the Global X Cybersecurity ETF (BUG) a large winner, up 88% over the past six months. The fund reached an all-time high this morning.

Back in March, we detailed how cybersecurity stocks were a compelling way to invest in our forecasted Agent Supernova, which is the explosion of AI agents that work for us, think for us, shop for us, invest for us, and solve hundreds of different problems for us.

In that issue, we detailed how this Agent Supernova was poised to explode, creating a huge number of new cybersecurity threats across banking, transportation, social media, energy production, healthcare, manufacturing, and many other industries.

If we’re going to have millions of AI agents performing billions of daily tasks in health care, education, energy, transportation, manufacturing, and technology, then we’re going to have billions of points of cybercrime vulnerability. And remember, crooks get to use AI too.

If agents can roam the web, communicate for you, log in to your apps, move money, and modify data at machine speed, then a compromised agent can do the same damage just as fast – now with far less human oversight to catch mistakes or intrusions. We stated this is why well-positioned cybersecurity companies are poised to enjoy years of booming business.

Concerns over AI safety have surged over the past two months, thanks to current and former Anthropic employees airing concerns that AI “could kill us all.”

They have shared precious few details on exactly how AI would do that, but presumably, they have some movie scenarios in mind, such as a “bad” AI taking over nuclear missile launches, developing a killer virus, or taking over transportation systems and causing catastrophic accidents.

Whatever the vector is, the public is now sufficiently spooked over AI. Political leaders are spooked over AI. And business leaders are spooked over AI.

This is all bullish for the cybersecurity business. After all, few things drive large increases in corporate cybersecurity budgets like a global AI panic.

We can see the future very clearly: Your average Fortune 500 CEO will be encouraged by his board to increase the cybersecurity budget. He will be encouraged by his executive team and workforce to increase the cybersecurity budget. Even his wife and kids will encourage him to increase the cybersecurity budget.

After all, the guy on the news said that “AI could kill us all”!

At the time of our March note, cybersecurity stocks – a special type of software stock – had suffered a sharp decline due to investor concerns that AI would disrupt software.

Soon after our note, cybersecurity stocks staged a huge rebound as investors began to believe AI wouldn’t disrupt the business as much as they had thought. CrowdStrike has returned 186%. Palo Alta has returned 169%. The Global X Cybersecurity ETF has returned 93%.

AI is the most exciting and potentially transformational technology of our time. The high-profile concerns aired by AI insiders over the past few months indicate that it’s probably also the most dangerous. That’s bullish for the cybersecurity industry.

Image


This industry has massive upside potential. How to trade it from here

Image

Credit: 3DSculptor

Are the beatings over for space stocks?

Can morale improve and create a new and rewarding bull market here?

We are starting to get indications that this could be the case…

Money & Megatrends readers in good standing will recall our belief that space-related industries will enjoy tremendous growth and generate many large stock market winners over the next five years.

On Sept. 22, 2025, I wrote a bullish piece on space stocks and said it’s a sector that the “public could go wild for.” I stated the bull case like this:

When people think of investing in space, they often go towards the business of launching rockets and Elon Musk’s SpaceX. But many of the most promising “space stocks” are in the business of space-based communication platforms and equipment. Think government surveillance, military communication, GPS, internet service, and cell service.

The best big picture fundamental case for space stocks right now is that the Trump administration believes America is in a hugely important competition with China and other countries for “space dominance.” This means regulatory and financial support for the U.S. space industry.

… Top performing individual space names worth checking out include Rocket Lab (RKLB), BlackSky (BKSY), Planet Labs PBC (PL), and AST SpaceMobile (ASTS).

Soon after our note, many space stocks soared 50%-100%, powered in part by anticipation of SpaceX’s (SPCX) gigantic IPO in June.

After that runup, however, space stocks experienced a large correction. I viewed this correction as natural, given its huge preceding run-up. No sector runs higher week after week in a straight line. The space trade needed to “work off” a lot of froth and enthusiasm.

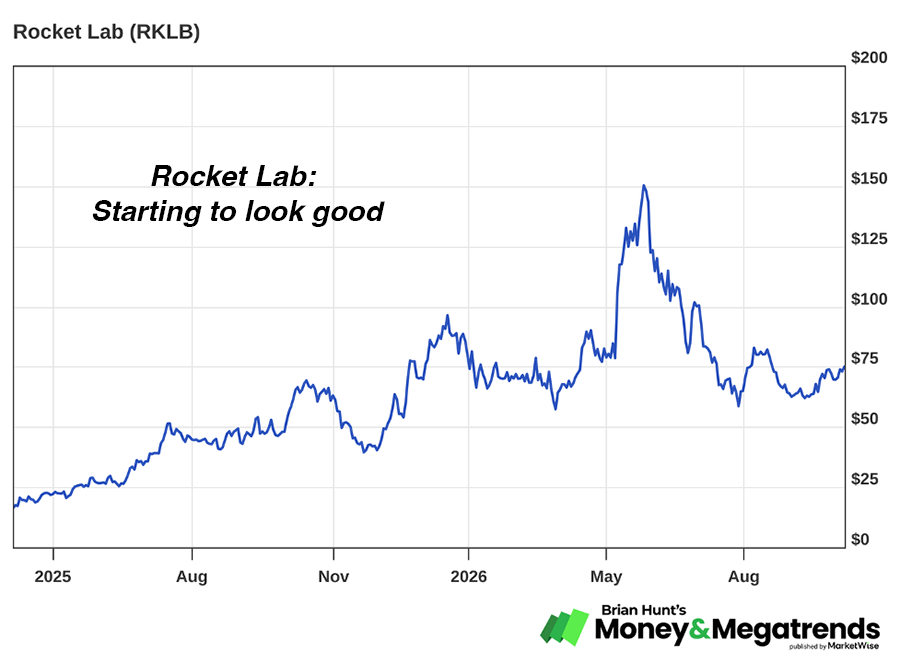
As you can see in the one-year chart below for RKLB, the correction appears to be ending… and health is being restored to this high-potential trend.

After supergiant Space X, Rocket Lab is America’s largest “space economy” stock.  This makes it one of the most widely followed and widely traded stocks in the industry. Its stock price trend gives us a good “real-time” read on the health of the space trade.

Rocket Lab makes rockets, satellites, and critical spacecraft components. Its Electron rocket launches small satellites into orbit, while its larger, reusable Neutron rocket is under development for heavier payloads.

Rocket Lab also manufactures satellite platforms, solar cells, navigation systems, and other space hardware used by commercial and government customers. Increasingly, the company can design, manufacture, launch, and operate entire satellite systems, making it one of the most vertically integrated competitors to SpaceX. Revenue has soared from $244 million in 2023 to $601 million in 2025.

As you can see in the 18-month chart below, RKLB enjoyed a spring rally and corrected in the summer, along with the rest of the space economy sector. The stock has found a bottom in the $60-$65 per share range, rebounded off it, and reached a one-month high this morning.

By itself, this new constructive price action for one of the leading space stocks does not mean “all clear, back up the truck and buy” for the space trade. However, it’s a step in the right direction. This high-potential trade is now near the top of our watch list.

Image


Market Notes

  • Our recommendation to ignore the AI bears and stay long the AI infrastructure trade continues to pay off. AI leaders Nvidia (NVDA), Advanced Micro Devices (AMD), and Everpure (P) all hit new highs today.

  • Our February 20th recommendation to get long Brazil is doing well. Itau Unibanco (ITUB) and Banco Bradesco (BBD) just hit new highs.

  • Leading diagnostics firm GRAIL (GRAL) continues to lead the market. The stock reached a new one-year high today. It is up 165% since our bullish June 12 note.

  • The Made in America megatrend we’ve been forecasting continues to generate stock winners. ProtoLabs (PRLB) is off to a good start as the stock just hit a new yearly high. Our pick-to-click Xometry (XMTR) also reached a one-year high.

Regards,

Brian Hunt signature

Brian Hunt signature

Brian Hunt
Editor, Money & Megatrends


An urgent message from our colleagues:

Elon’s Big Lie

Image

Elon Called This “Utterly False”… But the Evidence Says Otherwise. WSJ and Reuters both published this rumor. Elon denied it twice.

Here’s what he’s hiding.

The post Stocks for investing in a massive new AI trend appeared first on MarketWise.

  • ✇Market Wise
  • The strongest, most profitable bull market you’re probably missing Brian Hunt
    Today’s issue in preview: The strongest, most profitable bull market you’re probably missing This stealth AI trade is generating extraordinary winners. Are you in on it? Learn our Top Themes to buy now The strongest, most profitable bull market you’re probably missing Credit: gorodenkoff The modern-day gold rush in the healthcare business continues. This week, shares of Agilent Technologies (A) reached a new all-time high. Agilent is one of the largest and most important companies that
     

The strongest, most profitable bull market you’re probably missing

23 September 2026 at 12:00

Today’s issue in preview:

  • The strongest, most profitable bull market you’re probably missing

  • This stealth AI trade is generating extraordinary winners. Are you in on it?

  • Learn our Top Themes to buy now


The strongest, most profitable bull market you’re probably missing

Image

Credit: gorodenkoff

The modern-day gold rush in the healthcare business continues.

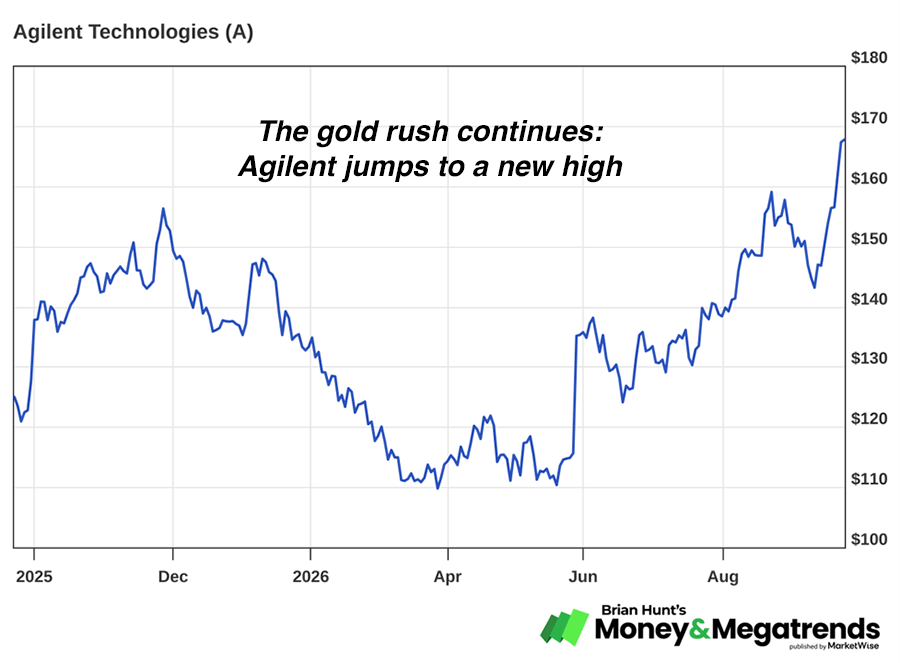
This week, shares of Agilent Technologies (A) reached a new all-time high.

Agilent is one of the largest and most important companies that most people have never heard of. It is a $45 billion giant of the Healthcare Equipment and Services industry.

Agilent is a leading provider of laboratory instruments, software, consumables, and services for analyzing chemical and biological materials. Its equipment – including chromatography, mass spectrometry, spectroscopy, and cell-analysis systems – is widely used by drug makers and biotech firms. Agilent also sells consumable supplies and maintenance services for its installed instruments.

Avid Money & Megatrends readers know that “Boomer health care” is one of our highest-conviction long-term investment megatrends. We don’t know of another investment research publication that has written more bullishly, more often about this booming industry than we have.

Over the past year, we have published more than two dozen pieces on opportunities in drug development, biotechnology, senior living facilities, genomics, cardiology, diagnostics, and more.

Our bullish stance has produced a parade of home runs, with the healthcare industry dominating the stock market’s new highs list over the past year.

Healthcare stocks are generating extraordinary returns because they are benefiting from several megatrends simultaneously…

One is demographics. More than 10,000 Americans reach retirement age every day. The U.S. population aged 80 and older is projected to roughly double, from 14.7 million in 2025 to 29.4 million by 2045.

This is the enormous Baby Boom generation entering the phase of life where health care and longevity spending skyrocket. For many boomers, a typical month involves going to see at least one doctor to have something looked at, removed, or treated.

This means many health care businesses are experiencing huge demand now – and will for at least the next decade.

Two is exponential technological progress. Thanks to major advancements in genomic sequencing, AI-powered analytics, imaging technology, and preventative treatment, healthcare is becoming much better and more personalized. This is driving strong demand for all kinds of new tests, tools, and treatments.

After all, when a useful and important service you buy gets much better, you typically buy more of it.

In the health care industry, giant drug firms like Eli Lilly (LLY) and Pfizer (PFE), as well as hospitals, get the lion’s share of media coverage and public awareness.

However, a large and varied ecosystem of smaller but critical health care businesses that are worth knowing about and owning. They comprise a huge – yet usually unseen – infrastructure layer of equipment and service providers that enable doctors, nurses, clinicians, and executives to do their jobs.

This is the world of CT scanners, hospital software, surgical tools, stents, catheters, endoscopes, artificial hips, X-ray machines, MRI machines, lab service providers, and syringes.

The U.S. spends more than $5 trillion on health care annually, or about 18% of GDP. This means the world of Healthcare Equipment & Services is large, varied, and full of opportunity.

Back to Agilent…

You generally won’t see Agilent equipment in patient rooms, operating rooms, or imaging departments. Agilent instruments are more likely to be found behind the scenes in laboratories.

For example, its pathology products can be used for tissue staining and cancer diagnostics, while its chromatography and mass-spectrometry systems can be used in research labs. Driven by strong revenue in the healthcare industry, Agilent expects 2026 sales to increase by about 8%.

Agilent is not the only Healthcare Equipment & Services stock on the market leaderboard.

  • This week, Agilent’s contemporary Danaher (DHR) reached a new six-month high.

  • Another Agilent contemporary, Mettler Toledo (MTD), reached a new one-year high.

  • Biological drug equipment leader Repligen (RGEN) just reached a new one-year high.

  • Lab instrument giant Waters (WAT) just reached a new one-year high.

  • Drug development services giant IQVIA (IQV) recently reached a new one-year high.

  • And as we covered last week, industry “super giant” Thermo Fisher Scientific (TMO) recently reached a new one-year high and is poised to break out of a huge multi-year consolidation pattern.

The fortunes of the firms above are closely tied to the R&D and capital spending cycles of drug firms such as Pfizer, Eli Lilly, Biogen, Amgen, Gilead, Merck, and Novartis.

When drugmakers expand laboratory research, genomic analysis, testing programs, and manufacturing capacity, they require more analytical instruments, consumables and bioprocessing equipment – the “picks and shovels” supplied by companies like Danaher and Agilent.

We believe the new highs reached by the likes of Danaher and Agilent are harbingers of a healthcare megatrend that will generate large returns over the coming years: That thanks to advanced genomic sequencing, AI-powered data analytics, and other bleeding edge innovations, the healthcare industry will move away from blunt “one size fits all” treatments and move to more “personalized” treatments that are tailored to an individual’s genetic makeup.

This megatrend will drive strong drugmaker R&D spending and strong revenue growth for well-positioned “picks and shovels” firms above.

Also, consider that U.S. healthcare leaders and the U.S. government are very keen on increasing domestic drug manufacturing to reduce our reliance on foreign manufacturing.

The FDA says more than half of pharmaceuticals distributed in the U.S. are manufactured overseas, and only about 11% of active pharmaceutical ingredient (API) manufacturers are U.S.-based.

Since 2025, pharmaceutical companies have announced hundreds of billions of dollars of U.S. manufacturing and R&D investment. CBRE tracked approximately $350 billion in announcements, although it estimates that roughly half of these were projects that had already been planned or begun – an important caveat when interpreting the headline.

Add these two trends – the personalized treatment revolution and the domestic drug manufacturing boom – and you get serious fundamental tailwinds that will continue driving the bull market in many areas of healthcare, especially the “picks and shovels” providers of drug development and manufacturing.

This new stock trend has much further to run.

Image

Recommended Link:

For the First Time Ever, Marc Chaikin and Louis Navellier Agree

Ad Image

Everything is about to CHANGE about the U.S. stock market. Marc Chaikin and Louis Navellier – using entirely different systems and strategies – have independently confirmed an event with a 92% chance of sending shockwaves through the market before the midterm elections. They’ve even tracked its arrival down to the EXACT day in October, thanks to a 100-year precedent. On Tuesday, September 29, they’ll join forces for the first time ever to tell you the EXACT day they see it’s coming – and give away FOUR urgent moves to make with your money now. Learn more and reserve your spot.

This stealth AI trade is generating extraordinary winners. Are you in on it?

Image

Credit: piyaset

The modern-day gold rush isn’t just making lab equipment shareholders wealthier. As we expected, genomic stock owners are getting richer as well.

The latest example of this phenomenon is the new all-time high reached today by genomics testing and analytics giant Illumina (ILMN). The stock rose 1.3% this morning, reaching a new all-time high.

Illumina’s strength has helped propel the ARK Genomic Revolution ETF (ARKG) to a new all-time high this week.

Illumina is one of the world’s largest DNA sequencing and analysis firms. Its sequencing machines, consumables, and software allow drug companies to read and analyze genetic information. Illumina’s technology is widely used in cancer research, rare-disease diagnosis, and reproductive health.

Its business benefits from growing adoption of genomics, with recurring revenue generated from sequencing consumables used on its installed base of instruments. The stock is up 158% since our original Oct. 9, 2025, bullish note on genomics.

Constant Money & Megatrends readers won’t be surprised to hear that the likes of Illumina are producing big returns.

Over the past year, we’ve written more than a dozen research notes about the extraordinary upside potential of biotech and genomics. We’ve written specific bullish notes on all the names listed above.

Genomics is the science of analyzing human DNA – often referred to as the “software code of life” – to create tests, medicines, and treatments.

Years of innovation in this field have us on the brink of creating customized, personalized treatments based on an individual’s DNA… and even “editing” genes to cure disease.

Industry bulls believe it will get a big “AI boost,” because super-intelligent computer programs can analyze genes and treatment effects so well… and have the potential to create drugs on their own.

The fusion of AI and genomics should generate dozens of compelling stock narratives over the coming years. Researchers running superintelligent AI programs will be able to create useful new diagnostics and run millions of digital simulations of drugs and treatments. This will put medical innovation into overdrive… and create many big stock market winners.

The personalized approach to medicine that genomics offers has us on the cusp of a historic revolution in healthcare. Ten years from now, medicine will be transformed… and a lot of money will be made along the way.

I’ve frequently mentioned how ARKG is one way to track and trade the genomics theme. It owns a basket of bleeding-edge genomic companies. It is up 63% since our original note.

One of its largest holdings, Tempus AI, is often cited as a premier way to play “AI in health care.” It holds genomics tools and services firm 10x Genomics (TXG) and synthetic DNA firm Twist Bioscience (TWST). TWST is up 396% since our original bullish note. TXG is up a 568%.

ARKG also holds significant positions in promising “gene editing” companies CRISPR Therapeutics (CRSP) and Intellia Therapeutics (NTLA).

It’s increasingly looking like genomics, and some drug development firms are being painted with the “AI brush,” a development that can turbocharge any trend or stock here in 2026. We recommend staying long.

Image


Market Notes

  • Our March 27th recommendation to own cybersecurity stocks is paying off. CrowdStrike (CRWD), Fortinet (FTNT), Cloudflare (NET), Okta (OKTA) and Dynatrace (DT) all hit new highs.

  • Our October 8th recommendation to own the Boomer healthcare trend is paying off. Thermo Fisher Scientific (TMO), Biogen (BIIB), Genmab (GMAB), and AbbVie (ABBV) just hit new highs.

  • Our recommendation to own farm machinery giant Deere & Co. (DE) is working well. The stock reached a new all-time high today.

  • More good signs for the AI infrastructure trade: Semiconductor leader Advanced Micro Devices (AMD) hit an all-time high and is now a $1 trillion company.

Regards,

Brian Hunt signature

Brian Hunt signature

Brian Hunt
Editor, Money & Megatrends


An urgent message from our colleagues:

This AI System identified the stocks positioned to surge

Image

While everyone rushes into Nvidia and SpaceX, one AI insider says the real money will be made elsewhere. Keith Kaplan’s AI system has identified a small group of stocks positioned to surge as the big-name AI trade breaks down.

Watch his free briefing now before September 30th.


The post The strongest, most profitable bull market you’re probably missing appeared first on MarketWise.

  • ✇Porter & Co
  • Moving Arrowhead Pharmaceuticals Off The Watchlist Porter &#38 · Co.
    In Porter’s first issue of Porter & Co. Biotechnology, he recommended one of the key players in gene silencing, Arrowhead Pharmaceuticals (Nasdaq: ARWR). However, he felt that we needed to wait for a better entry price. In that August 1 issue, he said that Arrowhead had done everything right: its triglyceride drug is approved and selling, it has pushed gene silencing into muscle, fat, lung, and brain, and the large drugmakers have paid Arrowhead billions for access. The stock had run from
     

Moving Arrowhead Pharmaceuticals Off The Watchlist

18 September 2026 at 08:17

In Porter’s first issue of Porter & Co. Biotechnology, he recommended one of the key players in gene silencing, Arrowhead Pharmaceuticals (Nasdaq: ARWR). However, he felt that we needed to wait for a better entry price. In that August 1 issue, he said that Arrowhead had done everything right: its triglyceride drug is approved and selling, it has pushed gene silencing into muscle, fat, lung, and brain, and the large drugmakers have paid Arrowhead billions for access. The stock had run from $15 to $87 in the past year. We want to own this company below $75, he concluded.

Shares of Arrowhead Pharmaceuticals are now trading around $67 per share, so we are moving them from our watchlist into a “buy” recommendation, below $75.

Action to Take: Buy Arrowhead Pharmaceuticals (Nasdaq: ARWR) below $75 per share

The post Moving Arrowhead Pharmaceuticals Off The Watchlist appeared first on Porter & Co..

  • ✇Porter & Co
  • The Biotech Bulwarks Porter &#38 · Co.
    To get a copy of this special report, just click the image on the left or click the button below that says “Download.” Then, the special report will be put on your computer into a folder called “Download.” Download The post The Biotech Bulwarks appeared first on Porter & Co..
     

The Biotech Bulwarks

16 September 2026 at 06:07

To get a copy of this special report, just click the image on the left or click the button below that says “Download.” Then, the special report will be put on your computer into a folder called “Download.”

The post The Biotech Bulwarks appeared first on Porter & Co..

  • ✇Porter & Co
  • The Kingdom Of Gene Silencing Porter &#38 · Co.
    To get a copy of this special report, just click the image on the left or click the button below that says “Download.” Then, the special report will be put on your computer into a folder called “Download.” Download The post The Kingdom Of Gene Silencing appeared first on Porter & Co..
     

The Kingdom Of Gene Silencing

16 September 2026 at 06:04

To get a copy of this special report, just click the image on the left or click the button below that says “Download.” Then, the special report will be put on your computer into a folder called “Download.”

The post The Kingdom Of Gene Silencing appeared first on Porter & Co..

  • ✇Porter & Co
  • The Nvidia Of Medicine Porter &#38 · Co.
    To get a copy of this special report, just click the image on the left or click the button below that says “Download.” Then, the special report will be put on your computer into a folder called “Download.” Download The post The Nvidia Of Medicine appeared first on Porter & Co..
     

The Nvidia Of Medicine

16 September 2026 at 06:03

To get a copy of this special report, just click the image on the left or click the button below that says “Download.” Then, the special report will be put on your computer into a folder called “Download.”

The post The Nvidia Of Medicine appeared first on Porter & Co..

  • ✇Porter & Co
  • The Highs And Lows Of Drug Development Porter &#38 · Co.
    Issue#154, Volume#3Updates On Novartis And Roivant Sciences Inside Today’s Issue Essay: The Highs And Lows Of Drug Development Declining Treasury Returns Insider Buying At Uber Japan’s Yen Support Chart Of The Day… Roivant Sciences (ROIV) Today’s Mailbag We don’t normally update stock recommendations from our various services in the Daily Journal, but from time to time something happens that’s important enough to discuss with the entire audience. On Friday, Porter & Co. Biotechnology r
     

The Highs And Lows Of Drug Development

8 September 2026 at 13:00

Issue#154, Volume#3

Updates On Novartis And Roivant Sciences


We don’t normally update stock recommendations from our various services in the Daily Journal, but from time to time something happens that’s important enough to discuss with the entire audience.

On Friday, Porter & Co. Biotechnology recommendation Novartis (NVS) announced that its heart and cholesterol drug pelacarsen failed in a Food And Drug Administration (“FDA”) Phase III trial to reduce cardiovascular events despite lowering the harmful cholesterol Lp(a).

One of our main themes in Porter & Co Biotechnology is a technology called RNA interference. It can prevent harmful proteins from being produced inside cells, before they cause harm in your body. As this intervention occurs earlier in the pathology of disease and inside cells, it has a good safety profile and can be extremely effective. We believe it’s going to become a dominant new approach to treating chronic disease.

One of the biggest potential market opportunities for RNA interference is preventing the production of certain kinds of cholesterol that are linked to cardiovascular disease (heart attack, stroke). Cardiovascular disease is a leading cause of death, so there are potentially huge markets for these drugs – if they’re safe, and if they can prevent disease.

Novartis has been conducting a six-year-long, huge (8,323 people) clinical trial (“HORIZON”) using an older form of RNA interference (antisense) to target lipoprotein(a). Lp(a) is a cholesterol-carrying particle found in the blood. It resembles an LDL particle, the type commonly called “bad cholesterol,” with an additional protein called apolipoprotein(a) attached to it.

Your genes determine most of your Lp(a) level. Diet, exercise, and statins generally do little to change it. People born with high Lp(a) experience more heart attacks, strokes, and aortic-valve disease over their lifetimes. And currently there’s no FDA-approved treatment to reduce Lp(a), which makes it one of the most valuable potential drug targets in medicine.

Novartis’ Lp(a) drug is called pelacarsen. On Friday afternoon, Novartis announced that pelacarsen did not lower the risk of cardiovascular events in the treatment population of the clinical trial. We don’t have complete data from the trial, so we don’t know exactly how it failed. We do know that Pelacarsen did what an antisense drug is supposed to do: it lowered the protein it was designed to lower. The problem is that patients did not suffer fewer cardiovascular events as a result.

There’s a lot of controversy about cholesterol drugs (statins) already. Many people claim that LDL isn’t the cause of heart attacks. While cardiovascular disease is multi-faceted, there’s no question that lowering LDL, especially before cardiovascular disease has begun, can dramatically reduce the risk of heart attack and stroke. We know this because some people have natural mutations that result in much lower levels of LDL and they have much less (88% less, in one landmark study) incidence of heart disease. Likewise, some people have natural mutations that lead to much higher levels of LDL – they get heart disease when they’re still very young.

Using drugs to replicate lower levels of LDL improves cardiovascular health: The Cholesterol Treatment Trialists combined 26 randomized trials containing 170,000 participants. Each 38.7 milligram-per-deciliter (“mg/dL”) reduction in LDL produced a 22% reduction in major vascular events and a 10% reduction in overall mortality. A meta-analysis of patients beginning at very low LDL levels found a 21% reduction in major vascular events for every 38.7 mg/dL reduction, combining statins and nonstatin drugs.

I’m explaining all of this because I suspect there will be a lot of people (especially on the internet) who point to this clinical-trial failure and then claim that cholesterol isn’t a factor in heart disease. But that isn’t what this trial means. LDL has bidirectional genetic evidence and repeated outcome benefits from several mechanistically different drugs.

Still, if high Lp(a) leads to heart attack, then why didn’t lowering it reduce heart attacks?

Pelacarsen is an antisense oligonucleotide (“ASO”) – a short, manufactured strand of genetic material designed to bind to one specific messenger RNA. When pelacarsen binds to the message for apolipoprotein(a), the cell destroys that message. With fewer instructions available, the liver makes less apolipoprotein(a), and the patient’s Lp(a) level falls.

What The Trial Tested

This clinical trial enrolled 8,323 patients who already had cardiovascular disease and Lp(a) levels of at least 70 mg/dL. Patients received either an 80-milligram pelacarsen injection once a month or a placebo injection containing no active drug. Neither the patients nor their doctors knew which treatment they received (this was a “double-blind” clinical trial).

The trial measured a composite endpoint. A composite endpoint combines several medical outcomes into one score so that the trial can accumulate enough events to reach a conclusion. The Pelacarsen trial, Lp(a)HORIZON, counted the first occurrence of cardiovascular death, a nonfatal heart attack, a nonfatal stroke, or an urgent procedure to restore blood flow to the heart.

Researchers often call this collection of outcomes MACE – major adverse cardiovascular events. Pelacarsen did not significantly reduce these events in the overall trial population, even though it lowered Lp(a).

“Did not significantly reduce” has a precise meaning. The difference between pelacarsen and placebo was not large or consistent enough for the trial to rule out chance under its pre-specified statistical test. Novartis has not disclosed the actual difference, known as the hazard ratio, or the range of plausible values around it, known as the confidence interval.

We therefore do not yet know whether pelacarsen produced no benefit, a small benefit, or a benefit concentrated among patients with the highest Lp(a). Novartis also has not disclosed the separate event counts, the amount of Lp(a) lowering achieved during the study, or the complete results for patients who started at 90 milligrams per deciliter or higher.

Why Pelacarsen May Have Failed

  1. Lp(a) may identify cardiovascular risk without being a useful drug target. A marker can predict disease without causing enough of the disease to make its removal helpful. Medicine has seen this before: raising HDL cholesterol improved a laboratory number but did not reliably prevent heart attacks.
  2. Treatment may have started too late. Genetic studies measure the effects of high Lp(a) across an entire lifetime. Lp(a)HORIZON began treatment after patients already had cardiovascular disease. Lowering one source of damage for several years may not reverse decades of plaque formation and injury.
  3. Pelacarsen may not have lowered Lp(a) far enough. Its earlier trials produced reductions near 80%. Competing siRNA drugs have produced reductions above 90%. If cardiovascular benefit requires crossing a threshold rather than merely lowering the level, the deeper reduction could matter.
  4. The trial may have enrolled too many patients whose remaining risk came from something other than Lp(a). The median starting Lp(a) was 108 milligrams per deciliter, and 21.4% of patients entered below 90 milligrams per deciliter. About 77.5% received high-intensity statins, and roughly 11% received a PCSK9 inhibitor.

PCSK9 inhibitors are powerful LDL-lowering drugs. A 2025 analysis of 273,770 patients with established cardiovascular disease found that the connection between Lp(a) and recurring cardiovascular events weakened as LDL treatment intensified and disappeared statistically among patients receiving PCSK9 inhibitors. If modern treatment had already removed much of the risk attributable to Lp(a), pelacarsen had little left to prevent.

The missing results will distinguish these explanations. We need the actual event rates, the hazard ratio, the confidence interval, the achieved Lp(a) levels, and the results among patients starting at 90 mg / dL or higher. We also need to know whether the event curves moved apart late in the study, which would suggest that benefit requires more time.

What The Result Means For Lp(a)

Lp(a) remains a genetically established risk factor.

Genetic evidence tells us that people exposed to high Lp(a) for decades have more disease. A successful clinical trial must show that lowering Lp(a) with a drug, later in life, improves patient outcomes. Pelacarsen failed that test.

The next decisive Lp(a) study belongs to Amgen (AMGN). Its drug, olpasiran, is being tested in an ongoing large-scale trial called “OCEAN.” This trial required a higher starting Lp(a), uses an siRNA that produces deeper lowering, and excludes stroke from its three-part primary endpoint. Those differences address several possible weaknesses in Lp(a)HORIZON. But they do not guarantee success.

Eli Lilly’s (LLY) lepodisiran also uses siRNA to target Lp(a) and is being tested in a larger population that includes some patients without established cardiovascular disease. Lilly’s muvalaplin is a daily pill that prevents Lp(a) particles from assembling rather than silencing messenger RNA (“mRNA”).

What Does This Setback Cost Novartis…?

Ionis Pharmaceuticals (IONS) discovered pelacarsen. Novartis licensed it and became responsible for worldwide development, manufacturing, and commercialization.

The contract allowed Ionis to receive as much as $900 million. The amount included a $75 million upfront payment, a $150 million license payment, a $25 million development payment, up to $290 million tied to regulatory progress, and up to $360 million tied to sales. Ionis had received more than $275 million through the end of 2025. It would have received another $50 million if the FDA accepted a pelacarsen application.

Novartis has never disclosed the cost of Lp(a)HORIZON. Our reconstruction is $250 million to $700 million, with $450 million as the base estimate. The study operated for more than six years, enrolled 8,323 patients at 902 sites, administered monthly injections, and continued until independent reviewers confirmed 993 cardiovascular events.

Novartis paid Ionis more than $65 million for a separate next-generation Lp(a) ASO program that it terminated in 2025. Including that program, other pelacarsen studies, drug manufacturing, launch preparation, Lp(a) testing campaigns, and the original Ionis equity investment, our total Novartis Lp(a) spending estimate is $850 million to $1.55 billion.

Here’s what matters to shareholders: Novartis expensed the clinical work as it occurred. Pelacarsen has no current sales. Its failure therefore has almost no effect on 2026 earnings.

The pelacarsen call option from our August recommendation should be treated as lost. But Novartis is a broadly diversified, major pharmaceutical company. It does not depend on pelacarsen alone. Its LDL drug, Leqvio, is growing rapidly. It silences PCSK9 rather than apolipoprotein(a), lowers LDL cholesterol rather than Lp(a), and operates in a pathway already validated by successful outcomes trials using PCSK9 antibodies.

Our August valuation was $180 per Novartis share. We don’t believe the failure of this trial impacts that valuation by more than $2 to $4 per share. Our next evaluation will occur when we get the full Lp(a)HORIZON data set.

What’s actually driving the share price of Novartis down today was a different clinical trial failure. And it matters more because this was a major ($12 billion) acquisition, not just a licensing deal.

Earlier this year, Novartis bought Avidity Bioscience, which was a clinical-stage biotech company developing RNA medicines for inherited muscle diseases.

Avidity’s core technology is an antibody that can deliver RNA drugs into muscle cells. The company had three advanced programs, including a Del-desiran for myotonic dystrophy (type 1). This inherited muscle disease causes weakness and myotonia: the inability to relax a muscle normally after using it.

The drug uses small interfering RNA, or siRNA, to destroy the toxic genetic message that causes DM1. An antibody carries Avidity’s siRNA into muscle. Earlier biopsies proved that this delivery system worked: del-desiran reached human muscle and reduced its intended RNA target by 37% to 46%. Its Phase III clinical trial (“HARBOR”) enrolled 159 patients. Its primary test measured how quickly patients could open their hands after squeezing them. Del-desiran did not improve that measurement significantly versus placebo. Novartis said other measures showed some clinical activity, but it has not released the full data.

The failure does not prove that the drug missed its molecular target or that Avidity’s muscle-delivery system is broken. The trial may have used a noisy new measurement, enrolled too few patients for a variable disease, treated them for too little time, or failed because partial correction of the molecular defect cannot restore damaged muscle. The complete strength, walking, daily-activity, and biological results will distinguish those explanations.

But, a lot more money is at stake in these drugs. Novartis assigned $7.5 billion of the purchase price to Avidity’s muscular dystrophy programs. If del-desiran is abandoned, most or all of that accounting asset could be written off. Our base estimate is a $6.2 billion loss of equity value, or about $3.25 per Novartis share.

While failed clinical trials are never good news, these are normal costs. We see no reason to change our outlook on Novartis and continue to expect it to become the market’s leading RNA-interference company.

And… there’s a reason we take a portfolio approach to our biotech investing.

Roivant Sciences (ROIV) is up about 20% today on strong Phase II results for mosliciguat in pulmonary hypertension caused by interstitial lung disease. Mosliciguat is an inhaled medicine designed to relax the blood vessels in damaged lungs, making it easier for the heart to pump blood through them. The drug reduced resistance in the lung’s blood vessels by 56.3% versus placebo. Patients also walked 35.2 meters farther in six minutes, while NT-proBNP, a blood marker of cardiac strain, fell 53.2%. The result is persuasive because the drug improved three different things: blood flow through the lungs, patients’ physical ability, and stress on the heart. Roivant has begun Phase III (“PHrontier”).

Tell me what you think of today’s Journal: porterstansberrydirect@gmail.com

Good investing,

F. Porter Stansberry
Stevenson, Maryland


Presented By: Katusa Research

The Scale Of What Is Coming

Roughly every reactor on earth — built again, by one country.

This administration intends to quadruple America’s nuclear capacity to 400 gigawatts. That is more nuclear power than the United States, France, China, Russia and South Korea operate combined — those five countries being 71% of all capacity on earth.

● One gigawatt powers roughly 700,000 American homes

● Uranium has not been in surplus since 2016

● $80 billion partnership signed with Westinghouse Electric

Read the full analysis

Sponsored content from Katusa Research. Not investment advice. Speculative resource investing involves substantial risk of loss; past performance is not indicative of future results. Katusa Research is located in Vancouver, BC, Canada.

Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Katusa Research is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.


3 Things To Know Before We Go…

1. U.S. Treasury bonds have lost money over the past decade. U.S. government debt maturing in 15 years or more returned roughly -2% a year over the 10 years through August, according to BofA Global Investment Strategy. That is the worst 10-year stretch since 1936, and the only time the figure has dropped below zero. The math is simple: the 30-year Treasury yielded 2.23% in September 2016 and yields 5.25% today. Bond prices fall when yields rise, and the longer the bond’s duration, the further it falls. The iShares 20+ Year Treasury Bond ETF (TLT) has dropped 52% from its July 2020 peak – a deeper decline than the S&P 500 suffered in 2008.

2. A big insider buy at Uber. Uber Technologies (UBER) president and COO Andrew Macdonald bought 70,000 shares on the open market on September 4 at $75.83 – a $5.31 million purchase that boosted his holdings by 20%, to 426,320 shares. Macdonald sees the growth possibilities from the inside every day. After 14 years of equity compensation, he’s buying more with his own cash.

3. Japan sells Treasuries to fund currency intervention. Japan liquidated a record $88 billion of foreign securities in August, which includes U.S. Treasuries. The sales likely funded Japan’s $98.6 billion currency intervention in August, designed to shore up the yen after it fell near 40-year lows in July. As the largest foreign owner of U.S. Treasuries, any further pressure on the Japanese currency risks spilling over into additional weakness in the U.S. bond market.


Chart Of The Day… Roivant Sciences (ROIV) 

As Porter reported above, shares of Porter & Co. Biotechnology recommendation Roivant Sciences (ROIV) jumped 20% today to a new high after its Pulmovant subsidiary reported a record 56.3% reduction in pulmonary vascular resistance in a Phase II trial of mosliciguat – stacking a second catalyst on top of Lisraya’s early commercial launch.


Mailbag

On September 1, Porter & Co. released details of the latest buy signal for our Porter & Co. Systematic Crypto service, available to Partners.

“Very Informative”

Greg R. writes:

The article was very informative. Most especially, news of your Bitcoin (BTC) pricing model. Some time ago I became aware that the value of hard assets is correlated to economic liquidity, as opposed to market swings. Your writing has helped solidify that thesis for Bitcoin as well.

I have been purchasing small amounts for several years, and see no reason to stop, even as the price climbs. (Is there ever a reason not to buy good, quality assets if you have the means?)

I think that in my lifetime people who are late to find their way to BTC will speak of Satoshis as a unit of measure, not whole coins, because the price of a single BTC will be out of their reach. I’d back the truck up to it if I had the present means!


Schuler B. writes:

Fantastic – made Bitcoin so simply understood.


“Bitcoin?”

JM writes:

Bitcoin? I think I’ll stick with investing in insurance companies.


Porter & Co. Market Snapshot

Price Friday’s Return Year-to-Date Return
S&P 500 Index $7,718.60 -0.36% 13.6%
Gold per ounce $4,404.30 -0.51% 1.9%
Bitcoin $79,223 -0.87% -10.5%
Oil (West Texas Intermediate) per barrel $91.48 18.82% 61.8%
Berkshire Hathaway (BRK) $759,350 -0.48% 0.6%
Porter’s Permanent Portfolio – -0.87% 4.4%
The Better Than Berkshire Index – -1.05% 7.5%
Total Return Annual Return
Porter & Co’s Top Ranked* 35.6% 16.2%
Yield Friday’s Change Change
Year-to-Date
U.S Treasury 30-Year Yield 5.24% 0 bps 40 bps
Prices as of 4:00 pm ET September 4, 2026 | bps = basis points (or 0.01%)
*A Complete Investor risk rating of 1 is defined as a “low risk, high allocation” security, while positions rated closer to a 5 are higher risk. Porter & Co.’s top-ranked positions include those rated either 1 or 2 in Complete Investor portfolio.


Porter & Co. Top Positions

Publication Ticker Description Total Return
Biotechnology QURE uniQure 237%
Biotechnology SGMT Sagimet Biosciences 203%
Complete Investor BTC/USD Bitcoin 193%
Complete Investor BWXT BWX Technologies 178%
Biotechnology NUVB Nuvation Bio 168%
Biotechnology TGTX TG Therapeutics 158%
Biotechnology ROIV Roivant Sciences 155%
Complete Investor SKWD Skyward Specialty Insurance 133%
Biotechnology QURE uniQure 131%
Complete Investor PM Philip Morris 128%
Prices as of 4:00 pm ET September 4, 2026

Please note: The investments in our “Porter & Co. Top Positions” should not be considered current recommendations. These positions are the best performers across our publications – and the securities listed may (or may not) be above the current buy-up-to price. To learn more, visit the current recommendations page of the relevant service, here| New Window. To gain access or to learn more about our current recommendations, call our Customer Care team at 888-610-8895 or internationally at +1 443-815-4447.

The post The Highs And Lows Of Drug Development appeared first on Porter & Co..

  • ✇Porter & Co
  • The Age Of Discovery Porter &#38 · Co.
    Understanding Last Month’s Nobel-Worthy Breakthroughs Edit Delete Edit Delete This is Porter & Co. Biotechnology – where Porter Stansberry presents a revamped portfolio to capitalize on the next biotech bull market. The details of the recommendations – and the specific name of the companies and buy prices – are for paid-up subscribers only. To learn more about subscribing to Porter & Co. Biotechnology, click here. We’ve forgotten how hard it was to build modern hea
     

The Age Of Discovery

5 September 2026 at 07:00

Understanding Last Month’s Nobel-Worthy Breakthroughs

⚙ Edit 🗑 Delete
⚙ Edit 🗑 Delete

This is Porter & Co. Biotechnology – where Porter Stansberry presents a revamped portfolio to capitalize on the next biotech bull market. The details of the recommendations – and the specific name of the companies and buy prices – are for paid-up subscribers only. To learn more about subscribing to Porter & Co. Biotechnology, click here.


We’ve forgotten how hard it was to build modern healthcare.

In 1900, pneumonia, tuberculosis, and diarrheal diseases were the three leading causes of death in America. Staphylococcus aureus in the bloodstream killed 82% of the people who got it and most of them were young and healthy. Even as late as 1935, maternal mortality was still 600 per 10,000 live births.

Then, penicillin emerged – as an accident. A mold spore drifted onto a culture plate in Alexander Fleming’s London laboratory in 1928. It killed the bacteria growing there. And, unbelievably, it was safe enough to be dosed into humans. Out of all the world’s innovations and technologies, only synthetic nitrogen fertilizer has enabled more human life than the discovery of antibiotics.

By 1950, maternal mortality had fallen to 100 women per 10,000 live births. Today, it’s between 10 and 20.

In 1900, 40% of the deaths from pneumonia were children under five. Today, only the very old and the very sick die from pneumonia. And, overall, less than 3% of all deaths in America are attributable to the leading causes of death in 1900.

But these innovations were not easy.

Modern drug discovery began at Rutgers University in the late 1930s. Professor Selman Waksman (pictured right, below) set out to discover new antibiotics with a systematic approach. His method was witchcraft crude by today’s standards. He dug up soil samples, cultured whatever was growing in it, and then painstakingly tested every culture against live bacteria, until something worked. It was like a blind man searching for a needle in 10,000 haystacks.

But it was foolproof. A student streaked a soil microbe in a line down the middle of a plate. Then he streaked a disease bacterium across that line at a right angle. If the microbes in the soil were producing something effective at killing bacteria, it left a clear band through the bacterial streak. About 1,000 of Waksman’s 10,000 soil cultures produced a clear band. But that didn’t mean he discovered 1,000 new antibiotics. This was only the first hurdle.

Nearly every antibiotic he discovered came out of actinomycetes: the thread-like soil bacteria that produce the smell of fresh-turned dirt. One actinomycete in 10 makes the same compound, streptothricin. Waksman isolated it, tested it, and discovered it was toxic.

And then there was another problem: many of the compounds he discovered killed the wrong type of bacteria. As you probably know, bacteria come in two forms: gram-positive and gram-negative. Gram-positive bacteria have a thick cell wall that’s “naked.” Gram-negative bacteria have a thin cell wall that’s protected by a membrane.

Penicillin works by jamming the enzyme that builds the cell wall, which causes the cell to burst as it grows. Against bacteria with a thick bare wall (gram-positive) the drug is devastating. But against a gram-negative bacterium, it never reaches the wall at all: the outer membrane protects it. Plague, cholera, and typhoid are gram-negative – penicillin did nothing to them. What Waksman needed was a compound that could kill what penicillin couldn’t. He needed to find a compound that could destroy gram-negative bacteria.

And then there was a final problem. Some of the gram-negative killing compounds could not be manufactured. Producing an antibiotic in quantity means growing the microbe in thousands of gallons of liquid inside a steel tank. Plenty of microbes that secrete freely across a solid plate will not secrete anything once they are submerged.

Out of 10,000 cultures, roughly 100 survived all of these challenges. Then they all had to be isolated. That meant separating the one active molecule out of the soup the microbe grew in, purifying it, and then making enough of it to inject into an animal. That took the sorting from 100 down to only 10.

Then the animals they were testing these new antibiotics on kept dying. In 1940, actinomycin, the first antibiotic the program found, was the most powerful anyone had ever measured. But just one milligram of it killed a full-grown chicken. Streptothricin passed its early animal tests and then destroyed kidneys weeks after the dose. Clavacin and fumigacin failed the same way.

Waksman discovered that, relatively speaking, killing bacteria wasn’t that hard. Killing bacteria at a dose the patient can survive was vastly harder. But finally, one of Waksman’s researchers found one.

Albert Schatz, a 23-year-old graduate student working alone in the basement at Rutgers, isolated streptomycin on the afternoon of October 19, 1943. It cured tuberculosis, a deadly disease that had killed millions. The discovery won Waksman the Nobel Prize in 1952.

Diminishing Returns On Drug Research

Over the following decade, researchers in his laboratory worked through more than 100,000 more cultures. But instead of improving with time, his lab discovered fewer new compounds, even as it spent more money on discovery. Economists call the problem Eroom’s Law, which is Moore’s Law spelled backward. Just as Moore’s Law held that computer chip speed doubled every two years, Eroom’s Law holds that the number of new drugs approved per billion dollars of research spending has been cut in half roughly every nine years since 1950. In the early 1950s, an inflation-adjusted billion dollars of research bought 40 to 50 approved medicines. By 2018, that same billion bought 0.7.

Today, the Tufts Center For The Study Of Drug Development puts the all-in cost of one approved drug at $2.6 billion. Where does all the money go? It goes toward the overwhelming percentage of drugs that fail.

That’s why the drug business has always been organized around diversifying the risks as much as possible. But that’s finally changing.

In much the same way that technology converted the oil-and-gas industry from a discovery challenge to an engineering challenge, with enormous horizontal wells, technology is changing the essential challenge of medicine from discovery to manufacturing.

For a century, the oil business ran on the same odds as when Waksman’s antibiotics were discovered. Until the late 1970s, the industry considered a 10% wildcat success rate attractive: one successful well for every nine dry holes. The American Association of Petroleum Geologists tracked it by decade. New-field wildcat success ran 11.3% from 1946 to 1955, 10.8% from 1956 to 1965, and 11.2% from 1966 to 1975.

Thirty years, and no improvement at all.

Then, the industry discovered three-dimensional seismic surveying. This technology bounces sound waves off rock layers and reconstructs the subsurface inside a computer. It first emerged in the 1980s and became standard practice by the 1990s. Amoco measured the difference. Between 1990 and 1996, wells drilled with 3D seismic hit 49% of the time, against 14% for wells drilled without it. Over those same years, the share of Amoco’s prospects covered by 3D rose from 1% to 65%, and its cost of finding a barrel of oil fell dramatically – from $8 to less than $1.

And what came next made it virtually impossible to drill a dry hole.

Texas real estate developer George Mitchell spent 17 years and roughly a quarter of a billion dollars drilling the Barnett Shale in North Texas without turning a profit. In 1997, one of his engineers, Nick Steinsberger, replaced the expensive gel in the well’s fracturing fluid with water slickened by a trace of chemicals. The following year that well, S.H. Griffin No. 3, out-produced every well the company had ever drilled.

Mitchell did not discover where the gas was. Everybody already knew where the shale was: it covered thousands of square miles. What Mitchell proved was, with the right chemistry, gas could be manufactured out of that rock.

That’s what I mean when I say that drilling stopped being exploration and became engineering. Today the challenge isn’t finding oil and gas. Development wells in proven shale succeed 85% to 95% of the time. Today the challenge is purely engineering: how efficiently can you drill a given area of shale?

In 2010, the horizontal section of the average new Permian Basin well ran 3,870 feet. By 2025, it ran 10,867 feet and 15% of new wells now stretch past three miles. Occidental Petroleum (OXY) cut its drilling time in the Wolfcamp shale (within the Permian in West Texas) from 43 days per well in 2014 to 26 days in 2015, and the best operators now drill these wells in 13 days. Output per Permian rig went from 130 barrels a day in 2014 to 800 barrels a day by 2019.

Nobody found more oil. They engineered more oil.

Drug discovery is making that same turn right now. Artificial intelligence (“AI”) will play a growing role in testing new drug targets. Much like 3D seismic, AI will dramatically reduce the cost of discovery. The key to success in the drug business will be engineering – figuring out more efficient, more effective, and cheaper ways of hitting the best targets.

Our portfolio will be built around who owns the best engineering.

Chronicling The Remarkable Breakthroughs

As you know, our strategy in Porter & Co. Biotechnology is always to follow the science.

In the month of August, there were two Nobel Prize-worthy technological breakthroughs that I’d like to share with you.

⚙ Edit 🗑 Delete

Porter further expands on the portfolio that he developed last month – with two of his newest recommendations up more than 30%. To see the remainder of this issue, new recommendations, and full access to the Porter & Co. Biotechnology portfolio, click here.

The most important breakthrough was on August 19. Merck (MRK) and Moderna (MRNA) announced a seminal breakthrough in the treatment of solid cancer tumors, the first successful Phase III trial of an individualized mRNA cancer vaccine. This new class of medicine holds the promise of stopping solid tumors from metastasizing following surgical removal.

Six days earlier, the New England Journal of Medicine published the details of a successful application of gene editing, in which a single infusion permanently rewrote the genetic code of human liver cells. The result dropped patient LDL levels by 62%, permanently.

The point made by highlighting these discoveries – which you’ll see me driving home in Biotechnology – is that we are living through a period of profound medical innovation. We’re getting closer to delivering cures at the cellular level by simply rewriting DNA – stopping disease before it can even begin.

And today, no one in the world understands the engineering behind drug discovery and optimization better than Eli Lilly (NYSE: LLY).

Yes, I know that’s a major pharmaceutical company. But we follow the science. Here’s what I mean.

The successful gene-editing program that I described above, the one that permanently reduced LDL in patients, is owned by Verve Therapeutics. Harvard cardiologist and human geneticist Skar Kathiresan founded Verve because his brother died of a heart attack at 42. Kathiresan founded the company to stop treating heart disease as a chronic condition by installing the natural protective mutations that nature already gives some people. In other words, rewrite the code of life inside your cells to give you nature’s best protection from heart disease. Obviously, the potential value of this technology is enormous, and it could have many applications beyond cardiology.

Verve’s initial funding came from Alphabet (GOOG) in May 2019. It went public in June 2021, during the massive post-COVID tech stock boom. On its first day, it gained 68%.

The company has three main programs. The breakthrough program that just published its results is VERVE-102, which is targeting PCSK9 for LDL cholesterol. It has Food And Drug Administration (“FDA”) Fast Track designation and is very promising.

The company’s next program is called VERVE-201. It’s targeting another gene in the liver (ANGPTL3) that makes a protein whose job is to put the brakes on fat clearance. It inhibits two enzymes (lipoprotein lipase and endothelial lipase) that pull triglycerides and cholesterol out of the bloodstream. Silence that gene, the brakes come off, and blood fats clear faster. It is unusual in that it moves all three lipid measures (LDL, triglycerides, and HDL).

Again, the company knew to target this particular gene because people who naturally have one broken copy of ANGPTL3 have 17% lower triglycerides, 12% lower LDL, and 34% lower odds of coronary artery disease. People with two broken copies of this gene have a recessive condition called familial combined hypolipidemia – very low triglycerides, LDL, and HDL – and they are healthy. Losing this gene entirely costs you nothing but gives you much better cardio health.

And then there’s VERVE-301, which targets lipoprotein(a) – Lp(a) – which I wrote about last month. This is the largest potential target in all of cardiology.

So what does this have to do with Eli Lilly? Lilly is the best in the world at finding the best targets and building the best therapeutics. In June 2023, Lilly signed a global research collaboration with Verve on its pre-clinical Lp(a) gene-editing program, paying $60 million upfront. After the results of VERVE-102 (targeting PCSK9) were first published last spring, Lilly bought Verve Therapeutics for $1 billion. That was $10.50 per share, which was less than the initial public offering (“IPO”) price and about 86% below the stock’s all-time closing high of $73.99 (set September 10, 2021).

Ruth Gimeno, Lilly’s group vice president for diabetes and metabolic research and development, described the deal as a chance to “shift the treatment paradigm for cardiovascular disease from chronic care to one-and-done treatment.”

This is more than just another modality. This is the difference between a treatment and a cure, and it could profoundly reshape the entire drug industry. I’ve told you that I believe gene silencing will be the best-performing modality over the next 20 years. But what if there aren’t any genes to silence because they’ve all been edited away?

Here are three points about that…

  1. Gene silencing will be used for a long time because changing your DNA permanently carries a lot of unknowns, and it may be irreversible. An edited genome has no off switch and no antidote. There will be a lot of people who are more comfortable taking a therapy once or twice a year – knowing that if something changes, they can always change therapies.
  2. Dosing has value too. A physician titrates silencing: more drug suppresses more protein, less drug suppresses less, and the dose can be adjusted as the patient changes. An edit delivers whatever suppression the editing efficiency achieved, forever. Where the safe range is narrow, or where medicine wants to reduce a protein rather than eliminate it, the adjustable drug wins.
  3. And then there’s the financial question. Insurers know how to pay for a twice-yearly injection, because they pay for thousands of chronic drugs that way. A one-time cure demands a single enormous payment with no established mechanism for spreading that cost across the decades of benefit it delivers. That is precisely why gene therapy has been such a commercial disappointment so far. BioMarin Pharmaceutical (BMRN) pulled a hemophilia gene therapy off the market entirely, despite the drug working because nobody would pay for it.

And regulators discriminate too. An irreversible intervention requires longer follow-up, mandatory patient registries, and restrictions confining early use to the sickest patients. For a 45-year-old managing a chronic condition, the reversible drug clears approval faster and reaches the prescription pad sooner.

Cholesterol treatment already works exactly this way. Statins come as daily pills. Antibodies against PCSK9 are injected twice monthly. Alnylam Pharmaceuticals (Nasdaq: ALNY) and Novartis’ (NYSE: NVS) Inclisiran (Leqvio) silences PCSK9 twice a year. And Verve’s gene-editing technology can rewrite it away once. Four technologies, one disease, and the market will determine who gets these drugs by how sick the patient is, how old, how reliably they take medication, and who is paying.

In other words, I don’t think gene editing is as big a risk to gene silencing as gene silencing is a risk to other modalities. I believe, going forward, more disease is going to be treated at the cellular level by silencing genes or editing them.

There’s no question that Lilly will be a leader in this field. And yes, I know its shares trade for more than $1,000 and the company’s enterprise value is more than $1 trillion. But that’s cheap compared to what the company will earn over the next decade.

Specifically, today you’re paying 25.5x what analysts expect Lilly to earn next year. Consensus estimates put earnings at $36.39 per share this year and $46.62 next year, on revenue climbing from $88.3 billion to $101.8 billion. And I believe revenue growth will far surpass these estimates.

The reason isn’t gene editing. Or even the company’s weight loss shots. The reason is a pill that’s going to transform human health.

Eli Lilly Is Medicine’s Nvidia

Novo Nordisk’s (NVO) Ozempic and Wegovy and Lilly’s Mounjaro and Zepbound are the current best-selling weight-loss shots. These therapies are peptides: a short chain of amino acids. Chemists build them the way a jeweler strings a necklace together. They anchor the first amino acid to a plastic bead, couple the second amino acid onto it, chemically unmask the new end so a third can attach, wash the bead in solvent, and repeat.

Tirzepatide, the molecule inside Mounjaro and Zepbound, runs 39 amino acids long. Every link demands its own coupling, unmasking, and washing cycle. Then there’s a purification process, which pushes dilute liquid through columns the size of oil drums for days. It’s a chemical engineering marvel. It is also expensive.

But orforglipron, Eli Lilly’s weight-loss pill, isn’t a peptide. It’s a small molecule.

Chemists make this drug the way they make aspirin or the cholesterol drug Lipitor: a handful of reactions, solid crystals you can filter and weigh at each stage, and purification by crystallization instead of chromatography. Thus, small molecule drugs are vastly cheaper to make than peptide chains.

The industry measures what a process costs to run using process mass intensity (“PMI”). Weigh everything you feed into the manufacturing line, the reagents, solvents, water, all of it, and divide by the weight of finished drug that comes out the other end. PMI captures manufacturing cost better than any other single number because solvent purchase and solvent disposal, not raw ingredients, dominate the bill. The American Chemical Society’s Green Chemistry Institute collected real production data from 14 pharmaceutical companies across 40 peptide manufacturing processes. Peptides consume 13,063 kilograms of input for every kilogram of drug delivered. Small molecules consume roughly 200.

Solvent accounts for roughly 44% of that mass. It’s expensive and frequently toxic. One solvent, dimethylformamide, generates 39% of all the waste. European regulators classified dimethylformamide as a Substance of Very High Concern and restricted it in December 2021 over reproductive toxicity. Piperidine, the reagent that unmasks each link on a peptide chain, sits on the Drug Enforcement Administration’s controlled-chemical list. Peptide plants have enormous compliance costs.

Over time, chemical engineers can drive costs out of small-molecule production. That’s why generic pills cost pennies. But peptide manufacturing shows no such expense-curve improvement between early development and commercial scale. It doesn’t get easier to make at scale.

The weight-loss market won’t be won by finding a better target. Incretins (GLP-1s) are incredibly safe and effective. The weight-loss market will be won by producing and marketing enormous quantities of these drugs at vastly lower costs. Much like a shale field, this market is not about discovery. It is an engineering battle. And Lilly has won.

I predict that Eli Lilly’s pill won’t just garner a lot of the market. I expect it will garner virtually all the market, better than 90% share over the next decade, for one simple reason: it’s vastly cheaper to produce and to distribute.

But wait a minute, Porter, wasn’t Novo Nordisk first to market with a GLP-1 pill?

Yes, Novo got there first. But it did it by manufacturing its peptide into a pill. That isn’t easy to do. It’s also very expensive because, in pill form, it requires vastly more of the GLP-1 peptide, semaglutide. And that’s an important point.

Bioavailability measures the fraction of a swallowed dose that survives the stomach and intestine and arrives in the bloodstream intact. Stomach acid and digestive enzymes exist specifically to dismantle proteins into their component amino acids, and a peptide is a small protein. Thus, your stomach treats oral semaglutide as lunch.

The FDA measured oral semaglutide’s bioavailability two separate ways during its review and got 0.471% and 0.795%. Swallow 1,000 units of oral semaglutide, and only five to eight of them reach your bloodstream, while the gut destroys or expels the other 992. In other words, Novo’s pill is an extremely inefficient delivery vehicle.

Novo tried to engineer a solution. Every tablet of Rybelsus, Novo’s original semaglutide pill, carries 300 milligrams of an absorption enhancer called salcaprozate sodium, which raises the pH immediately around the tablet so the peptide slips across the stomach lining before enzymes reach it. But there’s a problem: absorption still collapses under ordinary conditions. In the food-effect study Novo filed with the FDA, 14 of 26 subjects who swallowed the tablet after a meal showed no measurable semaglutide in their blood at all. None. The label therefore instructs patients to dose on an empty stomach, with no more than 120 milliliters of plain water, and to eat, drink, or take nothing else for at least 30 minutes.

Good luck in the real world.

Injected Wegovy delivers 2.4 milligrams once weekly, which is about 10.3 milligrams of semaglutide per patient per month. The approved Wegovy pill delivers 25 milligrams every day. Call it 750 milligrams a month. Switch a patient from the Wegovy injection to the Wegovy pill, and that patient consumes 73x more semaglutide than they did on the shot, whether any of it reaches their bloodstream or not. Every additional milligram must come out of the same peptide plants that took Novo five years and $10 billion a year to build. Now think about trying to serve a billion people that pill every day. That’s not going to scale.

Researchers priced generic semaglutide across formulations using 33 active ingredients. A year of the injection can be produced for well under $150, and most of that isn’t the drug at all: it’s the disposable injector pen. A year of the 14-milligram pill costs about $360 to produce. And Novo’s weight-loss pill isn’t 14 milligrams. It’s 25 milligrams. Our estimate is that Novo’s pill costs the company 4x to 5x as much as its injection costs to make.

Now, perhaps some people would pay more for a pill – but not many. And especially not when there’s a pill that’s cheaper and vastly more effective in real-world dosing.

Lilly’s orforglipron, approved April 1 and sold as Foundayo, is a small molecule that delivers 30% to 40% of a swallowed dose into the bloodstream. It needs no absorption enhancer and imposes no food restriction. It absorbs 40x to 100x more efficiently than oral semaglutide, and it belongs to a chemical family that costs one-50th as much to produce.

The cost of making enough semaglutide to enable pill production shows up in Novo’s financial statements. Novo’s gross profit margin fell from 84.9% in Q2 of 2024 to 78.2% in Q2 of 2026. Its capital spending has climbed from 6 billion kroner in 2021 to 60 billion kroner in 2025 (or US$935 million rising to US$9.4 billion), a 10-fold increase in four years. Novo also paid $16.5 billion in cash to buy the contract manufacturer Catalent (formerly CTLT) outright, purely to get its hands on more pen-filling capacity.

You can see how Novo is dealing with the threat from Lilly’s superior chemistry by watching Novo’s mergers-and-acquisitions activity. In May 2025, Novo Nordisk agreed to pay Septerna (SEPN) more than $200 million up front as part of a $2.2 billion deal for access to a platform that discovers small molecules acting on the same receptors Novo’s drugs target. Novo funds all the research. In February, it committed up to $2.1 billion to Vivtex, an MIT spinout, for a robotic screening system that tests thousands of formulations a day looking for ones that let a peptide survive the gut.

The battle isn’t about discovery anymore. The battle is engineering. When Lilly begins to compete on price, how will Novo recoup the cost of these massive investments? My bet: it won’t.

Lilly told investors a year ago that it expected to launch Foundayo worldwide without supply constraints. No peptide manufacturer can make that promise. Novo spent 2022 through 2024 rationing semaglutide, restricting starter doses and warning patients of shortages, because it could not make the peptide fast enough. Lilly, meanwhile, manufactured its pill before the FDA had even approved it. Its 2025 annual report disclosed $1.5 billion of pre-launch inventory sitting on the balance sheet as of December 31. Billions of tablets, ready to be sold.

Foundayo launched on April 1 at $149 a month for the starting dose through Lilly’s own pharmacy, rising to $349 per month at the maintenance dose. Patients with commercial insurance pay as little as $25 a month. Eligible Medicare patients pay $50 a month beginning July 1. Novo is competing with a list price near $1,349 for its semaglutide pill. Who is going to buy it?

Lilly launched Foundayo in Britain on August 23. Private providers there sell it at £100 to £120 a month ($136 to $163). Mounjaro, Lilly’s own injection, lists at £133 a month for the starting dose and £330 for the highest. So Lilly priced its pill below the cheapest injection it sells.

Lilly has filed orforglipron for approval in more than 40 countries. It filed with China’s National Medical Products Administration at the end of 2025, for both obesity and type 2 diabetes. In March, it committed another $3 billion over 10 years, adding tablet production in Beijing and expanding injection capacity at the plant it has run in Suzhou since 1996. That takes Lilly’s total investment in China to nearly $6 billion.

In total, Lilly has committed more than $50 billion to manufacturing since 2020. It’s building a $6.5 billion chemical plant in Houston to keep ramping Foundayo. It’s building a $3.5 billion injectables factory in Lehigh Valley, Pennsylvania, for its forthcoming new peptide, retatrutide. The plant won’t open until 2031 – so clearly Lilly believes there’s a vast amount of future demand for metabolic health products. And I believe they’re right.

Apple (AAPL) has shipped 2.64 billion iPhones as of March 31, 2026. Cumulative iPhone revenue since 2007 runs well past $2 trillion. The iPhone is, by far, the best-selling consumer product of all time. But I believe Lilly’s portfolio of metabolic health products will surpass Apple’s iPhone revenue. Do other analysts see this kind of potential? Morgan Stanley puts the combined diabetes and obesity market at $190 billion a year by 2035.

And with its next drug (retatrutide), Lilly will show the world what’s truly possible with this class of drugs.

Lilly’s current GLP-1 product, tirzepatide, activates two gut-hormone receptors. GLP-1 tells the pancreas to release insulin after a meal, slows how quickly the stomach empties, and signals the brain that eating can stop.

GIP is the second receptor, and it is the reason Lilly’s shot outperforms Novo’s. GIP stands for glucose-dependent insulinotropic polypeptide. Like GLP-1, it is a hormone your gut releases within minutes of food arriving, and like GLP-1, it tells the pancreas to make insulin. But GIP is different from GLP-1 in two critical ways. First, it acts directly on fat tissue, improving how efficiently fat cells absorb and store energy instead of leaving that energy to circulate in the blood. Second, and commercially more important, GIP appears to raise the threshold at which the brain triggers nausea. That means a drug hitting both receptors can be pushed to a higher dose before patients quit. Most of tirzepatide’s advantage over semaglutide comes from that headroom.

Hitting both receptors produced $9.9 billion of Mounjaro sales and $4.9 billion of Zepbound sales in Q2 of this year alone. The molecule’s composition-of-matter patent, the patent covering the substance itself and the hardest kind to work around, runs in the United States until January 5, 2036. But long before this patent expires, Lilly will have innovated much better drugs. And sold billions of pills.

The next innovation is retatrutide, which is a GLP-1 peptide that adds a third receptor. Glucagon is insulin’s mirror image. When your blood sugar falls, the pancreas releases glucagon, and the liver answers by breaking down stored glycogen and pushing glucose back into the blood. Adding a glucagon receptor to a weight-loss drug sounds backwards, since you are deliberately stimulating the hormone that raises blood sugar. What you buy is energy expenditure. Glucagon signaling raises the rate at which the liver burns fat and lifts resting metabolic rate.

So tirzepatide works the intake side of the equation: it reduces how much a patient eats and improves how well the body handles what does get eaten. Retatrutide adds the output side. The patient eats less and burns more. Lilly expects to file for approval in Q1 2027. Retatrutide gives Lilly an edge that many customers will pay up to receive.

Meanwhile, today Eli Lilly trades at 28x next year’s consensus earnings, which is only a small premium to the market.

Action to Take: Buy Eli Lilly (NYSE: LLY) below $1,500 per share

As with our other major pharma recommendation – Novartis (NYSE: NVS) – we recommend using an 80/20 allocation on this position, where you invest 80% of your capital into the equity and 20% of your capital into a long-dated call option with a strike price that is between 5% and 10% “out of the money.”

Moderna’s New Personalized Cancer Vaccine

In 1891, a New York surgeon named William Coley began injecting live streptococcal bacteria directly into tumors he could not cut out. He had noticed that patients who developed raging post-surgical infections sometimes watched their cancers shrink. He treated more than 1,000 patients and documented cures above 10% in cancers that otherwise killed everyone. Parke-Davis, later absorbed into Pfizer (PFE), sold a version of his toxin from 1899 until 1951.

The logic never changed: the immune system can kill cancer, and it will do so if you show it the right target.

Researchers identified the first usable molecular target on tumor cells in 1991. Dozens of companies then spent 20 years and billions of dollars building vaccines against targets like it. Nearly all of them failed for the same reason. Those targets were the patient’s own proteins, present at low levels in healthy tissue and merely overproduced by the tumor. Your immune system spends enormous effort learning not to attack your own proteins, because attacking them causes autoimmune disease. Training it to break that rule means overriding a safety system, and the safety system usually wins.

Subscribers who followed my work in the mid-2000s will remember Antigenics, which trades today as Agenus (AGEN). Antigenics manufactured a vaccine called Oncophage individually from each patient’s own surgically removed tumor. Genuine personalized medicine, 20 years too early. Its Phase III trial in kidney cancer randomized 818 patients. The hazard ratio for recurrence came in at 0.923, with a confidence interval running from 0.729 to 1.169 and a p-value of 0.506.

(Editor’s note: There are three critical numbers to know from any clinical trial. First, the hazard ratio compares how fast bad events happen in the treated group against how fast they happen in the control group. Read it like this: 1.0 means both groups suffered at identical rates and the drug did nothing at all. A 0.51 hazard ratio means the treated patients relapsed at roughly half the rate. Lower is better. A confidence interval brackets the range the true answer probably falls inside, given how few events the trial actually observed. If that range crosses 1.0, the drug might have done nothing, and the headline number could be noise. The p-value estimates the odds of seeing a result that large by pure chance if the drug were inert. Regulators generally want it below 0.05.)


The point estimate suggested 8% fewer recurrences. The confidence interval crossed 1.0 in both directions, meaning the vaccine might have helped by 27% or harmed by 17%. The p-value said a coin flip explains the whole result. Antigenics collapsed, renamed itself Agenus in January 2011, and built a business around the adjuvant Antigenics used to provoke an immune response (QS-21).

Dendreon (formerly DNDN) came next. Its personalized cancer vaccine, Provenge, was grown from each patient’s own immune cells. It won its Phase III trial, extending survival in prostate cancer by 4.1 months at a hazard ratio of 0.78. The FDA approved it in 2010. It showed no effect whatsoever on how fast the cancer progressed.

Then Dendreon priced it at $93,000 a course and… no one bought it. The company filed for bankruptcy in November 2014, and on May 6, 2015, the European Commission withdrew Provenge’s marketing authorization across the entire European Union. Not for safety. Not for efficacy. Dendreon requested the withdrawal itself, because it could not get European payers to reimburse for the drug.

In 2007, Genitope ran 287 patients through a lymphoma vaccine trial and delivered 19 months of progression-free survival versus 23 months on control. Worse than nothing. The stock halved the day the results came out. It delisted it nine months later.

After all these failures, most people assumed that personalized cancer vaccines would never work. But then three things changed.

First, the targets changed. Instead of vaccinating against the patient’s own normal proteins, laboratories now sequence the tumor’s DNA alongside the patient’s healthy DNA, subtract one from the other, and isolate the mutations that exist only inside the cancer. Those mutated proteins are genuinely foreign. These proteins are called neoantigens.

Second, checkpoint inhibitors arrived. Tumors survive by displaying molecular signals that switch off immune cells as they approach. Checkpoint inhibitors like Merck’s Keytruda block those signals. The old vaccines were pushing immune responses into a system the tumor could turn off at will, which is precisely why they generated beautiful laboratory data but didn’t save patients. Now that switch gets disabled.

Third, as we’ll be discussing for years, the engineering has gotten much better. mRNA (messenger RNA) solved the delivery problem: it carries the instructions directly into a cell, so the patient can make precisely the right antibodies. Encode dozens of neoantigens and the patient’s own body will manufacture all of them. Moderna’s product encodes up to 34 antigens, matched to that individual’s specific cancer. Production time fell from 50 or 60 days to about six weeks.

The individualized product cut recurrence at a hazard ratio of 0.51, with a confidence interval of 0.294 to 0.887 and a p-value of 0.0075.

In other words, the vaccine reduced cancer’s recurrence by about 50% – an outcome that was almost impossible by chance alone.

While the intellectual property around these vaccines and their delivery systems is, of course, complicated (like all IP in biotechnology) Moderna’s durable advantage rests on two assets that offer a moat beyond patents.

The first is the algorithm that picks which mutations go into the vaccine. In the largest published benchmark, ranking candidate neoantigens by how tightly they stick to the immune system’s display molecules identified genuinely useful targets less than 20% of the time. Filtering instead for whether the fragment actually appears on the cell surface, and whether a T-cell can recognize it, lifted accuracy above 70%. The clinical numbers are harsher still. Only 2% of computationally predicted neoantigens provoke a response in the laboratory. And in a pancreatic trial run by BioNTech SE (BNTX), only 11% of the selected targets produced a detectable immune response in patients.

Moderna’s vaccine holds 34 slots. At an 11% hit rate, four of them are doing something; at 70%, 24 are. Moderna’s algorithm is producing a better vaccine. And that advantage widens with every patient Moderna treats and learns from.

The second asset is Moderna’s factory. Every manufacturing batch treats exactly one patient. Moderna’s annual report states that the process scales out in parallel rather than up: you cannot build a bigger vessel and serve more people; you have to replicate the entire line. Moderna’s total dedicated capacity consists of one building: 140,000 square feet in Marlborough, Massachusetts. It cost around $400 million to build. Across the 10 solid tumors where this approach could work, American surgeons treat roughly 815,000 operable cases every year. Virtually every patient would want a personalized cancer vaccine, if having one meant a 50% better chance of extending cancer-free remission over a meaningful period (years). So, for now, it’s Moderna’s one building, against 815,000 American patients a year.

Currently, Moderna has no close competitor at all. BioNTech runs the only comparable program at scale and expects no pancreatic results before 2031. Genentech, the Roche Holding AG (SWX: ROG) subsidiary, abandoned its cancer vaccine partnership with the Norwegian developer Nykode Therapeutics.

Over the trailing 12 months through June 30, Moderna revenue was $2.23 billion and gross profit was $521 million, a gross margin of 23.4%. Research spending consumed $2.88 billion, 5.5x gross profit. The operating loss was $3.32 billion, or $7.99 a share. Moderna holds $6.91 billion of cash and investments with no reported debt, and it burns $1.24 billion a year, leaving 5.6 years of runway.

Analysts expect Moderna to lose $4.93 a share next year on $2.40 billion of revenue. Consensus is modeling almost no cancer-vaccine revenue at all through the end of 2027. Strip out the cash, and the market is valuing this business at $51 billion.

Moderna’s partner in this pivotal trial was Merck, which is seeking ways to extend the patent life of its best-selling checkpoint inhibitor, Keytruda. Merck books the sales and the two companies split the profits equally. Sell-side analysts put peak melanoma sales at $5.4 billion per year. Our base case assumes the vaccine reaches melanoma and lung cancer, which gets us to $11.4 billion in peak franchise revenue per year. Assuming 38% operating margin, that throws off $4.3 billion of profit per year. Moderna keeps half. As an estimate (we don’t know how long it will be before competitors emerge), we’ll use a 13-multiple on these earnings. That gets us to a future total value of $28 billion. But this market could easily grow much larger. Broad adoption across solid tumors at costs below $45,000 gets us to $92 billion.

Discounting those future values back to today yields a potential present value of $11 billion to $36 billion. On a Moderna per-share basis, that’s $27.56 or $90.42. That’s a very wide range of potential value for an investor to estimate today – welcome to biotech investing! And it’s even more difficult in this case because this entire approach is new, is extremely expensive, and doesn’t scale easily.

Manufacturing costs more than $100,000 per patient today. And this drug gets given to people whose cancer has already been cut out, who show no detectable disease anywhere in their bodies, and who feel completely fine. That’s a lot of money for an insurance company to approve… to someone who is currently healthy.

Provenge worked. It won its trial, and the FDA approved it. Then it was pulled out of Europe entirely, because payers would not shell out $93,000 for a drug given to patients who were not visibly, terminally ill. Moderna and Merck are proposing a six-figure therapy for patients who, while at great risk for further disease, are not currently sick. Who will pay that much?

One more thing. After Merck and Moderna announced that the trial met both of its endpoints, the market added $36 billion to Moderna’s value. That’s the present value of my most aggressive forecast for this product. I estimate that fair value on Moderna’s other business lines (an approved COVID vaccine, an approved RSV vaccine, a late-stage flu program) and its associated intellectual property is worth something around $15 per share. Add this to my estimates on the present value of the cancer vaccine, and you get something between $45 and $110. But the stock is trading above that – at $140 per share! Too expensive to recommend right now.

I suspect we will see a major pullback in Moderna’s shares at some point as the difficult economic reality of a $100,000 cancer vaccine plays out.

But what about Merck? Merck collects the other half of the vaccine profits; it sells the Keytruda that the vaccine must be given alongside, and it trades at only 16.1x what analysts expect it to earn in 2027. Keytruda generated 48.7% of Merck’s 2025 revenue. And Keytruda loses United States exclusivity in 2028. The stock has been trading very cheaply because of the risks Merck faces with the Keytruda patent cliff. I bought it personally earlier this year primarily because of its dividend and because it’s a very high-quality, low-volatility stock that fits with my “Honeycomb Strategy.” I didn’t buy it because of the cancer vaccine – in fact, before I took up this work in July, I didn’t know anything about Moderna’s cancer vaccine. But the shares jumped on that news and are now up 40% year-to-date. No, it’s not an expensive stock. But it’s not cheap anymore. I’m going to pass for now. If there’s a big drawdown, I’ll do a complete review of it.

Portfolio Review And Actions

Present value is our estimate of what a share is worth today on the evidence in hand. It’s not a price target, as we believe in letting our winners run. We don’t want to sell a great business when we have a good entry price. Buy below is the highest price at which we would put new money to work.

Eli Lilly enters at our 14% cap for integrated and tollbooth businesses, sized by inverse volatility alongside Novartis (NVS). Moderna would enter under our 10% cap for companies with marketed products, once it trades below $110.

Big Month Of News For uniQure

uniQure (Nasdaq: QURE) is a Hold.

Its AMT-130 is a gene therapy for Huntington’s disease. Huntington’s is caused by a single inherited defect that makes a mutant protein which slowly kills neurons in a part of the brain called the striatum. Patients lose motor control, then cognition, then everything, over 15 to 20 years. There is no treatment that changes the course of the disease.

AMT-130 is delivered by a neurosurgeon, through the skull, guided by MRI, directly into the striatum, in a single procedure. A viral vector carries instructions that make neurons produce a small RNA that silences the mutant gene.

Two things will happen this month. uniQure will present four-year data with a June 30 cutoff, covering 12 high-dose and 12 low-dose patients. The three-year data (previously published) is why the stock has tripled. On the primary measure – a composite score built from motor, cognitive, and functional tests – treated patients declined 0.38 points against 1.52 for an external control group, a 75% slowing, at p equal to 0.003. Functional capacity slowed 60% at p equal to 0.033. That is the most convincing result anyone has produced in Huntington’s disease.

September’s presentation is evidence about durability, and we suspect it will report data that’s stronger than the three-year data. We also believe this drug will receive approval this year, despite the very small number of patients and the lack of a real control group.

There’s a lot of history here. On November 3, 2025, FDA’s pre-submission feedback said it no longer agreed the Phase I/II data were adequate as primary evidence and the data were “currently unlikely” to support a filing. The shares fell from $67.49 to roughly $26. In June 2026, after a follow-up meeting, the agency reversed and agreed that the three-year analysis is acceptable as the primary basis for accelerated approval.

Here’s the real problem: uniQure has no placebo arm. These trials compared treated patients against a matched set drawn from Enroll-HD, an observational registry, selected by a statistical technique that pairs patients on baseline characteristics.

In February 2026, the FDA rejected a gene therapy for Hunter syndrome under similar circumstances: uncertainty in the eligibility criteria, comparability of the natural-history control, and the appropriateness of the biomarker. The agency noted that the control group was mismatched on age and baseline cognition.

uniQure’s filing rests on the same architecture: a small, treated cohort against a matched external control.

In addition, this division of the FDA has spent 2026 tightening the screws on gene therapy delivered to the brain. In January, it halted two REGENXBIO trials after a tumor appeared in an asymptomatic five-year-old dosed four years earlier, and the resected tumor showed viral genetic material integrated next to a cancer-causing gene called PLAG1. Causality was never established, and no other patient in either trial had a tumor. In August, the agency halted the same program again after spine imaging in five patients turned up small nodules, all judged benign. And in November 2025 the FDA put a boxed warning on Sarepta’s Duchenne gene therapy for fatal liver injury and pulled the indication for non-ambulatory patients.

The FDA is very worried about using viral vectors for gene therapy… and it’s easy to understand why.

But we think it’s likely that uniQure will get approval because there’s no other possible therapy and these results look strong. In 2023, the FDA granted accelerated approval to Qalsody for a form of ALS on the strength of a reduction in neurofilament light, a protein that leaks out of dying nerve cells, in 108 randomized patients. uniQure’s neurofilament data was 8.2% below baseline at three years on the high dose. We think there’s enough proof that the therapy is slowing the disease to warrant approval.

And so, we’ll hold.

Silence Therapeutics Closer To Divesiran Approval

Silence Therapeutics (Nasdaq: SLN) remains a Speculative Buy with a raised buy price.

Polycythemia vera is a blood cancer in which the bone marrow makes too many red cells, the blood thickens, and thick blood clots. The standard treatment has not fundamentally changed in a century: a nurse drains blood out of the patient, therapeutic phlebotomy. The body already has an off switch for making red blood cells. It’s a hormone called hepcidin that controls how much iron is available to the marrow. Iron is the raw material for red cells, so turning hepcidin up starves the marrow of what it needs and fewer red cells get made.

There are two ways to raise hepcidin. You can inject synthetic hepcidin, or you can help the patient produce more of his own. Protagonist Therapeutics (PTGX) and Takeda Pharmaceutical (TAK) took the first route with a peptide called rusfertide, and on August 28 the FDA approved it as Mimrylo.

Silence is taking the second approach. Divesiran is a small interfering RNA that silences a gene called TMPRSS6, whose protein is the brake on the body’s own hepcidin production. Release the brake, and the patient makes more of their own hepcidin.

Until August 28, the case for divesiran rested on a theory: that raising hepcidin controls polycythemia vera. The FDA has now approved a drug that does exactly that, on the strength of a randomized Phase III trial in 293 patients. The mechanism is no longer a hypothesis but a labeled indication. Mimrylo won approval on a single endpoint: the share of patients who did not become eligible for phlebotomy between weeks 20 and 32. Eligibility was defined precisely, as a confirmed hematocrit at or above 45% that also ran at least three points above the patient’s own baseline, or a hematocrit at or above 48%. Silence now knows the endpoint, its exact definition, and the trial size it will require to gain approval.

This new drug also begins to build the market for this kind of therapy. Somebody has to persuade hematologists to stop draining blood and start writing a prescription, and somebody has to get insurers to pay for it. Takeda has both the sales force and every incentive to do that work. Silence arrives after the category exists… but it will be second to market. What does that mean? Mimrylo is a once-weekly injection. Divesiran is one injection every twelve weeks. That’s fifty-two injections a year against four.

Regarding efficacy, Silence’s Phase II produced 88% clinical responders against 19% on placebo, at p below 0.0001, in 48 phlebotomy-dependent patients. Mimrylo produced 76.9% responders against 32.9% on placebo.

Silence sold $175 million of stock at $13.50 (right above our buy-up-to price) on the strength of the divesiran data.

We are raising our buy-below price from $13 to $16 and our present value estimate to $22.

Keeping A Watch On Arrowhead Pharmaceuticals

Arrowhead Pharmaceuticals (Nasdaq: ARWR) remains on the watchlist..

Plozasiran is a small interfering RNA (siRNA) that silences APOC3, a gene whose protein blocks the body from clearing fat out of the blood. Silence it, and triglycerides fall. It is injected under the skin once every three months. The FDA approved it on November 18, 2025, as REDEMPLO, for familial chylomicronemia syndrome, a genetic disorder affecting roughly 6,500 Americans. Arrowhead’s management has set the wholesale price at $45,000 per patient per year. In the June quarter, REDEMPLO produced about $2.4 million of revenue across more than 400 prescribers, roughly double the prior quarter.

Expanding the label is the company’s strategy. Roughly 2.3 million American adults carry triglycerides above 500 milligrams/deciliter (“mg/dL”), based on two decades of federal health survey data. Arrowhead will file for that population before the end of this year. And, on August 30, at the European Society of Cardiology congress in Munich, the company presented the trial data to support the filing. SHASTA-3 and SHASTA-4 randomized 757 adults to four quarterly doses or placebo. Triglycerides fell 79% and 81% at 12 months, both at p below 0.0001, and 85% in patients who started above 880 mg/dL.

Very high triglycerides cause acute pancreatitis, a sudden inflammation of the pancreas that hospitalizes patients and sometimes kills them. Pooled across both trials, pancreatitis events fell 78%, In patients who had already survived one attack, events fell 91%. Safety was clean: serious adverse events were 8.3% on drug against 10% on placebo, and 1.4% of patients discontinued against 0.8% on placebo.

Arrowhead isn’t the first to market here. On June 24, the FDA approved Ionis Pharma’s olezarsen as Tryngolza for the same population. Arrowhead’s competitive answer is dosing and depth: olezarsen is a monthly autoinjector, and plozasiran is quarterly. Olezarsen cites a 66% triglyceride reduction against Arrowhead’s 79% to 81%, and an 85% pancreatitis reduction against Arrowhead’s 78%.

Arrowhead carries roughly $1.22 billion of debt against $1.57 billion of cash and investments. The largest piece is a $400 million senior secured loan from Sixth Street. Interest runs at 15%, payable in kind rather than in cash, secured by a first lien on substantially all assets including the intellectual property itself. The company also has $700 million of zero-coupon convertible notes due January 2032 with a conversion price near $87.07.

Our $85 present value is built in four steps. We start with Morgan Stanley’s $3.2 billion peak plozasiran estimate, which that firm doubled from $1.7 billion in April, and value it at three times peak sales. We add $2 billion for the partnered royalty streams on olpasiran with Amgen and fazirsiran with Takeda, plus the obesity programs. Then we add the cash and subtract the debt. At $81.38, you are paying 3.5x Morgan Stanley’s peak-sales estimate for the whole enterprise, on a drug that is second to market with an interest bill that compounds at 15%.

We are keeping a watch on Arrowhead Pharmaceuticals until we see a price decline. We hope there’s a pullback in biotech this fall that allows us a good entry price.

Halozyme: Adding Another Tollbooth

Halozyme Therapeutics (Nasdaq: HALO) joins the recommended list with a Buy Below of $110, with a present value of $124.

Most antibody drugs have to be dripped into a vein, which means the patient sits in an infusion chair for hours and the hospital bills for a nurse, a chair, and a bag. Halozyme owns an enzyme called rHuPH20 that temporarily loosens the mesh of tissue under the skin, so the same drug can be pushed in with a syringe in minutes. It licenses that enzyme to drug companies under the name ENHANZE and collects a royalty.

Halozyme runs no trials, treats no patients, and files for no approvals. Roche Holding (SIX: ROG), Johnson & Johnson (JNJ), Takeda Pharmaceutical (TAK), Argenx (ARGX), and Bristol-Myers Squibb (BMY) do all of that. Halozyme cashes checks.

In June, royalty revenue rose 50% to $307.7 million, of which $152.2 million came from DARZALEX, the subcutaneous myeloma drug Johnson & Johnson sells.

Management raised full-year guidance for the second time this year, to $1.835 billion to $1.910 billion of revenue and non-GAAP earnings of $8.65 to $9.00 a share, up from $7.75 to $8.25. And it bought 4.8 million of its own shares in the quarter for $332.8 million, at an average price of $69.30, under a $1 billion authorization that runs through 2028.

One U.S. patent covers the composition of rHuPH20, which is licensed in every ENHANZE agreement. And it expires on September 23, 2027. That’s why Goldman Sachs rates the stock a Sell with a $58 target. But the royalty steps down, it does not stop. Halozyme’s filings reveal that when the rHuPH20 patent expires in a country, the royalty rate is reduced rather than terminated, and the company says the reduction never exceeds 50%. Apply the worst case to the exposed share of the royalty base, and we get a hit of roughly $1.85 a share against consensus 2027 earnings of $10.31. Halozyme guides DARZALEX royalties as secure through 2032.

And there is a second platform that is not in any existing license. MDASE is a separate family of modified hyaluronidases with 99 patents and applications, exclusive through 2032 outside the United States and 2034 inside it. Every new agreement Halozyme signs can be written on MDASE rather than ENHANZE. The company has signed five new agreements this year against a goal of three, including a global oncology collaboration with GSK (GSK) in May.

And there’s a potential kicker – a big one. Halozyme sued Merck in April 2025, claiming that subcutaneous Keytruda infringes 15 MDASE patents. A German court granted a preliminary injunction against subcutaneous Keytruda in December 2025.

If you’ve watched Veeva Systems (NYSE: VEEV) over the last month – up more than 40% – you’ll understand why I prefer to own biotech’s tollbooths.

Action to Take: Buy Halozyme Therapeutics (Nasdaq: HALO) up to $110 per share

BioNTech’s Failure

On August 28, BioNTech SE (BNTX) terminated the Phase II trial of autogene cevumeran, its individualized mRNA cancer vaccine partnered with Genentech, the Roche Holding subsidiary. The shares fell 8%. We do not own BioNTech, but what happened in this failed trial is important.

The independent Data Safety Monitoring Board found a numerical imbalance in overall survival between the two arms and concluded that continuing would not change the efficacy result. Reuters reported that analysts read that imbalance as more deaths in the vaccine group than in the control group.

BioNTech enrolled patients with high-risk stage II or stage III colorectal cancer who had already had surgery, then three months of chemotherapy, and who still had circulating tumor DNA in the blood afterward. Circulating tumor DNA is what it sounds like: fragments of cancer genome floating in the bloodstream. Finding it after surgery means the surgeon did not get everything.

But the vaccine was given as monotherapy, without a checkpoint inhibitor. Moderna’s product is given with Keytruda, Merck’s checkpoint inhibitor.

Bicycle: You Are Being Paid To Own The Pipeline

Bicycle Therapeutics (Nasdaq: BCYC) is our most uncomfortable Buy.

Bicycle holds $510.1 million of cash against $96.3 million of total liabilities and no debt at all, leaving $413.7 million of net cash, or $5.96 a share. So you are paying $4.14 for $5.96 of cash, which puts the enterprise value at negative $127 million. The market is paying you $1.83 a share to buy the stock.

Bicycle makes bicyclic peptides: short chains of amino acids chemically stapled into two rigid loops, which lets a very small molecule bind a target with the precision of an antibody and then clear the body in hours rather than weeks. Attach a chemotherapy payload, and you get a tumor-seeking missile that does not linger in healthy tissue. The lead drug, zelenectide pevedotin, targets a protein called Nectin-4 that sits on the surface of bladder-cancer cells.

There is already a Nectin-4 drug, and it is a good one. Padcev, from Pfizer (PFE) and Astellas, produced a confirmed response rate of 67.7% with pembrolizumab in first-line advanced bladder cancer and did more than $1.9 billion of sales in 2025. Zelenectide’s confirmed response rate in the equivalent setting was 58% to 62% in 26 patients.

Padcev’s label carries a boxed warning for severe and fatal skin reactions. Skin reactions occurred in 70% of patients on the combination, 17% at grade 3 or 4, with fatal bullous dermatitis in 0.2%. Peripheral nerve damage occurred in 67%, and 87% of those patients still had it at last evaluation. Zelenectide, at its selected dose, produced skin reactions in 17% and neuropathy in 33%, with no severe skin reactions at any grade.

On March 17, regulators told Bicycle that its pivotal trial design would not support accelerated approval in metastatic bladder cancer. The company converted the trial to a randomized Phase II, cut 30% of its staff, and set out to reduce operating expenses by half.

Its partners left. Genentech gave notice in July 2025, and Novartis followed later that year. Bayer terminated one target program in November 2025 and the entire agreement in July 2026, effective this month. Those three deals carried $45 million to $50 million of upfront money each and up to $1.7 billion of milestones apiece. Bicycle had collected $240.2 million of partner cash across its history and now has only one active collaboration, with Ionis.

In short, the outlook looks dark. But that’s why the stock is cheap. And we believe the underlying technology holds a lot of promise. The drug is not dead, and neither is the differentiation. Bicycle is still running the randomized Phase II and expects data in the second half of this year. In the Phase I first-line study, in patients too sick for cisplatin, zelenectide plus pembrolizumab produced a 59% response rate and median progression-free survival of 13.0 months. In late-line monotherapy, 38% responded with a median duration of response of 10.0 months. Those are not failing numbers.

Meanwhile, Bicycle is moving its resources to radioconjugates: the same targeting peptide carrying a radioactive isotope instead of a chemotherapy payload. It has locked up the hard part of that business, which is not the chemistry but the fuel. Bicycle signed a 15-year contract with the UK Nuclear Decommissioning Authority for access to up to 400 tonnes of reprocessed uranium, and it is working with the UK National Nuclear Laboratory to extract thorium-228 from it. It has exclusive lead-212 generators from SpectronRx and a supply agreement with Eckert & Ziegler. Novartis built a $2 billion drug in Pluvicto and an $816 million drug in Lutathera on this idea, and the constraint on the whole field is isotope supply. Bicycle’s first company-sponsored radioligand trial starts in 2027.

Bicycle Therapeutics is a Speculative Buy, below $5.00, with a present value of $7.50.

Good investing,

F. Porter Stansberry
Stevenson, Maryland

For important disclosures and disclaimers, please visit our Legal Disclosures page.

The post The Age Of Discovery appeared first on Porter & Co..

  • ✇Market Wise
  • This explosive, high upside sector is running higher. Do you own it? Brian Hunt
    Today’s issue in preview: This explosive, high upside sector is running higher. Do you own it? This industry has enormous upside potential. How to trade it from here. The most important bull market the mainstream media isn’t covering for you Learn our Top Themes to buy now This industry has enormous upside potential. How to trade it from here Credit: Walter Cicchetti After trading sickly for two months, it looks like the trend in space stocks is getting healthy again. Money & Meg
     

This explosive, high upside sector is running higher. Do you own it?

18 August 2026 at 12:00

Today’s issue in preview:

  • This explosive, high upside sector is running higher. Do you own it?

  • This industry has enormous upside potential. How to trade it from here.

  • The most important bull market the mainstream media isn’t covering for you

  • Learn our Top Themes to buy now


This industry has enormous upside potential. How to trade it from here

Image

Credit: Walter Cicchetti

After trading sickly for two months, it looks like the trend in space stocks is getting healthy again.

Money & Megatrends readers in good standing will recall our belief that space-related industries will enjoy tremendous growth and generate many large stock market winners over the next five years.

On Sept. 22, 2025, I wrote a bullish piece on space stocks and said it’s a sector that the “public could go wild for.” I stated the bull case like this:

When people think of investing in space, they often go towards the business of launching rockets and Elon Musk’s SpaceX. But many of the most promising “space stocks” are in the business of space-based communication platforms and equipment. Think government surveillance, military communication, GPS, internet service, and cell service.

The best big picture fundamental case for space stocks right now is that the Trump administration believes America is in a hugely important competition with China and other countries for “space dominance.” This means regulatory and financial support for the U.S. space industry.

… Top performing individual space names worth checking out include Rocket Lab (RKLB), BlackSky (BKSY), Planet Labs PBC (PL), and AST SpaceMobile (ASTS).

Soon after our note, many space stocks soared 50%-100%, powered in part by anticipation of SpaceX’s (SPCX) gigantic IPO in June.

After that runup, however, space stocks experienced a large correction. I viewed this correction as natural, given its huge preceding run-up. No sector runs higher week after week in a straight line. The space trade needed to “work off” a lot of froth and enthusiasm.

As you can see in the one-year chart below of the Procure Space ETF (UFO), the space theme looks to have formed a bottom in the mid-$40 per share range.

This is also where the fund traded in a sideways consolidation earlier this year. UFO used this price level as a base to mount an assault on the $48-per-share area, which it reached last week.

This bit of positive price action is enough for me to say the space theme is likely in a healthy uptrend again, which means the tailwinds are shifting back in favor of long positions.

We still like the names above and the ETF above… and we’ll be sharing more ideas and analysis on this trend soon.

Image

Recommended Link:

“This ticker will be headline news come September 16”

Ad Image

Larry Benedict made his clients $274m because he sees what others don’t. When 2008 hit, he made $95m in a single year. He predicted the COVID crash and made $2m in a month. Now Larry is predicting September 16 will be a massive day for the markets. And there’s one ticker he’s urging his readers to pay close attention to. Click to discover the ticker.

The most important bull market the mainstream media isn’t covering for you

Image

Credit: Traimak_Ivan

If you’re looking for some good news or a reason to be optimistic on America, look no further: The Invesco S&P SmallCap Industrials ETF (PSCI) is in a bull market… and just pennies from reaching a new all-time high.

That’s good for America… and good for your 401(k).

PSCI is one of the most important ETFs you’re probably not following. It holds a diversified basket of critical but lesser-known U.S. manufacturing firms.

These companies typically don’t make the front page. There’s no “rock star” CEO like Elon Musk in this area of the market.

These firms operate with little fanfare, providing critical equipment and services the U.S. economy cannot function without. You may not know them, but you most certainly encounter their products when you walk into an office, turn on your car, or flip on the lights.

Our factories, vehicles, homes, and cities cannot function without their specialized pumps, motors, filters, fans, valves, fasteners, tools, gaskets, wiring, bearings, and switches. These businesses are the backbone of the American economy. And they are doing great.

In late 2025 and early 2026, I frequently highlighted how many critical, yet unrecognized U.S. manufacturers were reporting excellent business results and enjoying rising stock prices. At the time, PSCI was regularly registering new all-time highs.

However, PSCI suffered an Iran War-induced selloff alongside the broader market. Shares dropped 14% in six weeks. Since then, PSCI has surged to new highs. As you can see in the chart below, the fund is in a beautiful three-year uptrend.

This exceptional price strength means the economy is doing very well. We are making and buying lots of trucks, tractors, concrete, steel, engines, HVAC systems, data centers, power plants, transmission lines, and communication networks.

The stock market is one of the world’s greatest forecasting mechanisms. It tends to look ahead 6-12 months. When an industry is in a recession, its stock prices will rise before the news media says it is recovering. When an industry seems to be doing well, its stock prices will decline before the news covers its downturn. This is often called “discounting the future.”

There’s a variety of negatives at work inside the U.S. economy. Stock market bears and pessimists can find all kinds of reasons to avoid stocks. But new all-time highs in industrial stocks mean the evidence is working against them.

Image


This explosive, high upside sector is running higher. Do you own it?

Image

Credit: gorodenkoff

This morning, shares of giant biotechnology firm Amgen (AMGN) advanced 1.3% to reach a new all-time high.

Amgen is the largest holding in the iShares Nasdaq Biotechnology ETF (IBB), so its strong performance helped push the fund to a new all-time high.

These important moves mean the biotechnology bull market is alive and well… and full of opportunity. They also make our recommendation to invest in this theme a very large winner.

On Aug. 18, 2025, I sent a research note to colleagues outlining my bullish view of the biotech sector’s price action. Since then, I’ve written more than a dozen updates on the biotech bull market, as IBB has risen 46.8%, far outpacing the S&P’s 19.5% return.

IBB focuses on large biotech firms such as Amgen (AMGN), Vertex Pharmaceuticals (VRTX), and Gilead Sciences (GILD). The S&P Biotech ETF (XBI), which focuses on smaller biotechs, has risen 76.9% compared to the S&P’s 19.5% return.

The biotechnology sector comprises companies working on cures and treatments for hundreds of diseases. When investors grow interested in this industry, the returns can be incredible. During the last biotech bull market, the sector soared 300% over four years.

Biotech performed poorly from 2021 through 2025, so most investors are indifferent to it. But I see major potential here. This industry is poised to generate many stock market doubles and triples over the coming decade.

The fusion of AI plus biology will generate dozens of compelling stock narratives over the coming years. Researchers running superintelligent AI programs will be able to run millions of digital simulations of drugs and treatments. This will put medical innovation into overdrive… and create many big stock market winners.

Companies that leverage AI to “crack the code” for various diseases, treatments and drugs will enjoy 100%… 500%… even 1,000%+ stock rallies.

In many cases, these rallies will happen thanks to stories and potential… rather than a company generating revenue or earnings.

Capitalizing on many of today’s biggest stock market trends means focusing on promise over profits. The biotech sector holds the potential for both.

Biotech has another powerful factor working in its favor: Virtual anonymity.

The investment public is largely indifferent to the biotech industry right now. Investment newsletter sales related to biotech are tiny. Biotech specialists posting on X get scant attention. CNBC does not have a show devoted to biotech. Presentations on biotechnology stocks are not popular at investment conferences.

If I were to bring up biotech investing to a group of casual, amateur investors, I’d get blank stares in return. This “state of indifference” is very bullish for biotech stocks.

When the investment public is indifferent towards a powerful theme, it tells you valuations have not been bid up to unrealistic levels… so there’s plenty of room to grow into high valuations. Plus, it means there’s a lot of money on the sidelines that could eventually pile into the trend, sending it much higher.

In other words, “A strong industry uptrend + public indifference towards that industry” is one of the greatest moneymaking equations in all of finance.

Investors with the time to spend on picking individual biotech stocks and managing the positions can generate large returns in a biotech industry uptrend. For example, over the past year, at least 14 companies with “therapeutics” in their names have delivered returns of 300%+ or more.

If you don’t want to spend time researching and managing individual biotech stock positions, ETFs can get you exposure to this industry. XBI and IBB are worth considering.

The biotech industry has tremendous price momentum working in its favor… plus the investment public is largely indifferent to its success. This is a powerful combination that makes more new highs a high-probability bet.

Image


Market Notes

  • The uptrend we highlighted in psychedelic medicine stocks has become a big winner. The AdvisorShares Psychedelics ETF (PSIL) is up 55% since our bullish March 16 note. The fund is benefiting from expectations that the U.S. government will ease regulations related to psychedelic treatments.

  • Our September 2025 recommendation to own oil and gas stocks continues to be a winner. The Energy Select Sector SPDR Fund (XLE) reached a new all-time high today. XLE is the world’s largest oil stock ETF.

  • Our recommendation to own oil and gas pipeline stocks continues to be a huge winner. The Alerian MLP ETF (AMLP) reached a new all-time high this week.

  • The bull market in health care diagnostics we’ve been highlighting continues to generate winners. Diagnostics giant Labcorp (LH) reached a new all-time high today.

  • The Iran War and its constriction of Middle Eastern oil supplies continue to work to the advantage of U.S. oil refiners. Industry giants Marathon Petroleum (MPC), Phillips 66 (PSX), and Valero Energy (VLO) reached new all-time highs today.

Regards,

Brian Hunt signature

Brian Hunt signature

Brian Hunt
Editor, Money & Megatrends


An urgent message from our colleagues:

SpaceX ‘Dark Energy’ Replaces Foreign Oil

Image

For years, we’ve been told SpaceX is a rocket company. But according to new satellite images from 300 miles above the Earth’s surface, there is something very strange going on at SpaceX right now that has nothing to do with space. It could soon replace our need for foreign oil forever and ignite a $10 trillion boom for the stocks involved.

Click here to learn more.

The post This explosive, high upside sector is running higher. Do you own it? appeared first on MarketWise.

  • ✇Market Wise
  • Stocks for investing in “the next big AI trade” Brian Hunt
    Today’s issue in preview: Stocks for investing in “the next big AI trade” The FSR bull market sends us an important message: The American consumer is alive and well. Four stocks to invest in an extraordinary new AI trend Our incredible track record continues to improve: Our thematic trades in Biotechnology, Canada, Cybersecurity, and Genomics reach new highs. Learn our Top Themes to buy now Stocks for investing in “the next big AI trade” Credit: piyaset It turns out, being bullish
     

Stocks for investing in “the next big AI trade”

10 August 2026 at 12:00

Today’s issue in preview:

  • Stocks for investing in “the next big AI trade”

  • The FSR bull market sends us an important message: The American consumer is alive and well.

  • Four stocks to invest in an extraordinary new AI trend

  • Our incredible track record continues to improve: Our thematic trades in Biotechnology, Canada, Cybersecurity, and Genomics reach new highs.

  • Learn our Top Themes to buy now


Stocks for investing in “the next big AI trade”

Image

Credit: piyaset

It turns out, being bullish on genomics was a great idea.

Last Friday, shares of medical diagnostics giant Natera (NTRA) leaped 21% to a new all-time high after the company reported outstanding second-quarter business results.

Natera is a genetic testing and diagnostics company that specializes in prenatal and cancer testing. Its Signatera blood test looks for microscopic pieces of tumor DNA in a patient’s blood. Doctors use it to detect whether cancer has returned following treatment.

Business is booming for Natera. Total revenue for the company grew 38% in the second quarter, driven by surging demand for its specialized diagnostics services.

Constant Money & Megatrends readers are not surprised to see the genomics theme surge to new highs. Over the past year, we’ve written over half a dozen research notes about the extraordinary upside potential of biotech and genomics.

Genomics is the science of analyzing human DNA – often referred to as the “software code of life” – to create tests, medicines, and treatments.

Years of innovation in this field have us on the brink of creating many customized treatments based on an individual’s DNA… and even “editing” genes to cure disease. Bulls on the industry believe it will get a giant “AI boost,” because super-intelligent computer programs can analyze genes and treatment effects so well… and have the potential to create drugs on their own.

The fusion of AI and genomics should generate dozens of compelling stock narratives over the coming years. Researchers running superintelligent AI programs will be able to create useful new diagnostics and run millions of digital simulations of drugs and treatments. This will put medical innovation into overdrive… and create many big stock market winners.

The personalized approach to medicine that genomics offers has us on the cusp of a historic revolution in healthcare. Ten years from now, medicine will be transformed… and a lot of money will be made along the way.

As I mentioned on May 28, the ARK Genomic Revolution Multi-Sector ETF (ARKG) is one way to track and trade the genomics theme. It owns a basket of bleeding-edge genomic companies.

Its largest holding, Tempus AI (TEM), is often cited as a premier way to play “AI in health care.” ARKG also holds significant positions in genetic diagnostic service firms such as Natera and Illumina (ILMN)… plus positions in promising “gene editing” companies CRISPR Therapeutics (CRSP) and Intellia Therapeutics (NTLA).

Natera’s excellent business results indicate soaring use of bleeding-edge genomic analysis to detect and treat illnesses.

Natera’s excellent stock performance suggests investors are beginning to appreciate the trend. We remain bullish on the genomics megatrend.

Image

Recommended Link:

“This ticker will be headline news come September 16”

Ad Image

Larry Benedict made his clients $274m because he sees what others don’t. When 2008 hit, he made $95m in a single year. He predicted the COVID crash and made $2m in a month. Now Larry is predicting September 16 will be a massive day for the markets. And there’s one ticker he’s urging his readers to pay close attention to. Click to discover the ticker.

The FSR bull market sends us an important message: The American consumer is alive and well.

Image

Credit: RiverNorthPhotography

Over the past five trading sessions, shares of Brinker International (EAT), The Cheesecake Factory (CAKE), and Texas Roadhouse (TXRH) reached new all-time highs.

These new highs are more evidence that the bull market in Full Service Restaurants (FSR) is alive and well.

They’re also the byproduct of a strong U.S. economy. And that’s important for your portfolio…

On July 21, I highlighted the emerging uptrend in FSR stocks, including Darden Restaurants (DRI, Olive Garden, LongHorn, Yard House), along with EAT, CAKE and TXRH.

These uptrends are important because they give us an informed, real-time analysis of American consumer health.

A full-service restaurant is one where you’re seated by a host, talk to a server, have your food brought to you, and hopefully leave a nice tip. This experience is different from a fast-food restaurant such as McDonald’s or Chick-fil-A.

It is also more expensive. The typical family of four going to a full-service restaurant knows it will be spending considerably more there than at a fast-food joint.

Because FSR bills are on the higher end of the dining cost spectrum, the earnings and stock prices of leading these chains are excellent “real world” indicators that signal a lot about the financial health of the American consumer.

After all, dropping $150 on dinner is not something most people do when they are broke. It is something people are more likely to do when they are gainfully employed, making money, and optimistic about tomorrow.

Driven by strong business performance, FSR stocks are in a clear uptrend, with some breaking out to new all-time highs.

Over the past eight months, I’ve written over a dozen research notes analyzing the soaring share prices of highly economically sensitive industry groups, including trucking stocks, railroad stocks, regional banks, manufacturing stocks, steelmakers, shopping mall operators, and hotel chains.

At the end of each note, I pointed to their soaring stock prices and told readers that the U.S. economy is doing much better than most people think.

These economically sensitive firms are important “real world” indicators. They almost always do a better job of telling us what is happening in the economy than any media outlet or economist. And their uptrends are moving in a bullish upward direction for the U.S.A.

Soaring FSR stocks are key members of this growing list of positives.

Image


Four stocks to invest in an extraordinary new AI trend

Image

Credit: imaginima

Cloudflare (NET) CFO Thomas Seifert recently ran the numbers. And he says that in the near future, web traffic from AI programs will far exceed traffic from real, actual humans.

Cloudflare is a key provider of equipment and services that keep Internet sites up and running smoothly, so it has unique insight into web traffic trends.

On the company’s recent earnings call, Seifert said that in five years, non-human web traffic will be as much as 1,000 times as much as human traffic.

“In other words, humans will be a rounding error on the internet, not because human traffic goes down, but that’s just how fast we’re seeing non-human traffic grow,” Seifert said.

Avid Money & Megatrends readers won’t be surprised to hear that AI agent traffic is on the up… and will be for years.

On March 16, we urged readers to prepare for the “Agent Supernova” our nickname for the coming explosion in AI agent usage.

Years of development have made AI advanced enough to perform many everyday tasks people do now… and the list of tasks is only getting bigger.

In the next 12–24 months, AI agents will assist with managing factories… performing financial analysis… managing business inventories… writing software… designing websites… creating legal documents… and thousands of other things.

Within the next two years, the number of AI agents operating in the American economy isn’t poised to increase by 10X… or 50X… or even by 1,000X. Try at least 10,000X.

This is the coming Agent Supernova. Agents working with people. Agents working with other agents. Agents running businesses. Agents negotiating and haggling with other agents.

The Agent Supernova is about to introduce billions of “AI workers” into our economy to perform all kinds of roles… with very little day-to-day human oversight.

The business and investment implications are huge. The Agent Supernova will transform many businesses and industries, and end many as we know them… while creating new ones. The economic deck is about to get reshuffled.

The bigger the impact a megatrend can have on our world, the bigger the capital gains it can generate in your portfolio. This is why the Agent Supernova is such a big opportunity. It’s why we will be writing about and investing in this trend for years.

One compelling theme inside the Agent Supernova megatrend is internet traffic. Just one AI agent working for a business can create enormous amounts of web traffic.

Remember, agents work much faster than humans. They don’t take breaks or vacations. They can search for information and transact at the speed of light. An explosion of agent usage will generate an explosion of internet traffic.

In our initial profile of this trend, we highlighted these companies poised to benefit from it:

Cisco (CSCO): CSCO benefits significantly in the agentic world because it sells the equipment that enables data to move. CSCO provides switches (which move data between machines within a data center) and routers (which move data across networks). As AI becomes more agentic, CSCO’s infrastructure keeps these systems connected.

Ciena (CIEN): CIEN provides optical networking equipment that enables data to move at very high speeds over long distances. CIEN is one of the leaders in the optical space along with Lumentum (LITE) and Applied Optoelectronics (AAOI).

Arista Networks (ANET): ANET builds the high-speed switches that sit inside data centers, similar to CSCO. ANET has carved out a much narrower niche in AI chip-to-chip communication, which should mean it benefits more from the agentic world over the next few years. Expected revenue growth is 27% in 2026, up to $11.5 billion.

Akamai Technologies (AKAM): AKAM is a global cloud computing and cybersecurity company best known for its massive distributed network. It helps businesses deliver websites, applications, video, and digital services quickly and reliably while protecting them from cyber threats.

Since our original note, the basket above is up an average of 21%. Given that we are in the first inning of the Agent Supernova… and trends recently highlighted by Cloudflare’s CFO, we believe this trend has much further to run.

Image


Market Notes

  • Our recommendation to invest in cybersecurity via Palo Alto Networks (PANW) continues to pay off. The stock is up 143% since our March recommendation and reached a new all-time high today.

  • Our recommendation to invest in the Boomer healthcare trend continues to pay off. Healthcare diagnostics giant Labcorp (LH) reached a new all-time high today.

  • Our recommendation to invest in the genomic megatrend continues to pay off. Synthetic DNA giant Twist Bioscience (TWST) jumped 6.5% today to reach an all-time high. The stock is up 287% this year.

  • Our recommendation to invest in the defense trend continues to pay off. Defense giant RTX (RTX, formerly Raytheon) reached a new all-time high today.

  • Our recommendation to get long the biotechnology megatrend continues its winning ways. The iShares Biotechnology ETF (IBB) reached a new all-time high today.

  • Our recommendation to invest in critical resource-rich Canada is a winner. The iShares Canada ETF (EWC) reached a new all-time high today.

Regards,

Brian Hunt signature

Brian Hunt signature

Brian Hunt
Editor, Money & Megatrends


An urgent message from our colleagues:

Have YOU prepared for Trump’s New Dollar??

Image

Enacted through Executive Order 14241, issued by the U.S. Treasury – all U.S. citizens will soon be forced to use America’s new money… But only a handful will understand how to turn it into new wealth.

Don’t be left behind – get the full story here.


The post Stocks for investing in “the next big AI trade” appeared first on MarketWise.

❌